The government is working on ensuring that the name of a new company is approved within 24 hours, a step towards improving ease of doing business and reducing overall transaction costs.
Corporate Affairs Secretary Tapan Ray said his Ministry is focused on reducing the problems faced by the industry and ensuring that ease of doing business becomes the “order of the day”.
“Incorporating a company is now much easier and will be made further easier as we go along the road. We are aiming to get a name (of a new company) approved within 24 hours,” Ray said.
The Corporate Affairs Ministry is fully geared up to improve ease of doing business, not only for starting a venture but also for the life cycle of companies as a whole, he noted.
Speaking at an event organised by the Institute of Cost Accountants of India (ICAI) here, Ray said speedier approval of names is itself a cost-cutting experiment because any delay adds to transaction costs.
“So ease of doing business is directly related to transaction costs. So the moment you make the ease of doing business better, transaction costs comes down and ultimately it has an affect on the product,” Ray said.
Stressing the need for becoming globally competitive, he said the dream of making India a manufacturing hub can be realised when costs are low.
“People will only start manufacturing in India if it is the cheapest,” he added.
Corporate Affairs Ministry, which is implementing the Companies Act, has been taking various steps to improve ease of doing business in the country.
Ray said setting up of the National Company Law Tribunal (NCLT) would further facilitate business in the country.
The Ministry has sought comments from stakeholders on draft rules pertaining to the proposed NCLT, which would replace the Company Law Board (CLB).
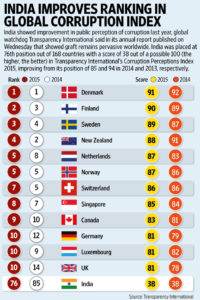
India has showed some improvement in addressing corruption this year, ranking 85th among 175 countries as against 94th last year, graft watchdog Transparency International India (TII) said on Wednesday.
Denmark retained its position as the least corrupt country in 2014 with a score of 92 while North Korea and Somalia shared the last place, scoring just 8, it said.In India’s neighbourhood, China moved to 100th place, down from 80th last year, while Pakistan and Nepal were at 126th position. Bangladesh was 145th and Bhutan 30th in the ranking. Sri Lanka was ranked 85th with India. Afghanistan was at a bleak 172.According to the Corruption Perception Index (CPI) report by TII, “the CPI score for India increased by 2 points in 2014 from its 2013 score, helping India’s rank move up to 85 in 2014 from 94 in 2013”. India’s score stood at 38 as compared to 36 last year.
The improvement in CPI for India was driven primarily by two data sources — from the World Economic Forum and World Justice Project’s (WJP) index.
“A score increase on WEF suggested businesses in India were viewing the environment favourably with regards to their perception of corruption and bribery in the country”.
The WJP score also went up reflecting the perceptions of public sector corruption coming down slightly in India, the report said.
The report noted that in terms of the new government, the CPI possibly captured the anti-corruption mandate on which the new government was elected and the possibility of some new reforms in this area.
“However, the data used for CPI mostly was collected prior to the change of government and therefore this will not reflect directly into any of the CPI sources,” it said.
To calculate India’s position this year, 9 out of 12 independent data sources specialising in governance and business climate analysis were also used.
These included Bertelsmann Foundation, World Bank and World Economic Forum. They helped in measuring perceptions of corruption in public sector and cross country comparability.
In his reaction, chairman of TII S K Agarwal, said the “new Government has got fully majority on agenda of good governance and now it’s high time to act and pass all pending anti corruption bills including the right of citizens for time bound delivery of goods and services and Redressal of their Grievances Bill”.
Indian tax authorities have resolved more than 100 cases of transfer prices with their US counterpart, involving companies from IT and ITeS sectors, in a move expected to give a boost to investment flows into the country.
The Central Board of Direct Taxes (CBDT) has said resolution of such issues follows the framework agreement signed with the US revenue authorities in January last year as part of the Mutual Agreement Procedure (MAP).
The framework will cover about 200 transfer pricing disputes involving US companies.
“More than 100 cases have already been resolved and some more are expected to be resolved before the end of this fiscal,” the CBDT said in a statement on Thursday.
The agreement with the US was finalised under the MAP provision in the India-USA Double Taxation Avoidance Convention.
It further said MAP programmes with other countries such as Japan and the UK are progressing well with regular meetings and resolution of past issues.
The CBDT said a combination of a robust advance pricing agreement (APA) programme and a streamlined MAP would be helpful in creating “an environment of tax certainty and encourage MNCs to do business in India”.
Earlier, the US bilateral APA programme was not applicable to India. “The success of the framework agreement in a short period of one year has led to US revenue authorities opening up their bilateral APA programme to India. The US is expected to begin accepting bilateral APA applications shortly,” the CBDT said.
APA, which was introduced in the Income Tax Act in 2012, provides for signing of an agreement between a taxpayer and the Income Tax department on an appropriate transfer pricing methodology for determining the value of assets and ensuing taxes on intra-group overseas transactions.
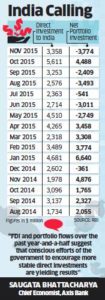
The quality of foreign investment coming into the country has improved substantially, according to Reserve Bank of India data.
Much of this is foreign direct investment (FDI) materialised in the September 2014-November 2015 period after Prime Minister Narendra Modi launched the Make in India campaign and bettered portfolio inflows during the period.
Gross FDI inflows amounted to $62.6 billion, 31% higher than $47.6 billion in the preceding 15 months.
This is more than triple the amount of net portfolio inflows of $14.3 billion in the same period. An analysis of the monthly trend in foreign investment inflows shows that in most months stable long-term FDI has been more than portfolio inflows, which have been more volatile in the period.
Economists say the surge in FDI is largely due to several initiatives by the government to attract investment in the manufacturing sector. “FDI and portfolio flows over the past year-and-a-half suggest that conscious efforts of the government to encourage more stable direct investments are yielding results,” said Saugata Bhattacharya, chief economist at Axis Bank. “At a time when global capital markets have become volatile, FDI flows reduce uncertainty about foreign capital outflows and, consequently, currency volatility.”
The surge in FDI in India is significant given that investment across the world has fallen by 16%, said Amitabh Kant, secretary at the Department of Industrial Policy and Promotion, at a recent event.
Though a sizeable amount is estimated to have gone to the manufacturing sector, including consumer goods and food processing, among others, a section of the market feels that a portion of the FDI inflows could have come through the private equity route.
This seldom finds its way into greenfield projects but at the same time provide an important source of finance for entrepreneurs.
“A significant part of the higher FDI has come in as PE and VC funding, which helps finance entrepreneurs,” said Bhattacharya.
Prime Minister Modi’s Make in India initiative is aimed at turning the country into a global manufacturing hub to generate jobs, raise incomes and drive growth.
The government has been seeking to drum up investment as part of this effort. India’s growth is being driven by public spending and consumption with private investment yet to kick in substantially.
Indian economy is less vulnerable to external shocks as it is mainly driven by household consumption and government spending, and not dependent on hot money which can move out quickly, Standard & Poor’s Rating Services said today.
The US-based rating agency expects the current account deficit (CAD), which is the difference between inflow and outflow of foreign exchange, to remain at a modest level of 1.4 per cent at the end of current fiscal and would continue at similar level till 2018.
“We see India as having limited vulnerability to external economic or financial shocks. This is because growth in the economy is mainly driven by domestic factors, such as household consumption and government spending.
“At the same time this is a country that has low reliance on external savings to fund its growth. In other words, the banks are mainly deposit funded and don’t rely on wholesale funding to grow their loan books,” S&P Rating Services India Sovereign Analyst Kyran Curry told PTI.
He said India’s capital markets are diversified and deep enough for companies to raise funding.
“Another favourable aspect of India external settings is that it is generally not subject to hot money inflows that can turn into outflows with shifts in investor sentiment. As such we see the external risks for India to be relatively contained,” Curry said.
He said while export growth may be disappointing, the current account deficit likely to be a modest 1.4 per cent in 2015, with similar levels through 2018.
“Our forecasts are partly informed by our view of increased monetary credibility, which dampens the demand for monetary gold imports. In addition, we expect India to fund this deficit mostly with non-debt, creating inflows,” Curry added.
The CAD in the first half of current fiscal stood at 1.4 per cent of GDP, lower than 1.8 per cent in the same period last fiscal. For full 2014-15 fiscal, the CAD stood at 1.3 per cent of GDP.
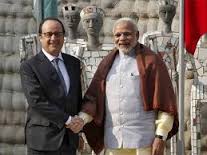
France will help India develop Chandigarh, Nagpur and Puducherry as smart cities. Agence Française de Developpement (French Development Agency) signed memoranda of understanding with the government of Union territory of Chandigarh, and government of Union territory of Puducherry and the Maharashtra government here on Sunday in the presence of French President Francois Hollande and Prime Minister Narendra Modi.
Chandigarh, designed by the French architect Le Corbusier half a century ago as a model city, is spread across 114 sq km and the urban infrastructure and green belt of the city provide it a distinguished status among India’s planned cities.
On January 26, Modi is set to announce the official list of 20 smart cities to be developed in the first phase.
A delegation of 26 CEOs from France travelled to Chandigarh with Hollande and had discussions on CEO forums to explore partnerships in renewable energy, defence, information technology and aerospace.
Modi said French companies can exploit India’s trained and affordable manpower to expand their manufacturing operations in the country. The French president committed annual investment to the tune of €1 billion to strengthen business relations with India.
An agreement between Airbus and Mahindra was also inked under Indo-French cooperation to manufacture helicopters within the Make in India initiative.
French companies will also collaborate with public sector firm Engineering Projects India to provide integrated railways solutions. The railway stations of Ambala and Ludhiana will also be redeveloped with French partnership.
The French delegation evinced interest in the areas of renewable energy, infrastructure, transport, defence, and water treatment.
The possibility of their investing, either directly in projects or through the National Investment and Infrastructure Fund (NIIF) that we have created, were both discussed,” he told reporters at the Indian High Commission in London.
Amid fears of the global economy edging close to recession, India and UK have agreed to open up trade and markets to support growth, carry out structural reforms and address issues related to cross-border tax evasion.
After talks between India’s Finance Minister Arun Jaitley and UK Chancellor of the Exchequer George Osborne, the two nation’s agreed to boost economic ties particularly in areas of infrastructure and financial services and renewed pledge for autonomical exchange of tax information from 2017.
“From the Indian point of view, we were extremely interested in having the British investors look at infrastructure investments in India for which various possibilities were discussed,” Jaitley said after the talks.
India, he said, is “extremely keen that large British companies, particularly involved in infrastructure financing, start investing in Indian infrastructure”.
The two nations will work together for developing an India-UK partnership fund under the umbrella of National Investment and Infrastructure Fund (NIIF) recently created in India.
“This fund will seek to increase flows of private sector capital and expertise alongside multilateral support into Indian infrastructure,” a joint statement issued after talks said.
The world’s fifth largest economy will work on development of smart cities in India. New Delhi is also looking at London for issuance of rupee-denominated bonds to get UK investors to fund its infrastructure projects.
“The possibility of their investing, either directly in projects or through the National Investment and Infrastructure Fund (NIIF) that we have created, were both discussed,” Jaitely told reporters at the Indian High Commission here.
With the IMF warning of global economy being close to recession with 3.4 per cent growth this year, the two sides said they “remain concerned that global growth is falling short of expectations and that the risks to the global outlook have increased”.
“In this regard we stand ready to take the necessary steps to open up trade and markets to support growth and jobs, and agree on the importance of structural reforms and pursuing credible fiscal policies,” the joint statement said.
The joint statement talked about advancement of cooperation in a range of sectors including infrastructure financing, addressing issues of cross-border tax evasion/ avoidance besides opening up of the Indian legal sector to foreign lawyers.
“The UK and India share a common commitment to address cross-border tax evasion and avoidance. Both sides have committed to the Common Reporting Standards (CRS) on Automatic Exchange of Tax Information and will begin exchange in 2017,” the statement said.
“We call on other countries to meet the commitments they have made and to implement the new standard on time,” it said.
During the talks, which included senior representatives from Finance Ministries, Central Banks and key regulators of both countries, the two leaders discussed ways to strengthen the Indo-UK existing economic partnership in order to further boost trade and investment, and to build on the success of Prime Minister, Narendra Modi’s recent summit with his British counterpart David Cameron in the UK.
“Given the fact that even in a somewhat difficult global scenario, India is managing a reasonable growth rate, this is one of the better options that investors have and that kind of a sentiment gets really echoed in the meetings with the investors that we had. Of course, the investors are also keenly watching which way our reform process in India goes,” Jaitley said.
The two nations agreed to work together on building commercial and regualtor-to-regulator links that can underpin further fintech growth in both countries.
“The UK and India agreed to renew the existing mandate of the India-UK Financial Partnership, and building on the re-establishment of the CEO Forum,” the statement said, adding that potential areas of interest for the India-UK Financial Partnership could be reinsurance, international use of the rupee, role of financial technology, financial inclusion, investor protection and green finance.
“The global economy is facing serious challenges and therefore the estimates of global growth also have been repeatedly lowered. Compared to how various countries across the world have been doing, India’s growth rate despite these challenges is probably the highest in the world among major economies,” Jaitley said, in reference to his meetings with investors at Goldman Sachs and London Stock Exchange.
As a follow up on Prime Minister Modi’s announcement during his UK visit last November on the listing of Rupee bonds in London, the minister said, “the UK is very keen for these to be listed in London and broadly the economic and financial dialogue was carried further”.
During the dialogue, the two sides recognised that as the leading financial centre in the world and in the view of successful issuance of Masala bonds issued by the International Finance Cooperation last year, London will be an attractive location for issuance of rupee-denominated bonds.
“The bonds, which were first announced during the visit of Prime Minister Modi to the UK in November, illustrate the crucial role that the UK’s capital markets can play in an enhanced economic relations relationship with India, with UK investors providing financing for the transformation of India’s infrastructure and continued rapid economic growth,” the statement said.
India and the UK also agreed that the development of deeper markets in rupee-linked products, and the increasingly sophisticated relationship between the Indian and UK financial sectors, are important underlying factors in fostering an enduring economic and financial partnership.
Both sides agreed to continue working closely on the development of smart cities in India.
“We will continue to build on and further embed the existing Technical Assistance Partnerships that were announced during Prime Minister Modi’s recent visit to the UK, and to continue working together on research collaboration and other measures to support India’s 100 Smart Cities programme,” the statement said.
While noting the strength of the economic outlook for both countries, the two sides expressed concern that global growth is falling short of expectations and that the risks to the global outlook have increased.
“In this regard we stand ready to take the necessary steps to open up trade and markets to support growth and jobs, and agree on the importance of structural reforms and pursuing credible fiscal policies in order to raise living standards,” it said.
India and the UK also agreed to work together with the aim of developing an Indo-UK partnership fund under the umbrella of the NIIF. The fund will seek to increase flows of private sector capital and expertise alongside multilateral support into Indian infrastructure.
The working group to be established will report back within the course of 2016 on a proposed fund strategy and delivery approach, the statement said.
“As part of this, India and the UK also both recognise the importance of identifying the sector or sectors where there is greatest potential for developing sustainable project pipelines, and of developing a supportive institutional environment for investment and delivery,” it said.

 The government is working on ensuring that the name of a new company is approved within 24 hours, a step towards improving ease of doing business and reducing overall transaction costs.