Capital markets regulator Sebi on Wednesday said its actions against auditors for faulty audits are within its “Parliamentary mandate”, and there is no question of “turf wars” on this issue.
SEBI Chairman Ajay Tyagi said the watchdog is working only to protect the interests of investors and limiting its actions to auditors of publicly listed firms.
In 2018, the regulator banned Price Waterhouse for two years from auditing any listed firm for its role in the Satyam Computer Services scam. However, the audit firm had successfully challenged the same in the Securities Appellate Tribunal and got the order quashed.
“It is our parliamentary mandate I would say to see that it is done and there is no trouble there. It goes to the basic issue of investor protection being the parliamentary mandate of Sebi,” he noted.
In November, the Supreme Court stayed a SAT order which had held that Sebi does not have the power to bar auditors.
“Our position is very simple — if they’re auditing listed companies based on which investors are investing, and if we find that that work has not been done properly and in investors’ interest, some audit firms should not be allowed to audit for sometime of the listed companies,” Tyagi said at an event here.
According to Tyagi, audit firms are important gatekeepers who help companies put out results and financial performance to the stock exchanges, based on which investors take the call whether to invest or not.
“It is not our case that Sebi is the agency which registers or regulates the auditors. It is nothing like that… We are not de-registering auditors. We don’t have the authority and we don’t wish to have that authority,” he said.
He also made it clear that Sebi’s expectation is that faulty audits should not lead to inflated profits or dividends.
Regarding IPO market, Tyagi said there has been an improvement in activities lately and that nearly a dozen issues of over Rs 15,000 crore are in the pipeline.
The regulator has given its wish-list for the budget to the finance ministry, includes ways to increase the activities in the corporate bond market, he said.
The government, in creating disciplinary mechanisms, could consider bringing in disclosure norms for auditors with respect to non-audit services and fees charged by them
The Ministry of Corporate Affairs is planning to amend the Chartered Accountants Act to build disciplinary mechanisms for removing possible conflicts of interest between audit firms and companies they audit.
The government is also looking at ways to address the gaps in the law with respect to network entities of which audit firms are part.
“We need to strengthen the Chartered Accountants Act. Many entities need to be brought within the regulatory remit to create accountability and transparency,” a senior government official told Business Standard.
The government, in creating disciplinary mechanisms, could consider bringing in disclosure norms for auditor with respect to non-audit services and fees charged by them
A government-appointed panel on regulating auditors and the networks had suggested that the fee from non-audit services should not be more than 50% of the audit fee.
India is considering tougher rules for audit firms, including a cap on the number of listed companies they can examine, according to a person with knowledge of the matter, as the government seeks to tighten oversight after a recent spate of governance lapses.
In India, 70% of the about 1,800 companies that trade on the National Stock Exchange are audited by firms affiliated to EY, Deloitte & Touche, KPMG and PWC, according to Delhi-based Prime Database. Current rules stipulate that individual auditors can examine accounts of up to 20 companies, though there is no limit on number of audits for the company.
The Big Four in India operate through a network of local chartered accountants firms. One way for them is to partner as a member of a local firm. They can also allow their brand name to be used by sub-licensee of a member local firm. The ministry hasn’t decided if the cap on audits will be at the group level or on each member firm, the person said.
The government is planning to expand the list of services which can’t be offered by statutory auditors under the Companies Act. Currently, statutory auditors can’t offer nine services, directly or indirectly, including internal audit, investment banking, and actuarial services. There is no restriction on providing services such as taxation or restructuring and valuation.
One option is to tweak the present cap on fees that can be generated through offering non-audit services, the person said. This cap, fixed in 2002, says fees from non-audit work can’t be more than the aggregate statutory audit fees. A spokeswoman for the corporate affairs ministry declined to comment.
A government-appointed panel on regulating auditors and the networks had suggested that the fee from non-audit services should not be more than 50% of the audit fee.
Deloitte Ban
Governance lapses and negligence has loaded the nation’s banks with one of the world’s worst piles of bad debt. In some cases, allegations of fund diversion have surfaced, while the founders of some shadow banks have faced accusations of accepting kickbacks in exchange for loans.
The corporate affairs ministry earlier this month sought a ban on Deloitte Haskins & Sells and BSR & Co. for their role as auditors to IL&FS Financial Services, a part of the IL&FS Group that was seized by the government last year after a string of debt defaults.
Deloitte in an emailed statement said it’s fully compliant with Indian audit standards, while BSR said it would defend its position in accordance with the law.
Meanwhile, the banking regulator forbid EY affiliate S. R. Batliboi & Co. from taking on bank audits for a year and, in 2018, the markets watchdog banned the local unit of PricewaterhouseCoopers LLP for two years in relations to work from a decade earlier.
Clarification on Auditor’s Certificate on Return of Deposits pursuant to Rule 16 of the Companies (Acceptance of Deposits) Rules, 2014
This has reference to Rule 16 of the Companies (Acceptance of Deposits) Rules, 2014 and further amendments.
In this regard, the Ministry of Corporate Affairs vide its letter no. File No: P-01/08/2013- CL-V Vol. VI dated June 24, 2019 has clarified on the matter as under:
The Auditor’s Certificate is mandatory only in case of return of deposits.
For filing particulars of transactions not considered as deposits information contained therein as on 31st March of that year need not be from the duly audited Financial Statement.
Only in case of Return of Deposit information contained therein as on 31st March of that year should be from duly audited financial statement of the company.
Also in order to provide guidance to members, the Auditing and Assurance Standards Board of ICAI has issued Illustrative Auditor’s Certificate on Return of Deposits, which is available on the below cited link:
With a spate of corporate irregularities coming to the fore, the Centre has decided to make disclosure norms more stringent. Corporate India is now required to submit details of transactions involving the receipt of money or loans taken by them, which are otherwise not considered deposits.
Every company other than Government company to which these rules apply, shall on or before the 29th day of June, of every year, file with the Registrar, a return in Form DPT–3 along with the fee as provided in Companies (Registration Offices and Fees) Rules, 2014 and furnish the information contained therein as on the 31st day of March of that year duly audited by the auditor of the company.
Form DPT–3 shall be used for filing return of deposit or particulars of transaction not considered as a deposit or both by every company other than Government company.
Due Date of the Form DPT-3 – Return of Deposits: Every company shall on or before the 30th day of June, of every year, file a return of deposit with the Registrar and furnish the information contained therein as on the 31st day of March of that year duly audited by the auditor of the company.
Due Date of the Form DPT-3 (ONE TIME): Form DPT-3 one time Due Date – all companies would be required to file Form DPT-3 one-time on or before the 29th June 2019
DPT-3 Due Date (EVERY YEAR): Form DPT-3 every year on or before 30th June of the preceding year.
Auditor of Company prepare the financial statements which include the following (Audited Copy)
Balance sheet,
Profit and loss account
Income and expenditure account
Cash flow statement
Statement of changes in equity
Due Date: 29th May 2019
Penalty On the defaulting company A fine of minimum Rs. 1 crore or twice the amount of deposit so accepted, whichever is lower, which may extend to Rs.10 crores; and
Every Officer who is in default: Imprisonment up to seven years and with a fine of not less than Rs. 25 lakh which may extend to Rs. 2 crores.
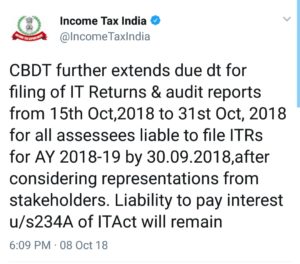
The Central Board of Direct Taxes (CBDT) has further extended due date for filing Income Tax Returns and Audit Reports to October 31st.
The due date for filing of Income Tax Returns and Audit Reports for Assessment Year 2018-19 is 30th September, 2018 for certain categories of taxpayers.
The CBDT had earlier extended the date for filing of Income Tax Returns and various reports of Audit to 15th October 2018.
Upon consideration of representations from various stakeholders, CBDT further extends the ‘due date’ for filing of Income Tax Returns as well as reports of Audit (which were required to be filed by the said specified date) from 15th October, 2018 to 31st October, 2018 in respect of the said categories of taxpayers.
However, as specified in earlier order dated 24.09.2018, assessees filing their return of income within the extended due date shall be liable for levy of interest as per provisions of section 234A of the Income-tax Act, 1961.
SEBI has proposed giving the board of directors of the company the authority to take appropriate action after conducting an investigation against the individual or firm that violates any regulations or submits a false certificate or report.
India’s capital market regulator has proposed amendments to tighten laws governing auditors and other third-party individuals hired by listed companies for auditing financial results, among other things.
The Kotak Committee, formed to come up with proposals for improving corporate governance, last year recommended that the Securities and Exchange Board of India (SEBI) should have clear powers to act against auditors and other third-party individuals or firms with statutory duties under the securities law.
Auditing lapses have caused several frauds to go unnoticed for years and the capital market regulator has had no direct control on the auditing firms.
SEBI has proposed giving the board of directors of the company the authority to take appropriate action after conducting an investigation against the individual or firm that violates any regulations or submits a false certificate or report.
The proposed changes come months after Punjab National Bank, India’s second largest state-run lender, stunned markets after uncovering a $2 billion loan fraud that had gone undetected for years.
Merchant bankers, credit rating agencies, custodians, among others, are registered and regulated by SEBI but chartered accountants, company secretaries, valuers and monitoring agencies do not come under any direct regulators.
The amendments would mean auditors must ensure certificates or reports issued by them are true in all material respects and they must exercise all due care, skill and diligence with respect to all processes involved in issuance of the report or certificate.
The auditors would be responsible to report in writing to the audit committee of the listed company or the compliance officer on any violation of the securities law they noticed.
In January, SEBI barred Price Waterhouse from auditing listed companies in India for two years after an investigation into a nearly decade-old accounting fraud case in a software services company that became India’s biggest corporate scandal.
SEBI has sought feedback and comments on the draft regulations over the next 30 days.

 Capital markets regulator Sebi on Wednesday said its actions against auditors for faulty audits are within its “Parliamentary mandate”, and there is no question of “turf wars” on this issue.