ITR filing date extended to October 31

Tax payers who were supposed to file their income tax returns by September 30 now have some more time on their hands. The government has extended the deadline to file income tax returns for such tax payers until October 31.

“The ‘due-date’ for filing Income Tax Returns and various reports of audit prescribed under the Income-tax Act,1961 has been extended from 30th September, 2017 to 31st October, 2017 for all taxpayers who were liable to file their Income Tax Returns by 30th September, 2017,” Ministry of Finance said.

This time tax payers will have to quote their 12-digit Aadhaar number or the 28-digit Aadhaar enrolment number while filing the income tax return.

You will have to keep the Form 16, which you got from their employer handy. If you don’t have it, get it asap. Download the Form 26AS from the Income Tax e-filing website. Form 26AS is a consolidated tax statement which states tax credit statement of all taxes received by the Income Tax Department against your PAN number. You will need it to tally with your Form 16.

Availability of the detail of bank accounts in which the refund is to be credited is a precondition for direct credit of refund in bank accounts. Refund generated on processing of return of income is currently credited directly to the bank accounts of the tax-payers. Non-residents, who are claiming refund but do not have bank accounts in India may furnish details of one foreign accounts in ITR for issuance of refund.

Bank accounts details

A tax payer is also required to disclose his/her bank account number along with the IFSC code. However, dormant accounts which have been in use for the past three years or more need not to be mentioned.

Mandatory disclosure

According to the Income Tax Department now, tax payers have to disclose information of cash deposited in their bank account aggregating to Rs 2 lakh from November 11 to 30 December, 2016.

Ensure that ITR is compliant with amount deposited in bank accounts during the period of demonetisation

Besides that, if any assessee has any unexplained income or investments, he has to report such unexplained income in the new ITR forms and such amount will be taxable at the tax rate of 60 percent plus surcharge and cess.

Tax deductions

  • If you are claiming tax deductions under 80C, you should keep the following details handy:
  • Investment details (eg: LIC, PPF, NSC)
  • Home loan
  • LTA
  • Medical

Consequences of Late filing of Return

According to ClearTax, if there are any taxes which are unpaid, penal interest at 1 per cent per month or part thereof will be charged till the date of payment of taxes .Also Penalty of Rs 5,000 may be charged. The penalty is not levied in all cases and depends upon the circumstances of the case.

For returns of FY 2017-18 and onwards, penalty of Rs 5,000 will be charged for returns filed after due date but before 31st December. If returns are filed after 31st December, a penalty of Rs 10,000 shall apply. However, penalty will be Rs 1,000 for those with income upto Rs 5 lakh.
Who has to file?

Every person whose gross total income exceeds the taxable limit must file an Income Tax Return (ITR)

Who has to file?

Every person whose gross total income exceeds the taxable limit must file an Income Tax Return (ITR)

Who has to e-file?

  • Individuals & HUF having total income exceeding Rs 5 lakh or claiming any refund in the return (excluding individuals of the age of 80 years or more who are furnishing return in Form no. ITR-1 or ITR-2).
  • Individual or HUF, being a resident other than not ordinarily resident, having any foreign asset/income or claiming any foreign tax relief.
  • Persons filing ITR in Form no. 3, 4, 5 or 7.


Source: Business Today


Banks’ auditors under lens: RBI seeks explanation on differences in write-downs

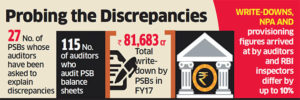
According to RBI data, PSU banks in FY17 have written off Rs 81,683 crore against Rs 2.49 lakh crore in the past five years.

The Reserve Bank of India (RBI) has questioned scores of auditors at 27 public sector banks on the process and logic they had used to compute and report write-downs at the lenders, two people close to the development told ET.

The RBI has sought written explanation on differences in the write-down assessments by its own inspectors and those certified by the auditors. A write-down is a reduction in the estimated and nominal value of an asset, and is charged off as a loss to the profit and loss account for the relevant period. In some cases, the RBI has also questioned the provisioning methodology and non-performing asset (NPA) figures arrived at by the auditors at a few public sector banks, sources told ET.

The banking regulator is examining whether auditors at these state-run lenders followed RBI guidelines on write-downs, provisioning and NPAs. “This is part of RBI’s annual assessment. Auditors will have to explain how they provisioned for NPA and how they calculated write-downs,” said a person aware of the matter.

The write-downs, NPA and provisioning figures arrived at by the auditors and RBI inspectors differ by up to 10%.

WRITE-DOWNS & PROVISIONING
According to RBI data, PSU banks in FY17 have written off Rs 81,683 crore against Rs 2.49 lakh crore in the past five years. In a few cases, the audit reports of some of these lenders do not reflect these write-downs, said one of the persons cited above. Most banks do not separately report write-downs in their accounts, combining them often with quarterly provisioning.

Most Indian public sector banks use more than one auditor due to the enormous size of their balance sheets. Most auditors are mid-to-small Indian firms that audit several branches. The 27 public sector banks collectively employ 115 auditors, according to data analysed by the ET Intelligence Group.

According to the people in the know, auditors at State Bank of India, Punjab National Bank, Bank of Baroda, Canara Bank, Allahabad Bank and Bank of India (BoI) were sent the show-cause notices about two weeks ago.

ET’s detailed email queries to the regulator and the affected lenders – SBI, PNB, BoB, IDBI, Indian Overseas Bank, Canara Bank, BoI, Oriental Bank of Commerce (OBC) and Allahabad Bank – did not elicit any response.

REGULATOR HAS PRIVILEGED ACCESS’
According to a major bank’s auditor who did not wish to be identified, the differences are not unexpected. “The RBI has access to information an auditor may not. Like, if a loan in bank X has gone toxic, the auditor of bank Y may not know, but the RBI would,” he said. He added that there is a time lapse between auditors preparing an account and the RBI conducting inspections. “What you must look at is the impact on the P&L of a bank due to divergence. In most cases, that is not much,” he said.

To be sure, there may have been ‘technical’ errors in interpreting the writedown rules, resulting in the differences. “There is a direct impact of the new accounting standards on the way write-downs are arrived at,” said a senior executive at a top audit firm. “Under the old accounting system, the rules around write-downs were not as precise, and there is a possibility that some auditors may have ignored this.”

Source: Economic Times

Rotation of auditors and its side effects

The Companies Act, 2013, has introduced important audit reforms. One of the important reforms is rotation of the auditor.

Important provisions under this reform

  • All listed companies; unlisted public limited companies having paid-up share capital of Rs 10 crore or more; all private limited companies having paid-up share capital of Rs 20 crore or more, and all companies having public borrowings from financial institutions, banks or public deposit of Rs 50 crore or more are required to rotate their auditor.
  • An individual cannot continue as an auditor for more than one term of five years and an audit firm cannot continue as an auditor for more than two terms of five years
  • The cooling off period is five years.
  • The provision must be complied by April 1, 2017.

Benefits of this reform

  • This is expected to improve audit quality, resulting in improved financial reporting.
  • Would give local auditors more leverage, if implemented properly along with some other measures.

Local auditors v/s the Big Four

  • Local firms dominate the Indian audit market. However, the presence of the Big Four audit firms (Deloitte, PWC, E&Y and KPMG) cannot be ignored.
  • The Big Four are the largest professional service network in the world. They provide audit, assurance, tax, consulting, advisory, actuarial, corporate finance and advisory services. In India, they cannot provide audit services directly.
    • It is alleged that they flout rules while providing audit and assurance services. Many foreign investors put a condition that the auditor of their choice should be appointed. This helps the Big Four audit firms to grow in India.
    • There is an apprehension that many companies that get their accounts audited by local firms will appoint one of the Big Four or another large international professional service network as auditors.
    • Hence, the Ministry of Corporate Affairs had notified the constitution of a three-member expert group to look into the complaint that the Big Four are circumventing rules and to find ways to help local firms.

Should the government intervene?

  • Local auditors are mostly present in tier 2 and tier 3 cities and audit 62 % of the companies listed on BSE 500.
  • They provide a variety of services to small companies. They lack aspiration to become big.
  • Therefore, it is debatable whether there is a case for government’s intervention to protect local audit firms

Way ahead and Conclusion

Chartered accountants are prohibited from soliciting professional work through advertisement or otherwise. But they can respond to tenders.

  • The practice of issuing a tender for the appointment of internal auditors is quite common among public enterprises. Such a practice is not common among private-sector companies.
  • Tendering is the right method to search for the right audit firm. This increases choice and reduces auditing cost through competition.
  • Companies should not limit their choice to the Big Four and other international firms or a few large local audit firms.
  • There are local firms that have capabilities to audit large and complex transactions. Search through tendering process would help to identify such firms.

It will be interesting to see how the new rules regarding rotation of auditors will actually impact the auditing profession.


Source: http://www.business-standard.com/article/opinion/rotation-of-auditors-and-its-side-effects-116100900736_1.html

Now, listed companies’ management to explain audit qualifications : SEBI

Markets regulator Sebi today asked listed companies to disseminate cumulative impact of audit qualifications in a separate format along with the annual audited financial results to the stock exchanges.

Besides, the management of a company would be required to explain its view about audit qualifications.

The new framework would ensure that the impact of audit qualifications are clearly communicated by the companies concerned to their investors in a timely manner apart from streamlining the whole process.

Sebi decided to have the new system on audit qualifications after extensive discussions with its advisory committees, Institute of Chartered Accountants of India (ICAI), stock exchanges and industry bodies.

Now, listed entities will be required to disclose the cumulative impact of all audit qualifications on relevant financial items in a separate form called ‘Statement on Impact of Audit Qualifications’ instead of the present form.

Such disclosures will have to be made in a tabular form, along with annual audited financial results filed in compliance with the listing regulations.

The new mechanism will be applicable for all the annual audited standalone/consolidated financial results, submitted by the listed entities for the period ended March 31, 2016 and thereafter.

The listed entity will have to furnish a declaration in case there are no audit qualifications.

In case of audit reports with modified opinion, a statement showing impact of audit qualifications will be filed with the stock exchanges in a format specified by the regulator, Sebi said in a circular today.

Issuing a format for ‘Statement on Impact of Audit Qualifications’ for the financial year, Sebi said that companies will have to disclose net profit, networth, turnover, total expenditure, earning per share, total assets and liabilities.

Besides, the firms will have to make submission about details, types, frequency of audit qualification. The management will have the right to give its views on the audit qualification.

Also, the management of the listed entity will have explain its views on the audit qualifications.

“Where the impact of the audit qualification is not quantified by the auditor, the management shall make an estimate. In case the management is unable to make an estimate, it shall provide reasons for the same. In both the scenarios, the auditor shall review and give the comments,” Sebi noted.

Source: http://www.business-standard.com/article/pti-stories/now-listed-cos-management-to-explain-audit-qualifications-116052700918_1.html