RBI may allow you to be a lender (P2P)

The RBI’s move to regulate the peer-to-peer (P2P) lending business has evoked good response with most participants saying that it could provide greater confidence to lenders and borrowers, as also to venture capitalists. The space has some 35 startups now and more than 20 of them were founded just last year, according to data from startup tracking platform Tracxn. They have collectively attracted only $7.5 million in venture funds, and the ones that have received the most funds include Faircent, Milaap, iLend, RangDe, LendenClub and LoanCircle.

“VCs have so far shied away from the industry due to lack of recognition and regulation of the segment,” says IDG Ventures partner Karan Mohla, adding that the proposed regulation will help the sector grow the way microfinance did.

P2P lending typically involves a technology platform that brings together borrowers and lenders, often individuals. The borrower can place his/her requirements,  and lenders can bid to service that borrower. Normally, the platforms insist on more than one lender servicing a single borrowing requirement to reduce risks. The interest rate may be set by the platform or by mutual agreement between the borrower and lender, or through an auction where lenders place bids. The platform does a preliminary assessment of the borrower’s creditworthiness, and they also collect the loan repayments. Over time, the platforms could automatically develop creditworthiness scores. Borrowers and lenders both pay a fee to the platform for these services. The average interest rates on these platforms tend to be high at 20% and the loan amount is an average of around Rs 1 lakh. Most borrowers are self-employed or those with salaries above Rs 6 lakh per annum. Most platforms charge around 2.5% of the loan amount as commission, from both parties.

The RBI is looking at factors such as what should constitute P2P lending, the legal framework, whether to set a maximum interest rate, and how to differentiate it with crowd-funding. It is, for now, looking to categorize them as non-banking financial companies (NBFCs).

“The potential benefits that P2P lending promises to various stakeholders (to borrowers, lenders, agencies, etc) and its associated risks to the financial system are too important to be ignored,” says the RBI consultation paper. The UK-based Peer-to-Peer Finance Association (P2PFA) estimates that lending through the channel globally has grown dramatically from 0.2 billion pounds in the first quarter of 2012 to 5.1 billion pounds in the first quarter of 2016.

Apoorv Sharma, founder of Venture Catalyst and an investor in LenDen, says P2P in India is still in its early stages but the government’s involvement could drive rapid growth.

Faircent, one of the largest platforms in the country, believes that the new norms will accelerate the growth in the sector – similar to how RBI regulations helped the e-wallet sector. The company has raised funding from Aarin Capital, M & S Partners and others. It has disbursed more than Rs 4.5 crore to beneficiaries so far and it is looking at loans of more than Rs 60 crore this fiscal.

Abhishek Periwal, founder of P2P platform KountMoney, said that regular banking channels don’t cater to lots of self-employed people. “P2P lending platforms come into play here, as they are faster than banks and NBFCs,” he said. Bhavin Patel, founder of LenDen Club, which started in 2015, believes the RBI regulation will be a confidence booster but has reservations about the regulator’s proposal that payment should happen directly between the borrower and the lender and that P2P platforms should have brick-and-mortar offices. He thinks the former will make monitoring and control difficult, and the latter is unnecessary. “A lot of our plans have been put on hold due to these uncertainties,” said Patel, whose platform has more than 2,000 borrowers and 900 lenders.
Source: http://economictimes.indiatimes.com/articleshow/52183326.cms?utm_source=contentofinterest&utm_medium=text&utm_campaign=cppst.

Forex reserves hit record high at $359.917 bn

India’s foreign exchange reserves continue to rise to hit a record level of $359.917 billion as on April 8, data from the Reserve Bank of India (RBI) show.

India’s foreign exchange reserves continue to rise to hit a record level of $359.917 billion as on April 8, data from the Reserve Bank of India (RBI) show.

The central bank data show that in the week-ended April 8, India’s forex reserves rose by $157.40 million from the previous week.

As on April 8, foreign currency assets (FCA), which forms a key component of the reserves rose by $159.3 million from the previous week to $335.845 billion. FCA are maintained in major currencies like US dollar, euro, pound sterling, yen, etc. However, the foreign exchange reserves are denominated and expressed in US dollar only.

The movements in the FCA occur mainly on account of purchase and sale of foreign exchange by the RBI in the foreign exchange market in India, income arising out of the deployment of the foreign exchange reserves, external aid receipts of the central government and revaluation of the assets.

Gold reserves, however, remained unchanged at $20.115 billion. Special drawing rights (SDR) from the International Monetary Fund fell by $0.90 million from the previous week to $1.501 billion.

SDR is an international reserve asset created by IMF and allocated to its members in proportion of the members’ quota at IMF. The country’s reserve position in the IMF, however, fell by $1 million to $2.455 billion.

Source: http://www.financialexpress.com/article/industry/banking-finance/forex-reserves-hit-record-high-at-359-917-bn/237598/

NRIs with offshore bank accounts cannot escape investigation by tax authorities

Governed by rules and conventions of banking secrecy, banks in Switzerland and tax havens divulge information only after account holders give their consent.

Even NRIs with offshore bank accounts cannot keep the taxman at bay by obtaining quick relief from the court of law. In order to prove their innocence, such persons will have to instruct the overseas banks to share information on the accounts with the Indian tax office.

And, only after the details released by the bank show that the money lying in the account does not belong to the person who has been pulled up (for hiding offshore assets), can he escape the glare of tax officials.

The Bombay High Court recently dismissed the writ petition filed by an NRI — an alleged beneficiary of a trust linked to an account with HSBC Geneva — after she refused to sign the “consent waiver” form to let HSBC share the information on the account. Governed by rules and conventions of banking secrecy, banks in Switzerland and tax havens divulge information only after account holders gives their consent.

The court, in its order dated April 5, said, “In the normal course of human conduct if a person has nothing to hide and serious allegations/questions are being raised about the funds, a person would make available the documents which would put to rest all questions which seem to arise in the mind of the authorities.”

Since the court did not allow the withdrawal of petition, the order is likely to be used by the tax office which is trying to fish out bank account and transaction details from those it suspects to have accounts with HSBC Geneva.

According to the base note that the French government had shared with New Delhi, the petitioner Soignee R Kothari, along with six other individuals and two trusts, are beneficiaries of an account held by one White Cedar Investments with HSBC Geneva; the seven individuals in turn are beneficial owners of the two trusts.

As on 26 March 2006, the account had a balance of more than $44 million. The department had served Ms Kothari a notice to reopen assessment for the assessment year 2006-07.

She has later agreed (in a rejoinder before the court) to sign the consent waiver form with a modification — as ‘alleged beneficiary’ rather than ‘holder or beneficiary’ of the account in HSBC Geneva.

“With this, the Bombay High Court has precluded any alleged holder of overseas bank account from seeking alternative remedy by way of a writ. However, their right to contest any addition of income by the tax authorities would still survive. Thus, while NRIs can prove that they are outside jurisdiction of Indian tax authorities, they cannot wriggle out of investigation by virtue of being NRIs,” said senior chartered accountant Dilip Lakhani. The other six alleged beneficiaries of the trust are Arun Ramniklal Mehta, Russell Mehta, Viraj Russell Mehta, Rihen Harshad Mehta, Naina Harshad Mehta and Priti Harshad Mehta.

The court said that this bank statement if obtained from HSBC Geneva “would reveal and/or possibly give clues as to the source of amounts deposited in the Account No. 5091404580.” “If a person has nothing to hide, we believe the person would have co-operated in obtaining bank statements,” said

Source : http://economictimes.indiatimes.com/articleshow/51870910.cms


Private sector lender Federal Bank to support startups

Jumping on to the startup bandwagon, Kerala based private sector lender Federal BankBSE -1.38 % is opening incubation centres in Bangalore and Ernakulam exclusively for startups. These would be specialised lounges within Federal Bank branches meant for funding advisory, regulatory support and if required even for direct investment.

“We have a dedicated startup fund worth Rs 25 crore which we would like to use to fund or lend to promising startups. These lounges, named Launchpad, with fast internet connections, support staff from the financial world and advisory mechanisms would be the perfect breeding ground for future entrepreneurs,” said Shyam Srinivasan, managing director, Federal bank.

The lounge would be manned by bank officers who would be capable of dealing with the financial requirements of the startups as well as local specialists who would be able to advise on regulatory issues that entrepreneurs need to handle.

“We are talking to 3 or 4 startups daily. The challenge for a bank is to move away from a conservative credit mind set to a more entrepreneurial mind set and to accept the fact that out of 40 or 50 investments only one might take off. So even we are in the process of understanding how to engage with startups better,” he said.

The bank follows the footsteps of HDFC Bank and Bank of Baroda to integrate their platform with mobile payments application Chillr. The addition that Federal Bank brings to the Chillr app is that they would allow even non Federal Bank users to instantly open a Federal Bank account through a selfie and Aadhar identification number and allow them to receive payments through Chillr.

“This is just another offer in the suite of offerings for the customer. We are in the major discovery process slowly there would be convergence in this field,” said Srinivasan.

New bankruptcy bill to speed up shutdown of failed businesses

Panel has sought the overhaul of the bankruptcy framework to allow the speedy winding up of failed businesses to protect shareholders and lenders, aiming to modernise an outdated system.

A government panel has sought the overhaul of the bankruptcy framework to allow the speedy winding up of failed businesses to protect shareholders and lenders, aiming to modernise an outdated system that drags out closure proceedings.

It has recommended new institutions and structures for a fresh regime that will encourage entrepreneurship and foster a startup culture, among the stated objectives of the Narendra Modi administration. The government has indicated it will move a Bill in the winter session of Parliament to give effect to the recommendations, addressing one of the key issues that has kept India low on the ease of doing business rankings.

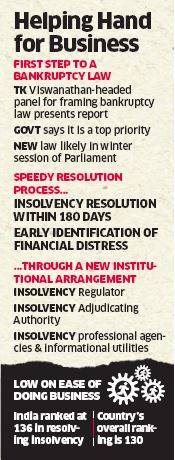
The Bankruptcy Law Reform Commission headed by former law secretary TK Viswanathan has proposed insolvency resolution within 180 days and a new regulator to oversee the process. It’s also laid down a clear and speedy system for early identification of financial distress and revival of companies.

The timelines are on par with international norms for insolvency resolution. “The endeavour would be to introduce the Bill in the next session of Parliament,” Finance Minister Arun Jaitley said at the World Economic Forum in the Capital on Wednesday. Viswanathan submitted the report to the minister later in the day. The report, along with the draft legislation, has been made public for feedback. “The Bill seeks to improve the handling of conflicts between creditors and debtors, avoid destruction of value, distinguish malfeasance vis-a-vis business failure and clearly allocate losses in macroeconomic downturns,” the report said.

The World Bank has ranked India at 136 out of 189 countries in ‘resolving insolvency,’ estimating that it takes 4.3 years on average in Mumbai to settle a case.

Jaitley had identified bankruptcy law reform as a key priority for improving ease of doing business in his February budget speech. He said that a comprehensive bankruptcy code, meeting global standards and providing the necessary judicial capacity, would be unveiled in the fiscal year. Under the current system, proceedings take several years, hurting investors and lenders besides costing taxpayers crores of rupees.

Banks are groaning under bad debt stemming from projects that have got stuck, drawing the Reserve Bank of India’s concern. “We need a bankruptcy code. We need equity to be seen as equity and debt to be seen as debt. Today there’s a lot of confusion… We need that confusion to be changed,” RBI Governor Raghuram Rajan has said previously.

90 Days for Key Categories. The prescribed resolution timeline of 180 days can be cut further to 90 days from the trigger date for key categories. The proposed insolvency regulator will cover professionals and agencies specialising in the field.

The proposals include information utilities that will collect, authenticate and disseminate financial information from listed companies. An Insolvency Adjudicating Authority will hear cases by or against debtors. The Debt Recovery Tribunal should be the adjudicating authority with jurisdiction over individuals and unlimited liability partnership firms, it said. The National Company Law Tribunal (NCLT) should be the adjudicating authority with jurisdiction over companies and limited liability entities, it added.

The draft bill has consolidated existing rules relating to insolvency of companies, limited liability entities, unlimited liability partnerships and individuals, all of which are currently scattered across a number of laws, into a single legislation.

According to the draft bill, during the transition phase, the Centre will exercise all regulatory powers until the agency is established. The panel’s report suggests that an insolvency resolution plan prepared by a resolution professional has to be approved by a majority of 75% of the voting share of financial creditors. As part of the insolvency resolution process, creditors and debtors will engage in negotiations to arrive at agreeable repayment plans.

The draft proposes that any proceeding pending before the Appellate Authority for Industrial and Financial Reconstruction (AAIFR) or the Board for Industrial and Financial Reconstruction (BIFR) before the new law goes into force should stand abated or stopped.

“However, a company in respect of which such proceeding stands abated may make a reference to Adjudicating Authority within 180 days from the commencement of this law,” the recommendation said, keeping in view continuity of the process. Minister of State for Finance Jayant Sinha said the required infrastructure needed to be put in place.

“We also have to ensure that necessary judicial capacity is available,” he said. “We also need to resolve many of the situations immediately because they are short of cash in most of these bankruptcy types of cases.” The minister said the government was trying to put together a comprehensive solution where “we can resolve default and bankruptcy cases as quickly and efficiently possible.”

Industry feels the new system will create a robust and globally competitive insolvency regime. This will significantly reduce the time taken for insolvency proceedings in India, which at present, on an average basis is estimated at about 4.3 years as against only 1.7 years in high-income OECD countries,” said Chandrajit Banerjee, director general of the Confederation of Indian Industry.

“The architecture proposed by the Viswanathan committee of establishing an insolvency regulator to have oversight of the new class of insolvency professionals, agencies and information utilities will enhance the systemic efficiency of dealing with insolvency cases in a timebound manner,” he said.

Source: http://articles.economictimes.indiatimes.com/2015-11-05/news/68043912_1_bankruptcy-framework-new-bankruptcy-bill-180-days

Mallya default singes top auditing companies

Some of world’s top auditing firms, including Price Waterhouse, Grant Thornton, Deloitte LLP and Walker Chandiok & Co, are under scrutiny with a slew of regulators seeking answers on their valuation, auditing and due diligence of UB Group companies over the last few years.

Deloitte LLP conducted the financial and tax due diligence for Diageo of United Spirits Ltd (USL) which led to the $2.1 billion acquisition of the company, but could not detect the problems in annual accounts. These accounts, in turn, were prepared by PW, which was the auditor for USL between 2010 and 2011, and later by Walker & Chandiok & Co.

The accounts were disputed by Diageo in April 2015 after it found a Rs 2,100 crore hole and sought Vijay Mallya’s ouster from the USL board. Questions have also been raised by lenders on what basis Grant Thornton valued the Kingfisher brand at Rs 4,100 crore. This is now being probed by the Serious Fraud Investigation office (SFIO).

When contacted, a Grant Thornton spokesperson said the firm fully stood by its brand valuation report on Kingfisher. “We believe it was appropriate in the context of when it was done and the purpose for which it was done,” the spokesperson said.

PW declined comment but an external spokesperson said the firm had not received any communication from either the Securities and Exchange Board of India or the Enforcement Directorate. “Deloitte does not comment on client confidential matters,” its spokesperson said.

Diageo had invested in USL after the British company was given express representations that all of the receivables from Mallya entities were recoverable in full. The fund diversion worth Rs 2,100 crore from USL was later raised when KPMG, the new auditor appointed by Diageo, discovered discrepancies when it was finalising USL’s 2014 accounts. All the three years’ accounts will now have to be re-stated, according to listing norms.

In the same year, the new USL management called in PW UK for a forensic audit of the previous three years (which included auditing by its own India unit) and passed on the reports to the regulators including the Sebi, the ministry of corporate affairs and the Institute of Chartered Accountants of India.

The ICAI, sources said, had asked both PW and Walker Chandiok to explain the discrepancy. An ED official said it was surprising that none of the auditors or valuers for Diageo raised flags over the accounts manipulation or the Rs 4,000 crore diversion by USL to the British Virgin Islands in 2007.

While the auditors of USL are in the dock for cooking accounts, another marquee auditing firm — Grant Thornton is under investigation by the SFIO for its Rs 4,100 crore brand valuation of Kingfisher Airlines. It was based on this brand valuation in 2011 that Mallya raised Rs 9,100 crore from government-owned banks by offering the brand as collateral. The lenders are now holding a dud Kingfisher brand, which is finding no takers.

Sources in the ICAI said it was a redux of the Satyam scam, when some of the world’s top auditors overvalued assets before the Maytas and Satyam merger, which led to the unravelling of the scam. In the Satyam case, the ICAI had debarred two auditors from Price Waterhouse who were found guilty of professional misconduct. S Gopalakrishnan and T Srinivas were struck off the ICAI’s rolls and fined Rs 5 lakh each. A Central Bureau of Investigation court later convicted them of fraud.

Source: http://www.business-standard.com/article/current-affairs/mallya-default-singes-top-auditing-companies-116031900495_1.html