CBDT extends deadline for filing ITR return and submitting audit report.

The government extended the date for filing income tax returns for companies by one month to November 30.

Income Tax Department has extended the deadline for ITR filing for certain categories of taxpayers. This has brought great relief to the taxpayers/institutions falling in these categories and they have also been saved from paying heavy penalties due to delay.

According to the Income Tax Department, till September 5, about 6.98 crore individual taxpayers have filed ITR.

The Income Tax Department has extended the deadline for filing income tax returns for charitable trusts, religious institutions and professional bodies by one month to November 30. The Income Tax Department said in a statement that the due date for filing income tax return in Form ITR-7 for the assessment year 2023-24, which is 31 October 2023, has been extended to 30 November 2023.

Also, the due date for submission of audit report for 2022-23 by any fund, trust, institution or any university or educational institution or medical institution in Form 10B/10BB has been extended by one month to 31 October 2023. Earlier the last date for submission of audit report was 30 September.

ITR-7 is filed by institutions involved in charitable and religious activities, research institutes, professional bodies, political parties and electoral trusts also file tax returns through ITR-7.

The Finance Ministry said in a statement on Monday, the deadline for filing income tax return in Form ITR-7 for the assessment year 2023-24 has been extended from October 31, 2023 to November 30, 2023.

In the current financial year, till mid-September, net direct tax collection has increased by 23.51% to Rs 8.65 lakh crore. The Finance Ministry said that there has been a huge increase in direct tax collection due to more advance tax payment by the companies. During this period, advance tax payment has increased by 21%.

According to the data, net tax collection has been 47.45% of the budget estimate of Rs 18.23 lakh crore for the current financial year. In the last financial year 2022-23, direct tax collection was Rs 16.61 lakh crore.

CBDT Circular: https://incometaxindia.gov.in/pages/communications/index.aspx

CBDT extends due date for filing Income Tax Return for AY 2022-23 to Nov 7

Providing a relaxation to the tax payer, the Central Board of Direct Taxes has extended the deadline for filing income tax return for the assessment year of 2022-23 till November 7, 2022. The decision was taken on Wednesday. It is to be noted that the last date to file ITR for FY23 was October 31.

The Central Board of Direct Taxes (CBDT) said in a notification that the ITR filing due date has been extended as it had last month extended the deadline for filing audit reports.

Providing a relaxation to the tax payer, the Central Board of Direct Taxes has extended the deadline for filing income tax return for the assessment year of 2022-23 till November 7, 2022. The decision was taken on Wednesday. It is to be noted that the last date to file ITR for FY23 was October 31.

CBDT extends the due date for furnishing Income Tax Return for AY 2022-23 to 7th November, 2022 for certain categories of assessees in consequence of extension of due dates for filing various reports of audit. Circular No. 20/2022 dated 26.10.2022 issued.

CBDT’s extension of due date for filing of Income Tax Return (ITR) for Assessment Year 2022-23 from 31/10/2022 to 07/11/2022 applies to the following assesses:

a) Companies
b) Persons subject to Tax Audit or Audit under any other law
c) Partner of Firm which is subject to Tax Audit
d) Other specified persons whose due date of filing the return of income is 31/10/2022.

Source: CBDT Circular

CBDT extends the timeline for filing Income Tax Returns and various Tax Audit Reports for Asst Year 2021-22

CBDT has decided to further extend the due dates for filing of Income Tax Returns and various reports of audit for the Assessment Year 2021-22.
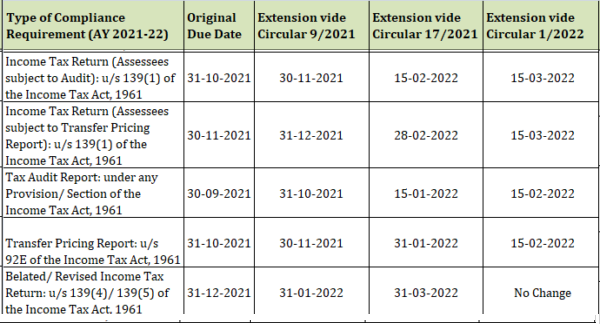
The Central Board of Direct Taxes, via Circular No. 01/2022 issued on 11th January 2021, has extended the timeline for filing of Income Tax Returns and various Reports of Audit for the Assessment Year 2021-22.
 
This has been done following the adverse impact of the 3rd wave of the COVID-19 pandemic and difficulties faced by taxpayers and professionals.
 

Announcement from CBDT earlier today on extension of timelines for filing of tax returns and certain audit reports to 15 March and 15 February is a major relief considering the challenges faced by both the taxpayers and their advisors due to newer variant of virus and the glitches in the online portal. Timing of the announcement in particular avoids anxiety for all concerned.

Here is the list of  various ITR deadline for AY 2021-22 that have been extended

  1. The due date of furnishing of Report of Audit under any provision of the Act for the Previous Year 2020-21, which was 30thSeptember 2021, in the case of assessees referred in clause (a) of Explanation 2 to sub-section (1) of section 139 of the Act, as extended to 31st October 2021 and 15th January 2022 by Circular No.9/2021 dated 20.05.2021 and Circular No.17/2021 dated 09.09.2021 respectively, is hereby further extended to 15th February, 2022;
  2. The due date of furnishing of Report of Audit under any provision of the Act for the Previous Year 2020-21, which was 31stOctober, 2021, in the case of assessees referred in clause (aa) of Explanation 2 to sub-section (1) of section 139 of the Act, is hereby extended to 15th February, 2022;
  3. The due date of furnishing of Report from an Accountant by persons entering into international transaction or specified domestic transaction under section 92E of the Act for the Previous Year 2020-21, which was 31stOctober 2021, as extended to 30th November 2021 and 31st January 2022 by Circular No.9/2021 dated 20.05.2021 and Circular No.17/2021 dated 09.09.2021 respectively, is hereby further extended to 15th February, 2022;
  4. The due date of furnishing of Return of Income for the Assessment Year 2021-22, which was 31stOctober 2021 under sub-section (1) of section 139 of the Act, as extended to 30th November 2021 and 15th February 2022 by Circular No.9/2021 dated 20.05.2021 and Circular No.17/2021 dated 09.09.2021 respectively, is hereby further extended to 15th March, 2022;
  5. The due date of furnishing of Return of Income for the Assessment Year 2021-22, which was 30thNovember 2021 under sub-section (1) of section 139 of the Act, as extended to 31st December 2021 and 28th February 2022 by Circular No.9/2021 dated 20.05.2021 and Circular No.17/2021 dated 09.09.2021 respectively, is hereby further extended to 15th March, 2022.

Clarification 1: It is clarified that this extension shall not apply to Explanation 1 to section 234A of the Act, in cases where the amount of tax on the total income as reduced by the amount as specified in clauses (i) to (vi) of sub-section (1) of that section exceeds one lakh rupees.

Clarification 2: For the purpose of Clarification 1, in case of an individual resident in India referred to in sub-section (2) of section 207 of the Act, the tax paid by him under section 140A of the Act within the due date (without extension under Circular No.9/2021, Circular No.17/2021 and this Circular) provided in that Act, shall be deemed to be the advance tax.

Source: CBDT Circular

Key changes in new ITR forms for AY 2021-22

Only the bare minimum changes necessitated due to amendments in the Income-tax Act, 1961 have been incorporated in the forms, CBDT said in the notification for the new ITR forms, in view of the ongoing crisis due to COVID-19 pandemic.

Keeping minimum change and with the view to minimise compliance burden, The Central Board of Direct Taxation (CBDT) has notified new income tax return forms — ITR-1 to ITR-7,  for the Assessment Year 2021-22, the ministry of finance said in a statement on April 1.  

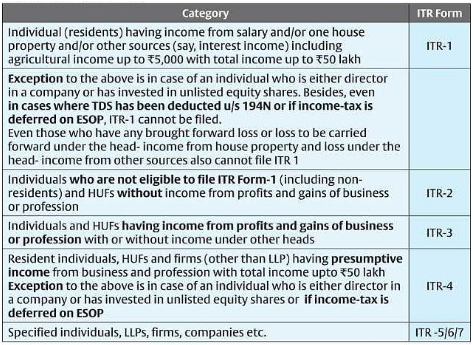
In this new ITR form for AY 2021-22, the taxpayers will now have dedicated space in each of the ITR forms — Sahaj (ITR-1), Form ITR-2, Form ITR-3, Form ITR-4 (Sugam), Form ITR-5, Form ITR-6, Form ITR-7 and Form ITR-V to describe their investments, CBDT said. 

ITR Form 1 (Sahaj) and ITR Form 4 (Sugam) are simpler Forms that cater to a large number of small and medium taxpayers. Sahaj can be filed by an individual having income up to Rs 50 lakh and who receives income from salary, one house property / other sources (interest etc). 

Similarly, Sugam can be filed by individuals, Hindu Undivided Families (HUFs) and firms (other than Limited Liability Partnerships (LLPs) having total income up to Rs 50 lakh and income from business and profession computed under the presumptive taxation provisions. 

Individuals and HUFs not having income from business or profession (and not eligible for filing Sahaj) can file ITR-2, while those having income from business or profession can file ITR Form 3. 

Persons other than individual, HUF and companies i.e. partnership firm, LLP etc can file ITR Form 5. Companies can file ITR Form 6. Trusts, political parties, charitable institutions etc claiming exempt income under the Act can file ITR-7. 

There is no change in the manner of filing of ITR forms as compared to last year, the CBDT said. 

Key points :

♦ ITR-1 cannot be filed in case tax has been deducted u/s 194N

As per, Section 194N – TDS 194N is required to be deducted if amount of cash withdrawn exceeds –

  • Exceeds Rs 20 lakhs in case of non-filers of return
  • Rs 1 crore in all other cases

from banking company or co-operative bank or post-office from one or more accounts maintained by taxpayer.

If tax has been deducted u/s 194N, a person can file –

  • ITR 2
  • ITR 3
  • ITR 4

♦ TDS deducted u/s 194N cannot be carried forward to subsequent years.

It means Credit for tax deducted u/s 194N can be taken in previous year relevant to Assessment year in which tax has been deducted.

♦ Option has been given to Individual or HUF as per Section 115BAC.

From A.Y 2021-22 option is available to Individual & HUF whether to opt New Scheme or not. This option for lower tax regime, by foregoing certain exemptions and deductions, is given to Assessees to select new scheme-Section 115BAC and are required to file Form-10IE before filing the return u/s 139(1).

♦ Change in Schedule 112A-LTCG from sale of equity share or unit of equity oriented fund on which STT is paid.

Sale price per share/unit now added in Schedule 112A, which was not earlier provided.

♦ Dividend also taxable from A.Y 2021-22- As we know Dividend Income taxable from A.Y 2021-22 in hands of Assessee from A.Y 2021-22 so we are required to give quarterly break-up of Dividend received in order to get relief from interest levied u/s 234C.

♦ Changes in Section 44AB- The threshold limit to get books of account audited increased from Rs 1 crore to 10 crores, if the following conditions are satisfied-

  1. His aggregate of all receipts in cash during the previous year does not exceeds 5 % of such receipts.
  2. His aggregate of all payments in cash during the previous year does not exceeds 5 % of such payments

Due date for filing income tax returns further extended

The reduced TDS and TCS rate will be for specific payments such as payment for a contract, professional fees, interest, rent etc.
Income tax return filing due date: ITR FOR COMPANIES:- Deadline for filing income tax return for 2019-20 by companies extended by 15 days to Feb 15, 2021and for individuals by 10 days to Jan 10, 2021

In a major development, Income Tax department has extended the deadline for ITR filings. The deadline for filing income tax return for 2019-20 by companies extended by 15 days to Feb 15, 2021. Further, the deadline for filing income tax returns by individuals extended by 10 days to January 10, 2021. Also, the last date to declare under Vivad se Vishwas Scheme extended to 31st January 2021, it was expiring on December 31st.

Deadline for filing income tax return for 2019-20 by companies extended by 15 days to Feb 15, 2021 & deadline for filing income tax returns by individuals extended by 10 days to Jan 10, 2021

Taking to Twitter, Income Tax Department said, “In view of the continued challenges faced by taxpayers in meeting statutory compliances due to outbreak of COVID-19, the Govt further extends the dates for various compliances. Press release on extension of time limits issued today:”

Earlier, direct tax professionals had sought extension for tax audit report, income tax returns for audit cases and time limit for AGMs in the wake of the ongoing pandemic scenario. The Direct Taxes Professionals Association (DTPA) had urged Finance Minister Nirmala Sitharaman for extension of date of furnishing of tax audit report under section 44AB to February 28 and the due date of filing of income tax returns of assessment year 2020-21 in audit cases to March, 31, 2021.

Meanwhile, the IT department on Wednesday said more than 4.54 crore tax returns for 2019-20 fiscal have been filed till December 29. In the comparable period last year, 4.77 crore income tax returns were filed. At the close of deadline for filing ITRs without payment of late fees for fiscal 2018-19 (assessment year (AY) 2019-20), over 5.65 crore returns were filed by taxpayers.

In a tweet on Wednesday, the Income Tax department nudged taxpayers to file their ITRs by the due date. “More than 4.54 crore Income Tax Returns for AY 2020-21 have already been filed till 29th of December, 2020,” the I-T department said.

The data released by the tax department showed that over 2.52 crore ITR-1 have been filed till December 29, 2020, lower than the 2.77 crore filed till August 29, 2019.

Over 1 crore ITR-4 have been filed till December 29 as compared to 99.50 lakh filed till August 29, 2019. An analysis of the data showed that individuals filing tax return for fiscal 2019-20 have slowed so far in the current year, while filings by businesses and trusts have increased.

Returns in ITR-1 Sahaj can be filed by an ordinarily resident individual whose total income does not exceed Rs 50 lakh, while form ITR-4 Sugam is meant for resident individuals, Hindu Undivided Families (HUFs) and firms (other than LLP) having a total income of up to Rs 50 lakh and having presumptive income from business and profession.

Over 33.93 lakh ITR-2 (filed by people having income from residential property) were filed till December 29.

During last year, the due date for filing ITR by individuals who do not need to get their accounts audited was August 31. However, the date has been extended till December 31 this year on account of the COVID-19 pandemic.

ITR-5 (filed by LLP and Association of Persons) filings till December 29, 2020 jumped to 7.09 lakh from 4.14 lakh filed till August 29, 2019. ITR-6 (filed by businesses) filings skyrocketed to over 3.46 lakh till December 29, 2020 as compared to 21,962 filed till August 29, 2019.

ITR-7 (filed by persons having income derived from property held under trust) filings also jumped to over 1.04 lakh till December 29, 2020 as compared to 41,963 till August 29 last year.

Earlier, for the FY 2019-20, the government had also extended the date for making various investment/ payment for claiming deduction under Chapter-VIA-B of the IT Act which includes section 80C (LIC, PPF, NSC etc.), 80D (Mediclaim), 80G (Donations) to 31st July, 2020. Now the investment/ payment can be made upto 31st July, 2020 for claiming the deduction under these sections for FY 2019-20. In the income tax forms, Schedule DI enables taxpayers to claim exemptions on investments they made during the extended period, until June 30, 2020.

Under normal circumstances, the last date to take income tax benefits is till March 31 of the financial year. The government had also extended the last date for the issuance of Form 16 by employers to their employees. In fact, the extension has been given for all TDS ( tax deducted at source) certificates, including Form 16. The CBDT has already notified the Income Tax Return Forms for the assessment year (AY) 2020-21 and are available for e-Filing by downloading either excel or Java utility.

Source: Press Release from Ministry of Finance