Institute of Chartered Accountants of India enable generation of UDIN (Unique Document Identification Number) for certification by its members
A provision for generating UDIN in bulk for Certificates has been incorporated in UDIN Portal.
Using this facility now the members will be able to generate UDIN in bulk (uptil 300 UDINs) for various types of Certificates in one go. It can be done through uploading of excel file.
Process for bulk UDIN
Step-wise complete process for generating bulk UDINs is as under:
i) After login, from the Menu bar, click on Bulk UDIN for Certificates. Minimum 3 certificates and Maximum 300 certificates can be generated using this procedure.
ii) Download template file from Download Template button and open in Excel. Please note that the .xlsx file can be opened in Excel 2007 and later versions.
iii) Select Certificate type from drop down.
iv) Input dates in the format as per your system/computer (generally it is in mm/dd/yyyy or as 10 June 2020). Excel will format dates automatically in required format i.e dd-mm-yyyy. Do not use copy paste in this cell.
v) Fill in all the parameters and values.
vi) Save the file.
vii) Click on the upload file on the Certificate Form on UDIN Portal.
viii) Select the file just saved now.
ix) Portal will populate the data in the Form. Verify the data so populated.
x) If correct, Send and Verify OTP and Submit.
xi) Alternatively, the option of filling the details of Type of Certificates, Dates and key fields etc. is available on the form itself.
The amendment, aims at controlling tax evasion, and bring glassiness Form 26AS, which is now being replaced with a new Annual Information Statement (AIS) i.e Form 26AIS.
The Central Board of Direct Taxes (CBDT) on Thursday notified Income Tax (11th Amendment) Rules, 2020.
In exercise of the powers conferred by section 285BB read with section 295 of the Income-tax Act, 1961 (43 of 1961), the Central Board of Direct Taxes hereby makes the following rules further to amend the Income-tax Rules, 1962, namely:-
In Income Tax Rules, 1962 Rule 114-I relating to Annual Information shall be inserted which is, “the Principal Director General of Income Tax (System) or the Director-General of Income Tax (Systems) or any person authorized by him shall, under Section 285BB of the Income-Tax Act, 1961, upload in the registered account of the assessee an annual information statement in Form No. 26AS containing the information specified in the column (2) of the table below, which is in his possession within three months from the end of the month in which the information is received by him.”
The notification consists of a table that contains the nature of information which includes information relating to a tax deduction or collected at source; specified financial transaction; payment of taxes; demand and refund; pending proceedings; and completed proceedings:
Sl. No.
Nature of information
(i)
Information relating to tax deducted or collected at source
(ii)
Information relating to specified financial transaction
(iii)
Information relating to payment of taxes
(iv)
Information relating to demand and refund
(v)
Information relating to pending proceedings
(vi)
Information relating to completed proceedings
(vii)
Any other information in relation to sub-rule (2) of rule 114-I
The amendment, aims at controlling tax evasion, and bring glassiness Form 26AS, which is now being replaced with a new Annual Information Statement (AIS) i.e Form 26AIS.
Further sub-clause (2) of Rule 114-I says, “the Board may also authorize the Principal Director General of Income-tax (System) or the Director-General of Income Tax (Systems) or any person authorized by him to upload the information received from any officer, authority or body performing any function under any law or the information received under an agreement referred to in Section 90 or Section 90A of the Income Tax Act, 1961 or the information received from any other person to the extent as it may deem fit in the interest of the revenue in the annual information statement referred to in sub-clause (1).”
Lastly, sub-clause (3) of Rule 114-I says, “the Principal Director General of Income-tax (System) or the Director-General of Income Tax (Systems) shall specify the procedures, formats, and standards for the purpose of uploading of annual information statement referred to in sub-clause (1).”
NCLAT quashes NCLT order to make MCA party in all insolvency cases as this will be not only excessive but perhaps counterproductive
The National Company Law Appellate Tribunal (NCLAT) quashed an order of the National Company Law Appellate Tribunal (NCLT) directing that the Ministry of Corporate Affairs (MCA) be made a party to every case under the Insolvency and Bankruptcy Code (IBC) on Monday.
According to the appellate tribunal, the NCLT’s order, was beyond the power of the tribunal as it was tantamount to the imposition of a new rule in a compelling fashion
The impugned order making it applicable throughout the country to all the benches of NCLT is untenable and it suffers from material irregularity and patent illegality in the eye of law, said the judgment of the three-judge bench headed by Justice Venugopal M.
“The NCLAT ruled that the MCA need not be a party to all Section 7,9 and 10 applications, although they may be impleaded in certain cases based on exercise of judicial principles and following principles of natural justice. Although the MCA has been central in the implementation of the IBC, their being a party to every single IBC fillings is not only excessive but perhaps counterproductive,” said Richa Roy, partner at Cyril Amarchand Mangaldas.
In November 2019, the NCLT had directed the MCA, through its secretary, be party to all cases under IBC on the grounds that authentic records would be made available by officers of the MCA.
The Centre challenged the order arguing that such rule making was the exclusive domain of the government. It further said that authentic records could be furnished by the Registrar of Companies and certified copies could be made available for a fee.
The NCLAT order added that such “wholesale, blanket and omnibus directions” cannot be issued in a single stroke” and impleadment of the MCA can only be determined on a case-to-case basis.
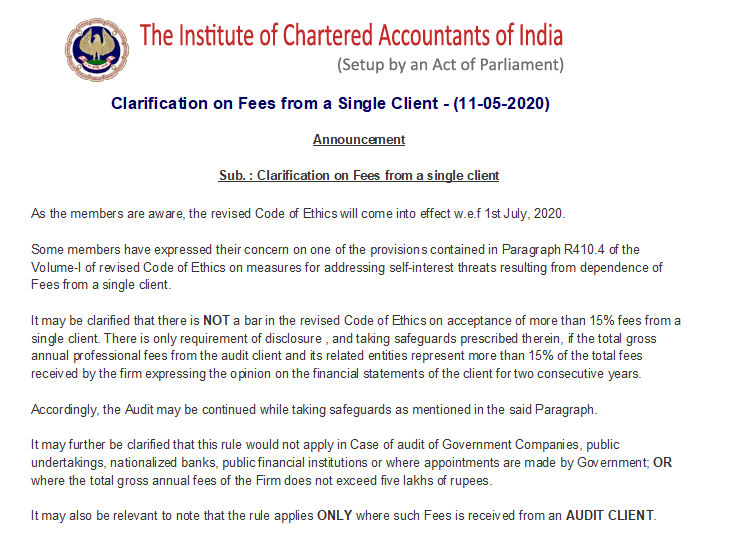
The Institute of Chartered Accountants of India ( ICAI ) has clarified that there is NOT a bar in the revised Code of Ethics on acceptance of more than 15% fees from a single client.
The ICAI has said that some members have expressed their concern on one of the provisions contained in Paragraph R410.4 of the Volume-I of revised Code of Ethics on measures for addressing self-interest threats resulting from the dependence of Fees from a single client.
The ICAI clarified that there is NOT a bar in the revised Code of Ethics on acceptance of more than 15% fees from a single client. There is the only requirement of disclosure, and taking safeguards prescribed therein, if the total gross annual professional fees from the audit client and its related entities represent more than 15% of the total fees received by the firm expressing the opinion on the financial statements of the client for two consecutive years.
Accordingly, the Audit may be continued while taking safeguards as mentioned in the said Paragraph. The ICAI further clarified that this rule would not apply in case of audit of Government Companies, public undertakings, nationalized banks, public financial institutions, or where appointments are made by Government; OR where the total gross annual fees of the Firm does not exceed five lakhs of rupees.
It may also be relevant to note that the rule applies ONLY where such Fees are received from an AUDIT CLIENT.
As per existing norms, if a payment default exceeds 90 days then the lender concerned has to refer the account for resolution under IBC or any other mechanism permitted by the Reserve Bank of India (RBI). The lender does not have the option to restructure the loan.
The government has decided to suspend insolvency and bankruptcy proceedings for at least six months owing to challenges businesses are facing due to the Covid-19 pandemic.
A new Section is likely to be added to the Insolvency and Bankruptcy Code (IBC).
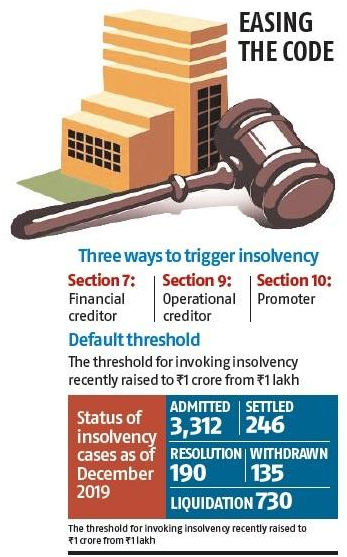
It will suspend Sections 7, 9, and 10, which are used to trigger insolvency proceedings for six months or a period not exceeding one year from the date they commence, the official said.
A new Section is likely to be added to the Insolvency and Bankruptcy Code (IBC).
It will suspend Sections 7, 9, and 10, which are used to trigger insolvency proceedings for six months or a period not exceeding one year from the date they commence, the official said.
Section 7 of the Code enables
financial creditors to start insolvency proceedings against a company while
Section 9 gives operational creditors these powers.
Under Section 10, the promoter of the company can trigger insolvency proceedings against his or her own concern.
All the three Sections will cease to be effective for six months or further.
The provision is likely to require a change in the Act, according to experts.
“This is a positive step for companies.
But for companies, which were otherwise already in stress and could have found resolution under the IBC, their resolution may also be delayed due to this suspension,” said Anshul Jain, partner, PwC India.
Jain also said it needed to be seen if this move would have a positive impact on privately negotiated transactions on mergers and acquisitions.
In March, Union Finance Minister Nirmala Sitharaman had indicated the government would consider suspending the IBC for a few months if the Covid situation persisted and caused stress to businesses.
Already, the default threshold for stressed companies facing insolvency has been increased from Rs 1 lakh to Rs 1 crore.
In March, Union Finance Minister Nirmala Sitharaman had indicated the government would consider suspending the IBC for a few months if the Covid situation persisted and caused stress to businesses. Already, the default threshold for stressed companies facing insolvency has been increased from Rs 1 lakh to Rs 1 crore.
RBI is also likely to question the auditor on whether the SBI proposal would have any ‘material impact’ on the existing accounts of Yes Bank
The Reserve Bank of India will check if troubled lender Yes Bank’s auditor had raised any alarm in the past year. The apex bank has been in touch with the auditor and will look into whether they had specifically issued any warning in the past 12 months.
According to a report in The Economic Times, RBI has been in touch with auditor BSR & Co and wants to know if it had raised any red flag relating to the health of Yes Bank or any other issue. The auditor is part of KPMG India. The central bank is also likely to question the auditor on whether the SBI proposal would have any ‘material impact’ on the existing accounts of Yes Bank.
On Friday, the RBI announced a reconstruction scheme for the bank. It said that SBI that has expressed interest to invest in the troubled bank would do so to the extent of holding 49 per cent shareholding. The apex bank said that SBI’s investment in Yes Bank would not impact the employees and their current terms of employment.
BSR and Co was appointed as Yes Bank’s auditor after RBI banned SR Batliboi & Co for a year. The RBI had stated that the firm that was part of EY was banned due to “lapses identified in a statutory audit assignment carried out by the firm”.
RBI put restrictions on Yes Bank on March 6, allowing its customers to withdraw only Rs 50,000 for a month. The apex bank relaxed the guidelines subsequently. On Tuesday, the bank permitted its credit card customers to pay their credit card dues and loan obligations from other bank accounts. It allowed NEFT payments to clear loan EMIs and make credit card payments. The bank had, before that, allowed customers to withdraw money from ATMs of other banks.
The government had issued new norms for auditors, seeking more disclosures in reports, a move which comes after a series of corporate scams and frauds surfaced over the past few years.
CARO 2020 – Companies (Auditor’s Report) Order, 2020
MCA in place of existing the Companies (Auditor’s Report) Order, 2016, has notified CARO 2020 after consultation with the National Financial Reporting Authority constituted under section 132 of the Companies Act, 2013.
Auditor’s report to contain matters specified in paragraphs 3 and 4. – Every report made by the auditor under section 143 of the Companies Act on the accounts of every company audited by him, to which this Order applies, for the financial years commencing on or after the 1st April, 2019, shall in addition, contain the matters specified in paragraphs 3 and 4, of the CARO 2020.
Provided this Order shall not apply to the auditor’s report on consolidated financial statements except clause (xxi) of paragraph 3.
It shall come into force on the date of its publication in the Official Gazette.
CARO 2020 – Key changes/highlights
Matters to be included in auditor’s report, in CARO 2020 – the reporting clauses are more extensive and detailed than were in CARO2016
Unlike CARO 2016, which required reporting on all fixed assets, new reporting requirements pays attention to Property, Plant, Equipment and intangible assets.
Reporting on revaluation of Property, Plant and Equipments by company
Reporting of proceedings under the Benami Transactions (Prohibition) Act, 1988.
Reporting of compliances if company was sanctioned working capital limits in excess of Rs.5 crores or more from banks or financial institutions.
– whether the quarterly returns or statements filed by the company with such banks or financial institutions are in agreement with the books of account of the Company, if not, to give details;
Reporting of investments in or in providing of any guarantee or security or granting any loans or advances to companies, firms, Limited Liability Partnerships or any other parties.
Reporting of compliances with RBI directives and the provisions the Companies Act with respect to deemed deposits.
Reporting with respect to transactions not recorded in the books of account surrendered or disclosed as income in the income tax proceedings.
Comprehensive reporting requirement for default in the repayment of loans / other borrowings or in the payment of interest
– whether the company is a declared wilful defaulter by any bank or financial institution or other lender;
– whether term loans were applied for the purpose for which the loans were obtained; if not, the amount of loan so diverted and the purpose for which it is used may be reported;
– whether funds raised on short term basis have been utilised for long term purposes, if yes, the nature and amount to be indicated
Reporting on treatment by auditor of whistle-blower complaints received during the year by the company
Reporting on internal audit system
– whether the company has an internal audit system commensurate with the size and nature of its business;
– whether the reports of the Internal Auditors for the period under audit were considered by the statutory auditor;
Reporting on cash losses
Reporting on resignation of the statutory auditors
Reporting on uncertainty of company capable of meeting its liabilities
Reporting transfer of unspent CSR amount to Fund specified in Schedule VII
Reporting on qualifications or adverse remarks by the auditors in the CARO reports of companies included in the consolidated financial statements
It is expected that CARO, 2020 will improve the overall quality of reporting by the auditors and thereby lead to “greater transparency and faith in the financial affairs of the companies.”