India, UK to cooperate in infrastructure financing, address tax evasion

The possibility of their investing, either directly in projects or through the National Investment and Infrastructure Fund (NIIF) that we have created, were both discussed,” he told reporters at the Indian High Commission in London.

Amid fears of the global economy edging close to recession, India and UK have agreed to open up trade and markets to support growth, carry out structural reforms and address issues related to cross-border tax evasion.

After talks between India’s Finance Minister Arun Jaitley and UK Chancellor of the Exchequer George Osborne, the two nation’s agreed to boost economic ties particularly in areas of infrastructure and financial services and renewed pledge for autonomical exchange of tax information from 2017.

“From the Indian point of view, we were extremely interested in having the British investors look at infrastructure investments in India for which various possibilities were discussed,” Jaitley said after the talks.

India, he said, is “extremely keen that large British companies, particularly involved in infrastructure financing, start investing in Indian infrastructure”.

The two nations will work together for developing an India-UK partnership fund under the umbrella of National Investment and Infrastructure Fund (NIIF) recently created in India.

“This fund will seek to increase flows of private sector capital and expertise alongside multilateral support into Indian infrastructure,” a joint statement issued after talks said.

The world’s fifth largest economy will work on development of smart cities in India. New Delhi is also looking at London for issuance of rupee-denominated bonds to get UK investors to fund its infrastructure projects.

“The possibility of their investing, either directly in projects or through the National Investment and Infrastructure Fund (NIIF) that we have created, were both discussed,” Jaitely told reporters at the Indian High Commission here.

With the IMF warning of global economy being close to recession with 3.4 per cent growth this year, the two sides said they “remain concerned that global growth is falling short of expectations and that the risks to the global outlook have increased”.

“In this regard we stand ready to take the necessary steps to open up trade and markets to support growth and jobs, and agree on the importance of structural reforms and pursuing credible fiscal policies,” the joint statement said.
The joint statement talked about advancement of cooperation in a range of sectors including infrastructure financing, addressing issues of cross-border tax evasion/ avoidance besides opening up of the Indian legal sector to foreign lawyers.

“The UK and India share a common commitment to address cross-border tax evasion and avoidance. Both sides have committed to the Common Reporting Standards (CRS) on Automatic Exchange of Tax Information and will begin exchange in 2017,” the statement said.

“We call on other countries to meet the commitments they have made and to implement the new standard on time,” it said.

During the talks, which included senior representatives from Finance Ministries, Central Banks and key regulators of both countries, the two leaders discussed ways to strengthen the Indo-UK existing economic partnership in order to further boost trade and investment, and to build on the success of Prime Minister, Narendra Modi’s recent summit with his British counterpart David Cameron in the UK.

“Given the fact that even in a somewhat difficult global scenario, India is managing a reasonable growth rate, this is one of the better options that investors have and that kind of a sentiment gets really echoed in the meetings with the investors that we had. Of course, the investors are also keenly watching which way our reform process in India goes,” Jaitley said.
The two nations agreed to work together on building commercial and regualtor-to-regulator links that can underpin further fintech growth in both countries.

“The UK and India agreed to renew the existing mandate of the India-UK Financial Partnership, and building on the re-establishment of the CEO Forum,” the statement said, adding that potential areas of interest for the India-UK Financial Partnership could be reinsurance, international use of the rupee, role of financial technology, financial inclusion, investor protection and green finance.

“The global economy is facing serious challenges and therefore the estimates of global growth also have been repeatedly lowered. Compared to how various countries across the world have been doing, India’s growth rate despite these challenges is probably the highest in the world among major economies,” Jaitley said, in reference to his meetings with investors at Goldman Sachs and London Stock Exchange.

As a follow up on Prime Minister Modi’s announcement during his UK visit last November on the listing of Rupee bonds in London, the minister said, “the UK is very keen for these to be listed in London and broadly the economic and financial dialogue was carried further”.

During the dialogue, the two sides recognised that as the leading financial centre in the world and in the view of successful issuance of Masala bonds issued by the International Finance Cooperation last year, London will be an attractive location for issuance of rupee-denominated bonds.

“The bonds, which were first announced during the visit of Prime Minister Modi to the UK in November, illustrate the crucial role that the UK’s capital markets can play in an enhanced economic relations relationship with India, with UK investors providing financing for the transformation of India’s infrastructure and continued rapid economic growth,” the statement said.

India and the UK also agreed that the development of deeper markets in rupee-linked products, and the increasingly sophisticated relationship between the Indian and UK financial sectors, are important underlying factors in fostering an enduring economic and financial partnership.

Both sides agreed to continue working closely on the development of smart cities in India.

“We will continue to build on and further embed the existing Technical Assistance Partnerships that were announced during Prime Minister Modi’s recent visit to the UK, and to continue working together on research collaboration and other measures to support India’s 100 Smart Cities programme,” the statement said.

While noting the strength of the economic outlook for both countries, the two sides expressed concern that global growth is falling short of expectations and that the risks to the global outlook have increased.

“In this regard we stand ready to take the necessary steps to open up trade and markets to support growth and jobs, and agree on the importance of structural reforms and pursuing credible fiscal policies in order to raise living standards,” it said.

India and the UK also agreed to work together with the aim of developing an Indo-UK partnership fund under the umbrella of the NIIF. The fund will seek to increase flows of private sector capital and expertise alongside multilateral support into Indian infrastructure.

The working group to be established will report back within the course of 2016 on a proposed fund strategy and delivery approach, the statement said.

“As part of this, India and the UK also both recognise the importance of identifying the sector or sectors where there is greatest potential for developing sustainable project pipelines, and of developing a supportive institutional environment for investment and delivery,” it said.

Source:http://economictimes.indiatimes.com/articleshow/50650198.cms
 

Income Tax Department processes 32.7 million returns during April-December, 2015

Income Tax Department has processed 3.27 crore returns and has issued refunds in 1.81 crore cases during April-December period of this fiscal.


CBDTCentralized Processing Centre (CPC), Bengaluru has processed 3.27 crore returns as of December 31, registering a growth of 18 per cent over 2.65 crore returns processed during the corresponding period of the previous fiscal.

“During the current financial year, the CPC has issued refunds in 1.81 crore cases out of which in 1.32 crore cases, that is 73 per cent, the refunds were issued within 30 days of filing by the taxpayers,” an official statement said.

The number of Tax payers in the income bracket of Rs 1 crore and below was 2.39 crore as of October 31 last year. For 2014-15 it was 3.66 crore; 3.73 crore in 2013-14 and 3.26 crore in 2012-13.

The Department is committed to continuously improving the quality of tax payer services and enhance taxpayer satisfaction, it added.

Meanwhile, on January 11, CPC was awarded “ISO 9001:2008 Standard for Quality Management System” Certificate by British Standards Institution (BSI).

The Certificate encompasses all business services and business enabler services of CPC, it said.

ISO 9001 is an international standard that specifies requirements for quality management system (QMS) addressing the principles and processes that surround the design, development and delivery of services, it said.

Organisations use this standard to demonstrate their ability to consistently provide services that meet customer and regulatory requirements, it added.

Source: http://economictimes.indiatimes.com/articleshow/50623770.cms?utm_source=contentofinterest&utm_medium=text&utm_campaign=cppst

Startups enjoy 3 years tax holiday over a five year window

If a startup claims benefit in first year & does not make profit in next two years, it can still enjoy tax exemption on profit in fourth and fifth year

The three-year tax holiday proposed for startups in India will be available over a five-year window, ensuring that innovators won’t lose the benefit even if they make a profit later, the government said.

Those seeking the income tax exemption, announced in the Startup Action Plan on Saturday, will need to get approval by March 2019, in line with the government’s policy to weed out exemptions and bring down the corporate tax rate to 25%. Startups approved until March 31, 2019, will enjoy the benefit for up to five years. The government has proposed that a high-level, inter-ministerial committee should vet startup proposals to validate the innovative nature of the business for granting tax-related benefits. The details of the tax benefits will be announced in the budget.

“The benefit will be available for three years over a five-year period, “a senior government official told ET. If a startup claims the benefit in the first year and does not have a profit in the next two years, it will not lose out on the exemption. If profits are made in the fourth and fifth year, they will still be eligible for the tax break.

“All startups incorporated in India not prior to five years as per the definition of startup and starting the operations before 2019 can get this benefit for three years,“ said Amitabh Kant, secretary in the Department of Industrial Policy and Promotion, which piloted the startup initiative.

With the deadline for seeking exemption set for March 2019, the scheme will effectively run till March 2024, a period of eight years from now.

“This fiscal exemption shall facilitate growth of business and meet the working capital requirements during the initial years of operations, “according to the action plan document.

The policy imposes only one condition on startups claiming the benefit, apart from seeking approval from the appropriate body and meeting eligibility criteria: it should not distribute dividend while getting the tax exemption.

Tax-friendly Regime Need of the Hour for Startup Investors

The devil is in the details. The tax incentive package for startups will be clear in the Budget. But open-ended tax breaks won’t be possible as the government has already signalled a phasing out of exemptions to lower the corporate tax rate. Investments in unicorns would typically be long-term. So, it makes eminent sense to spare investors from paying capital gains tax when they sell their unlisted shares in startups after holding them for over a year. A tax-friendly regime will encourage many of them to relocate to India from, say, Singapore. The government, as promised, should end its Inspector Raj to boost the startup ecosystem.

Source: http://epaperbeta.timesofindia.com/Article.aspx?eid=31816&articlexml=Startups-May-Get-5-Year-Window-to-Avail-18012016015013


CBEC for voluntary code for e-retailers to curb illicit trade

Expressing concern over sale of fake products on e-commerce platform, CEBC today said it is considering putting in place a voluntary code of practice for e-retailers to curb illicit trade.
“New challenges are emerging for customs. E-commerce is one such major area of vulnerability. E-commerce in India provides an unparalleled platform for sellers of both genuine and counterfeit products. So, we are looking at possibility of introducing voluntary code of practice for e-retailers,” Central Board of Excise and Customs (CBEC) Chairman Najib Shah said at an event organised by Ficci here.
The easy concealment of identity encourages sale of counterfeit products on the e-commerce platform. At times, intermediaries are denied judicial protection in the absence of strong law, he said.
To address the challenges posed by e-commerce trade, Shah said CBEC will at a seminar next month discuss with stakeholders the possibility of introducing ‘voluntary code of practice’ for e-retailers to fight illicit trade.
Stating that any smuggling and counterfeit activities is a matter of great concern to the government, the CBEC chief said, “This game is done at the cost of the honest tax payers. Though it results in financial gain to the person infringing the law but it is a financial loss to the exchequer.”
Shah also emphasised on the intellectual property rights and called for structured interaction between the customs and stakeholders on this issue.
The latest report, ‘Emerging challenges to legitimate business in the border-less world’, prepared by tax and advisory firm Grant Thornton and industry body Ficci, also noted that online marketplaces have become a “preferred hub for illicit operations” owing to their wider reach and ease of access.
Prominent players including Alibaba, Amazon and SnapDeal, etc have been at the receiving end of imitation products offered by third parties not connected to the brand owner, the report said and suggested e-retailers to put in place an holistic anti-counterfeit policy.
That apart, the report also pitched for a separate e- commerce law in the country to check illicit trade.
“In the absence of a specific e-commerce legislature in India and other laws including the Information Technology Act, Indian Companies Act, Companies Act 2013, Intellectual property, laws in copyrights and trademark etc, there are certain grey areas. Thus, there is a need for a separate e- commerce law in the country,” the report said.
The e-commerce regulations have a long way to go in India and inching closely towards this journey is the recent proposal of the Consumer Affairs Ministry to bring e-commerce businesses under the purview of multiple government agencies, the report added.
The report was released here by Food and Consumer Affairs Minister Ram Vilas Paswan. (PTI)

Source: http://www.dailyexcelsior.com/cbec-for-voluntary-code-for-e-retailers-to-curb-illicit-trade/

E-filing: Over 50 lakh ITRs e-verified by Income Tax department

The Income Tax department’s ambitious OTP-based ITR filing system for taxpayers has crossed the 50 lakh e-verification mark, while more than 39 lakh Aadhaar numbers have been successfully linked with the PAN database after the scheme was launched over six months back.

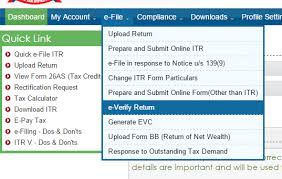
The new e-filing system, operationalised last year, allows online verification of a person’s Income Tax Returns (ITR) by using either the Aadhaar number, internet banking, ATM or email, thereby ending the practice of sending paper acknowledgment to the Centralised Processing Centre (CPC) of the IT department located in Bengaluru.

“The e-verification of ITRs recently crossed the 50 lakh figure which is a testimony to more and more people and entities opting for electronic filing of their IT returns. While sky is the limit here, getting these numbers just when the new year has begun will enable the government to usher in more and more facilities for e-filing of ITRs in the new financial year begining April 1,” a senior official said.

The official, quoting latest data of the week ending today, said a total of 50,10,282 ITRs have been e-verified, while Aadhaar linkages with the Permanent Account Number (PAN) has been achieved in 39,66,149 cases during the same period.

The online ITR filing portal of the department is available at http://incometaxindiaefiling.gov.in.

According to the rules notified in this regard by the Central Board of Direct Taxes (CBDT) in July last year, any taxpayer whose income is Rs 5 lakh or below per annum and has no refund claims can straightaway generate the ‘Electronic Verification Code’ (EVC) for e-filing and validating their ITR through their registered mobile number and e-mail ID with the department. They get a system generated One-Time Password (OTP) to validate their ITRs.

However, this simplified option will be subject to certain “restrictions” which have been prepared by the taxman based on the concerned taxpayer’s “risk criteria and profile” on a case-to-case basis.

These new measures would completely eliminate the need of sending the paper acknowledgment called ITR-V through post to the Bengaluru based CPC.

In other options, those taxpayers who have activated internet banking facility can also do the e-verification.

Once logged in to the banking portal, the taxpayer will be sent EVC on his mobile number provided to the official e-filing portal of the department which they will put in their ITR for final submission.

The Aadhaar database is also being used by the taxman to verify taxpayers’ credentials.

The department initiated these new technology-based measures in order to fully automate the e-filing system and also to end taxpayers’ grievances with regard to their ITR-V not reaching by post which led to their returns getting rejected.

Source: http://www.financialexpress.com/article/economy/e-filing-over-50-lakh-itrs-e-verified-by-income-tax-dept/191519/

All communication of tax scrutiny to be via e-mail from FY17

The I-T department in the recent times has taken a host of initiatives to reduce human interface between tax official and assessees and make the tax system non-adversarial


The income tax department is planning to carry out all communication related to the scrutiny of returns through e-mails from the next fiscal to reduce harassment of tax payers by eliminating interface between assessees and taxmen.


The I-T department, on a pilot basis, has already started scrutiny of returns through e-mails in 5 metropolitan cities- Delhi, Mumbai, Bengaluru, Ahmedabad and Chennai regions.


“We are working on a software so that all scrutiny communications can be stored in a specified server. Once it is ready, we will shift to e-environment as far as scrutiny, and all communications in this regard are concerned,” a top revenue department official told PTI.


The official further said that moving to e-scrutiny would help in combating corruption, as it would reduce the interface between assessee and tax officials. Also, he added that all the communication records with regard to scrutiny would be stored in one place and can be verified whenever needed.


“There has been an encouraging response to the pilot project undertaken by the tax department. From next fiscal we want to make all scrutiny communication through emails,” the official said.


The Central Board of Direct Taxes (CBDT) has already asked the officials to initiate the concept of using emails for corresponding with taxpayers.


The I-T department in the recent times has taken a host of initiatives to reduce human interface between tax official and assessees and make the tax system non-adversarial. These include directing field offices to raise only specific queries in income tax assessment cases picked up for scrutiny. It also directed expeditious completion of those scrutiny cases where income concealed is up to Rs.5 lakh.


The department had also stipulated that appeals before I-T commissioner should be filed in electronic format by those assessees who e-file their returns.


Source: http://www.livemint.com/Politics/q7dtcfDoj7LMFeJkTG1VRK/All-communication-of-tax-scrutiny-to-be-via-email-from-FY17.html

ITR-V verification deadline extended to 31st January

If you missed your 120 days ITR-V verification deadline, there is good news. The income tax department has extended the verification deadline till 31st January.

If you missed your 120 days ITR-V verification deadline, there is good news. The income tax department has extended the verification deadline till 31st January.

Although it has not been officially notified yet, taxpayers have been receiving this information via email from the I-T department. However, you won’t be able to e-verify. Like old times, will have to physically mail the signed ITR V to CPC Bangalore.

“The electronic verification option gets switched-off automatically after 120 days of the taxpayer filing the return. However, the extended deadline to physically submit the ITR-V is open for all,” says Archit Gupta, founder and CEO, Cleartax.in. The 120 days countdown begins from the date the taxpayer submits their income tax returns forms.

The tax department had extended the filing deadline to September 7 this years. So, people who had filed on the last date still have a window of one day to e-verify. Post that you too will have to mail the ITR-V. The last date to do so will still remain 31st January.

Many individuals who, who had e-verified their return using Aadhar or Net banking, are receiving reminder letters from the CPC at Bangalore to physically send their ITR-V acknowledgement forms on or before the 31st of January, 2015.

“Those trying to e-verify their return once again with reference to the above are getting the message “No returns pending for e-verification” when they try to do so,” says Varun Advani, COO, makemyreturns.com. CAs advice them to re-send their ITR-Vs physically to the department before the deadline to aviod any further problems.