Audit giants see dominance waning

India’s audit landscape is undergoing a quiet change as the new rules for time-based rotation of auditors gather pace.

Early audit changes this year indicate the larger entities, such as Deloitte’s network, could face some pressure on their dominance. And, those lower down the order could gain ground. Leading firms are looking at increasing the focus on quality and are exploring new opportunities, such as private equity-backed ones in the unlisted space. Smaller entities such as Walker Chandiok, part of the Grant Thornton network, have ramped up their staff strength to handle new clients.

Close to 400 companies listed on the National Stock Exchange (NSE) have already changed auditors over the past three years, with clients changing hands among top audit firms. There is also pressure on pricing as the war for market share begins to intensify among top audit firms. This has resulted in a spike in demand for experienced auditors, with joining remuneration seeing 20-30 per cent jumps.

Audit giants see dominance waning
The revamped Companies Act of 2013 said every Indian company with a paid-up equity capital of Rs 20 crore or more was required to replace auditors after two five-year terms in succession. The law had given a three-year transition period for those which had to change auditors, ending March 2017. In the current financial year, 2016-17, around 40 NSE-listed companies have already switched to new auditors. More announcements are expected over the coming three months, shows data from Prime Database. In 2014-15 and 2015-16, a total of 339-NSE listed companies had settled for new auditors.

“We will be rotating off some of the larger companies. Simply because of the number and size of listed companies we audit, there will be changes in our audit market share,” said Shyamak Tata, partner, Deloitte Haskins Sells. He said large-scale changes in their portfolio were only expected from the third year onwards.

The Deloitte group’s network of audit companies is expected to see the largest churn. It has the biggest number of marquee audit clients. The network earned Rs 300 crore in fees for the year 2014-15, representing 15 per cent of the total pie of the Rs 2,000 crore audit fee market for 1,451 NSE-listed firms. It also audited the highest number of listed entities, at 149. The EY network made Rs 121 crore from the 108 companies. The PwC network audited 65 listed ones but had the lowest fee income among the ‘Big Four’ in audit, of Rs 65.6 crore. The KPMG network audited the lowest number of listed entities, at 58; however, it earned more than PwC at Rs 99.4 crore. Companies are still in the process of reporting the FY16 numbers.

Churn on
Early numbers suggest this pecking order is already going through a churn. A Business Standard analysis of data provided by Prime Database showed of the 41 auditor changes reported so far this year in listed companies, the KPMG network was the biggest gainer, with 11 new firms for the financial year ending March 2017. It was rotated out of two existing clients, a net gain of eight for FY17. The EY network added six and lost two, while Walker Chandiok gained a lone company. The PwC and Deloitte networks have lost more than they’ve gained so far this year. At the end of the changes, other smaller audit firms had 23 clients, up from 18 in FY16, among these 40 companies.

Grasim, Cipla, Biocon, Vedanta, Hindustan Zinc, United Spirits and Century Textiles are some of the large companies that have reported auditor changes for the new financial year.  In FY16, as many as 168 listed companies changed their auditors. The Deloitte network was the top gainer among the first five, gaining 17 and losing 11. The KPMG network was also a net gainer, with seven gains and four losses. EY, PwC and Walker Chandiok lost more than they gained.

In FY15, when 171 companies changed auditors, Walker Chandiok’s client list swelled by eight. While the EY network and Deloitte registered a net gain of one each, the KPMG and PwC networks recorded a net loss of four and one, respectively.

Strategy
Deloitte, expecting a strong attack on its dominance, is looking for greener pastures. “We are large in the listed company space, and have a majority share across industry sectors.  Our audit breadth and experience in this changing regulatory environment provides us, currently and over the next two-three years, an opportunity to provide audit services to untapped listed and unlisted entities, with a bias in favour of unlisted clients,” said Tata.

Other large entities are also gearing up for the transition. Russell Parera, partner, Price Waterhouse Chartered Accountants LLP, said his network had embarked on a transformation programme focussing on people, technology and processes for close to two years. “We have taken significant efforts in training our people for this change. Also, with rotation kicking in, it is going to be important to focus on investing in relationship building.”

The PwC network also bets on technology as another aspect, which will go a long way in these ever-evolving market scenario. “Today, technology has become a crucial enabler, with more data audits getting conducted. It is also relevant in cross border and multi-location audits to ensure consistency. We as a firm have been preparing for this change,” Parera added.  Tata of Deloitte spoke of pricing pressure in certain pockets. “We are seeing this as a section of the market looks to gain market share.  There will be some short- term blips. However, with continuing investment in innovation and quality, which will lead to enhancing value to clients, over the short term, this will correct. We already have a large pool of audit talent. We are looking at consolidating and not dramatically increasing the headcount. Audit will remain the primary identity of our firm and, with our focus on quality, we will retain our leading position in the overall  space.”

Impact
According to Akhil Bansal, deputy chief executive of KPMG India, with European audit rotation also coming into effect, the impact of Indian mandatory company rotation regulations will be felt around the globe. “The choice of the audit firm in India might influence the choice in Europe and other geographies,” he added. Bansal said the impact of mandatory firm rotation will also be felt on other services, including internal audit, due to stringent independence requirements. “It is important that the companies make their choice of audit firm early, since the best resources will be committed to clients who are first off the block,” he said.

Audit companies have been preparing for this, with investment in personnel, training and ramping up headcount numbers. For instance, the Grant Thornton network plans to double its auditor numbers across its network from 1,500 to 3,000. Vishesh Chandiok, national managing partner, Grant Thornton India LLP, said: “Several local Indian firms are very competent and the belief that only us international firms are the option is misplaced. Not all 50,000 firms for each company but certainly 50 firms can audit most companies, not only four of five firms.”

The EY group, which has 3,000 auditors across its network, added 400 over the past 12 months. “Internally, our focus continues to be on strengthening our teams with more hiring, greater investments in training, sharpening technical and industry capabilities  and increasingly, using more technology and, data analytic tools when performing audits,” said  Sudhir Soni, national leader, SR Batliboi, the Indian member-firm of EY Global.

Most audit companies have resorted to internal promotions and inducting of new talent to expand resources.

With the threshold for audit rotation being low, most audit companies are looking at tapping the unlisted private audit space in a big way. That’s a space the Deloitte network companies plan to play the game hard, indicated Tata. The client churn among audit firms is expected to last over the next two-three years, before it stabilises.
Source: http://www.business-standard.com/article/companies/audit-giants-see-dominance-waning-116062600777_1.html

Corporate Affairs Ministry again extends statutory filing deadline amid MCA21 woes

Extending the deadline for the third time, Corporate Affairs Ministry has now given time till July 7 for companies to submit their statutory filings as issues related to MCA21 portal are yet to be fully resolved.

MCA21 is used for making electronic filings under the Companies Act and is managed by Infosys  for the ministry.

The upgraded system went live in the last week of March and stakeholders have been facing issues in using the portal.

The Ministry has extended the filing deadline for the third time in less than two months.

Initially, the extension was till May 10 and later the deadline was fixed for June 10.

Giving more time, the Ministry has extended the time limit for making the requisite filings under the companies law to July 10.

“…keeping in view, requests received from various stakeholders, it has been decided to extend the period for which the one time waiver of additional fees is applicable to all e-forms which are due for filing by companies between March 25 to June 30, 2016 as well as extend the last date for filing such documents and availing the benefit of waiver to July 7, 2016,” it said in a communication dated May 31.

While the communication does not mention anything about MCA21, Ministry officials expect to resolve the issues related to the portal soon.

On April 6, an Infosys spokesperson had said it was working with the Ministry to resolve the “minor teething problems” related to MCA21.

The portal is designed to fully automate all processes related to enforcement and compliance of legal requirements under the Companies Act.

Meanwhile, the Ministry has also extended the time limit for submitting Form 11 of LLP in respect of 2015-16 financial year without any additional fees to June 30.

Form 11 is for filing annual returns LLPs.

Source: http://economictimes.indiatimes.com/articleshow/52556624.cms?utm_source=contentofinterest&utm_medium=text&utm_campaign=cppst


The Companies (Amendment) Bill, 2016 introduced in Loksabha

On 16th March 2016 Lok Sabha has passed the Companies (Amendment) Bill 2016 to further amend the Companies Act, 2013

The Act introduced significant changes related to disclosures to stakeholders, accountability of directors, auditors and key managerial personnel, investor protection and corporate governance. However, Government received number of representations from industry Chambers, Professional Institutes, legal experts and Ministries/Departments regarding difficulties faced in compliance of certain provisions. Amendments of the Act were carried out through the Companies (Amendment) Act, 2015 to address the immediate difficulties arising out of the initial experience of the working of the Act, and to facilitate “ease of doing business”.

The changes introduced are broadly aimed at addressing difficulties in implementation owing to stringency of compliance requirements; facilitating ease of doing business in order to promote growth with employment; harmonization with accounting standards, the regulations of Securities and Exchange Board of India Act, 1992 and the Reserve Bank of India Act, 1934; rectifying omissions and inconsistencies in the Act, and carrying out amendments in the provisions relating to qualifications and selection of members of the National Company Law Tribunal and the National Company Law Appellate Tribunal in accordance with the directions of the Supreme Court.

The Companies (Amendment) Bill, 2016, inter alia, proposes the following, namely:—

  • Simplification of the private placements: Simplification of the private placement process by doing away with separate offer letter, by making filing of details or records of applicants to be part of return of allotment only, and reducing number of filings to Registrar;

Earlier, there was significant difficulty was created by the Companies Act, with the unduly restrictive set of provisions pertaining to private placements. This over-ambitious scheme of regulation was a direct result of some incidents in the past. One such provision requires every private placement to be routed through a separate bank account opened for this purpose, and a bar on utilization of the money until allotment. More often than not, the amount received in private placement is large, and companies cannot afford to keep the amount idle.

Now, this private placements process has been simplified with the Companies (Amendment) Bill, 2016.

(b) Allow unrestricted object clause in the Memorandum of Association dispensing with detailed listing of objects, self-declarations to replace affidavits from subscribers to memorandum and first directors;

(c) Provisions relating to forward dealing and insider trading to be omitted from the Act;

(d) Requirement of approval of the Central Government for Managerial remuneration done away with:

Requirement of approval of the Central Government for Managerial remuneration above prescribed limits is replaced by approval through special resolution by shareholders;

Central Government control on managerial remuneration is eliminated. Section 197, which places limits on managerial remuneration, will now require special resolution only, if the limits placed under the law are exceeded.

(e) Loans to entities in which directors are interested:

A company may give loans to entities in which directors are interested after passing special resolution and adhering to disclosure requirement;

 (f) Provisions easing business by overseas entities

In support of the “Make in India” policy, it is quite appropriate that the Companies (Amendment) Bill, 2016 must have enabled foreign owned businesses to form companies in India. Accordingly, there are several provisions to facilitate foreign-owned businesses:

– EGM of a wholly-owned subsidiary of a foreign company may be called anywhere in India.

– The requirement for a resident director provided in section 149 is sought to be amended to provide that in case of newly incorporated companies the condition may be satisfied subsequent to incorporation, rather than before incorporation.

– Remove restrictions on layers of subsidiaries and investment companies

(g) Allow for exempting class of foreign companies from registering and compliance regime under the Act;

(h) Align prescription for companies to have Audit Committee and Nomination and Remuneration Committee with that of Independent Directors;

(i) Test of materiality to be introduced for pecuniary interest for testing independence of Independent Directors;

(j) Disclosures in the prospectus required under the Companies Act and the Securities and Exchange Board of India Act, 1992 and the regulations made thereunder to be aligned by omitting prescriptions in the Companies Act and allowing these prescriptions to be made by the Securities and Exchange Board of India in consultation with the Central Government;

(k) Provide for maintenance of register of significant beneficial owners by a company, and filing of returns in this regard to the Registrar;

(l) Removal of requirement for annual ratification of appointment or continuance of auditor;

(m) Amend provisions relating to Corporate Social Responsibility to bring greater clarity.

http://www.prsindia.org/uploads/media/Companies,%202016/Companies%20bill,%202016.pdf

CBEC for voluntary code for e-retailers to curb illicit trade

Expressing concern over sale of fake products on e-commerce platform, CEBC today said it is considering putting in place a voluntary code of practice for e-retailers to curb illicit trade.
“New challenges are emerging for customs. E-commerce is one such major area of vulnerability. E-commerce in India provides an unparalleled platform for sellers of both genuine and counterfeit products. So, we are looking at possibility of introducing voluntary code of practice for e-retailers,” Central Board of Excise and Customs (CBEC) Chairman Najib Shah said at an event organised by Ficci here.
The easy concealment of identity encourages sale of counterfeit products on the e-commerce platform. At times, intermediaries are denied judicial protection in the absence of strong law, he said.
To address the challenges posed by e-commerce trade, Shah said CBEC will at a seminar next month discuss with stakeholders the possibility of introducing ‘voluntary code of practice’ for e-retailers to fight illicit trade.
Stating that any smuggling and counterfeit activities is a matter of great concern to the government, the CBEC chief said, “This game is done at the cost of the honest tax payers. Though it results in financial gain to the person infringing the law but it is a financial loss to the exchequer.”
Shah also emphasised on the intellectual property rights and called for structured interaction between the customs and stakeholders on this issue.
The latest report, ‘Emerging challenges to legitimate business in the border-less world’, prepared by tax and advisory firm Grant Thornton and industry body Ficci, also noted that online marketplaces have become a “preferred hub for illicit operations” owing to their wider reach and ease of access.
Prominent players including Alibaba, Amazon and SnapDeal, etc have been at the receiving end of imitation products offered by third parties not connected to the brand owner, the report said and suggested e-retailers to put in place an holistic anti-counterfeit policy.
That apart, the report also pitched for a separate e- commerce law in the country to check illicit trade.
“In the absence of a specific e-commerce legislature in India and other laws including the Information Technology Act, Indian Companies Act, Companies Act 2013, Intellectual property, laws in copyrights and trademark etc, there are certain grey areas. Thus, there is a need for a separate e- commerce law in the country,” the report said.
The e-commerce regulations have a long way to go in India and inching closely towards this journey is the recent proposal of the Consumer Affairs Ministry to bring e-commerce businesses under the purview of multiple government agencies, the report added.
The report was released here by Food and Consumer Affairs Minister Ram Vilas Paswan. (PTI)

Source: http://www.dailyexcelsior.com/cbec-for-voluntary-code-for-e-retailers-to-curb-illicit-trade/

India Inc takes to social causes (CSR)

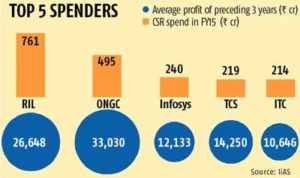
The move to make corporate social responsibility (CSR) spending mandatory has resulted in a spurt in social spending by India Inc. Spending on CSR activities by the top 100 companies increased to Rs 5,240 crore in 2014-15. The figure had stood at Rs 3,000 crore in 2012-13, when CSR spending was voluntary. Corporate governance firm Institutional Investor Advisory Services (IiAS) projects spending will increase to Rs 8,500 crore in the current financial year.

The Companies Act, 2013, requires companies above a certain financial threshold to spend at least two per cent of their average net profit of the preceding three years on CSR. Although CSR spending is compulsory, the Act has taken a ‘comply or explain’ approach, where a company has to provide reasons if the spending is less than the stipulated amount.

According to IiAS, CSR spends in FY15 were 26 per cent lower than the prescribed amount.

“Even as CSR is entering corporate consciousness, the next two to three years will remain a ‘learning period’ for industry,” the governance firm said in a note on Tuesday.

India Inc takes to social causes
IiAS has tracked the spending of BSE 100 companies, where 95 companies qualify under the profitability criteria for mandatory spending. The remaining five companies were not required to spend as they made average losses in the preceding three years.

State-owned firms set aside lesser amount compared to private sector firms. In FY13, public sector units (PSUs) spent 0.6 per cent of their average profits in the preceding three years. In comparison, non-PSUs spent one per cent of their average profit before tax of the preceding three years.

The trend continued in FY15. The CSR spends of the S&P BSE 100 companies aggregated 1.5 per cent of their three-year average profits. Non-PSUs spent 1.6 per cent and the 21 PSUs spent 1.3 per cent of their average profit in the preceding three years, IiAS noted.

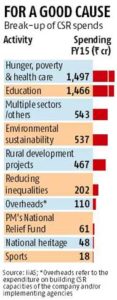
Close to Rs 61 crore of the CSR spends by India Inc in FY15 was towards the Prime Minister’s National Relief Fund and seven companies contributed Rs 47 crore towards Swachh Bharat Kosh.

Source: http://www.business-standard.com/article/companies/india-inc-takes-to-social-causes-116010500776_1.html

MCA extends last date of filing of AOC-4 and MGT-7 E-Forms to 30.01.2016 to Tamil Nadu & Pondicherry

MCA

The Circular from Ministry of Corporate Affairs extends one more month time, for Annual Filings of MGT -7 , Annual Return & AOC-4, Audited Financial Statements, without additional fees, to Tamil Nadu & Pondicherry, which were affected by floods.

The extract of the circular issued today, i.e., 30 December, 2015 is as below:


In continuation of the ministry’s circular 15/2015 dated 30.11.2015, keeping in view the requests received from various stakeholders stating that due to heavy rains and floods in the State of Tamil Nadu and Union Territory of Puducherry, the normal life/work was affected, it has been decided to relax the additional fees payable for the State of Tamil Nadu and UT of Puducherry on e-forms AOC-4, AOC (CFS) AOC-4 XBRL and e- Form MGT-7 up to 30.01.2016, wherever additional fee is applicable.

The last date of filing forms AOC-4 (XBRL, non-XBRL & CFS) and MGT-7 till 30th Dec 2015, without additional fees, has ended.


The Ministry of Corporate Affairs, Government of India has earlier vide its General Circular No.15/2015 dated 31/11/2015, extended the last date for filing the Annual Returns by 30 days and relaxed the additional fees for the forms filed till December 31, 2015. This has ended now.


* * * * * * *


Integrated e-Form INC-29 for Company Incorporation and Ease of doing business

INC 29Analysis of integrated e-Form INC-29 for Company Incorporation and Ease of doing business

With the introduction of the INC-29, the Ministry of Corporate Affairs (MCA) has begun to make good on its promise to improve India’s ranking on the World Bank’s Ease of Starting a Business Index to within the top 50 from the current 158.

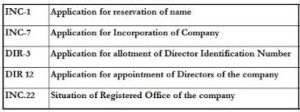
The INC-29 form for company registration, combines the application for DIN allotment, name reservation, incorporation and even PAN & TAN, while making the process faster and simpler. As the entire incorporation process is in a single form, correct filing could mean approval in 48 hours. Compared to the old process, this helps in formation of company saving a lot of time, if properly implemented.

Purpose of the eForm – eForm INC-29 deals with the single application for reservation of name, incorporation of a new company and/or application for allotment of DIN. This eForm is accompanied by supporting documents including details of Directors & subscribers, MoA and AoA etc. Once the eForm is processed and found complete, company would be incorporated with Corporate Identification Number (CIN) and the Certificate of Incorporation would be issued. Also DINs gets issued to the proposed Directors, who do not have a valid DIN. Maximum three Directors are allowed for using this integrated form for allotment of DIN while incorporating a company.

Key Features of e-form INC-29 

  1. The integrated e-Form INC-29 is available with effect from 01.05.2015 for One Person Company, Private Company as well as Public Company.
  2. INC-29 does away with filing of multiple applications/forms saving time and payable fees.

It combines the processes relating to:-

  • Allotment of Director Identification Number (DIN) (up to three Directors),
  • Incorporation of a company, and
  • Appointment of first Directors of the company.

3. The new e-Form does away with the need for reserving a name for the company prior to applying for its incorporation.

  1. Declarations are in-built in the e-Form. Separate attachments containing such declarations are not required.
  1. The e-Form is enabled for future integration with e-Biz platform of DIPP for generating applications for PAN, ESIC and EPFO numbers on the platform and therefore provides a single interface for these applications also.


Forms no longer to be filed individually as per the new Form INC 29:

Continued