200,000 more directors disqualified for holding posts in defaulting companies

The govt has struck off more than 200,000 firms that have not complied with the provision of the law from the list maintained by the RoC and frozen their bank accounts to check any siphoning off of funds.

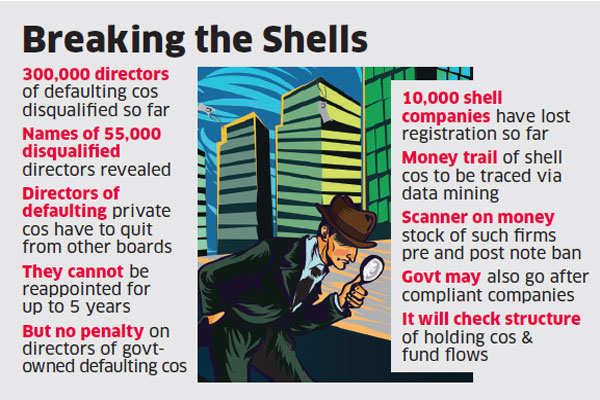
The corporate affairs ministry has disqualified another 200,000 directors for holding posts in defaulting companies that have not filed their financial returns for the last three years or more, taking the total number to over 300,000, while cancelling the registration of another 10,000 companies.

These directors won’t be able to hold board seats in other companies as well and may have to resign soon from them, potentially impacting other firms as well.

While the current law does not provide for any appeal, the government is thinking of exercising “the review power to take any such plea into consideration,” PP Chaudhary, minister of state for corporate affairs, told ET. “By operation of law, these directors are disqualified but we have to see under what provision of law we can examine this. If we need to frame a rule we will do it.”
According to Section 167 of the Companies Act, a director is disqualified automatically from all other posts of director once barred under Section 164, said Chaudhary, a lawyer by profession.

200,000 more directors disqualified for holding posts in defaulting companies

The government has struck off more than 200,000 firms that have not complied with the provision of the law from the list maintained by the Registrar of Companies and frozen their bank accounts to check any siphoning off of funds.

“This exercise is part of demonetisation. No one had the guts to stop all this till now. It will prove a catalyst for the Indian economy,” said the minister of state, who took over this responsibility after the recent reshuffle. He said the money trail will be traced after data mining of these companies.


The government will prioritise those cases where there is evidence of a large movement of cash. He rejected the criticism that the action was retrospective in nature.

“Law has not been retrospective. Companies had two years to file returns… there was healing time,” the minister of state said. So far the shell firm chase has been limited to defaulting firms that have not filed their financial returns for the last three years or more but the government will soon go after compliant firms as well to check their holding companies structures and fund flows.

Chaudhary said the intent is to restore trust in the corporate structure and also improve ease of doing business in the country.

“We do not want to create any terror. Trust in the corporate structure is gone and we want to increase the investor confidence, not interfere in the corporate structure,” Chaudhary said.The government wants to promote ease of doing business to ensure investors that their money is safe in India, he added.

“This exercise has been triggered due to governance. We have shown scale and speed in an unparalleled way in the way we have acted against these companies and directors,” Chaudhary said.

Last week, the government made public the names of 55,000 directors who were disqualified under Section 164 (2) (A) of the Companies Act. The list included the names of prominent politicians including former Jammu and Kashmir chief minister Omar Abdullah and Malayalam filmstar Mohanlal among others.While the government will not impose any penalty on the directors of government-owned companies that figured in the list of defaulters, those in private firms will have to resign from other board seats and won’t be eligible for reappointment for up to five years.

The corporate affairs ministry will also look into these companies to identify shell companies to see if they have been used for money laundering or any other illegal activity. “We need to find who the shell company’s real beneficiary is… It could be in the name of the cook or a driver. We are taking stock of the money in these companies pre and post demonetisation,” Chaudhary said.

While spotting defaulting companies is an ongoing process, Chaudhary said that, using artificial intelligence, the government will sift out the shell companies from among those that are compliant with regulations and also create an early warning system. “The system will trigger alerts every time we see unusual activity taking place in a company. It will also help us find out the beneficial owner of the shell companies,” he said.
Auditors come under lens amid crackdown on shell companies

A multi-agency clampdown has begun on shell companies to tackle the black money menace wherein the role of auditors has come under the scanner for alleged connivance in facilitating illegal transactions.

The auditors’ role is also being looked into for not raising the red flag as several cases have come to the fore, including at listed companies, for alleged mismatch in financial statements, sharp erosion in net worth, siphoning off funds to group and promoter entities, sources said.

Stepping up the vigil, the corporate affairs ministry as well as Sebi and other regulatory authorities are keeping a close tab on activities carried out by shell companies.

Sources said regulatory agencies are examining the role of auditors to ascertain whether they were also involved in suspected illegal activities.

The ministry as well as Sebi are closely looking at the functioning of auditors in various companies, especially those that have not been carrying out business for long. After a detailed analysis, the authorities would decide on the next course of action, sources added.

Auditors, who have greater responsibilities under the Companies Act, 2013, are required to ensure that financial statements of a company are proper and can red flag dubious transactions.

As part of larger efforts to fight illicit fund flows and tax evasion, the ministry has already struck off the names of over two lakh companies from the records and further action is expected.

Besides, Sebi has taken against 331 listed entities that are suspected shell companies. While the watchdog had imposed strict trading restrictions on these scrips, curbs have been eased in some cases after the companies went on appeal against Sebi’s move.

On Tuesday, the government said more than 1.06 lakh directors would be disqualified for their association with shell companies.

The ministry, which is implementing the companies law, has also identified professionals, chartered accountants, company secretaries and cost accountants associated with the defaulting companies.

Besides, such people “involved in illegal activities have been identified in certain cases and the action by professional institutes such as ICAI, ICSI and ICoAI is also being monitored”, an official release said on Tuesday.

Separately, authorities are looking at the possibility of having stricter scrutiny of global auditing firms to make them more accountable with such auditors coming under the lens in various corporate misdoings.

A big area of concern pertains to the big guns seeking to wash off their hands whenever their names crop up in any accounting wrong-doing while their delaying tactics in the name of jurisdiction have also been noticed, an official had said earlier.

While the existing legal framework provides for stringent provisions for auditing activities, there is no specific system in place when it comes to overseas audit firms.

While discussions on having tighter regulations for foreign audit firms are going on, the ministry is already examining the recommendations of the 3-member expert panel on various issues related to audit firms amid concerns over certain practices circumventing regulations.

 The expert panel, headed by Teri Chairman Ashok Chawla, had submitted its report in March this year.

Attack on shell firms: MCA issues notices to errant NBFCs

In yet another attempt to crack the whip on shell companies, the Ministry of Corporate Affairs has issued notices to companies which were supposed to act as non-banking financial companies (NBFCs) but have not registered with the Reserve Bank of India (RBI).

The ministry has taken this action to seek an explanation from these companies on their businesses within 10 days, a source said

If companies are found to be in the non-banking financial activities such as lending, investment or deposit acceptance as their principal business, without the RBI registration, the central bank can impose a penalty or even prosecute them in a court of law.

A similar attempt was undertaken by the RBI a few years back. In 2013, the RBI had clamped down on unregistered NBFCs after the Saradha scam. The central bank undertook such an exercise even in 2014. The pan-India figure of such entities back then was around 70,000. The number of non-registered NBFCs has risen since then, an official said.

The Securities & Exchange Board of India (Sebi) had recently put 331 companies on heightened surveillance. It also delisted entities it suspected of being shell companies. The Centre, too, has frozen bank accounts of 200,000 companies after these were struck off by Registrar of Companies. The directors of these firms were also banned.

The Centre and its agencies are not only taking corrective action but are also initiating pre-emptive steps to check the menace of dormant companies. It is working with Sebi to get all public unlisted companies to issue shares online. Experts said this would ensure greater transparency in these companies and bring down litigation.

After demonetisation, a number of shell companies were found to be operating with the same address, not directly contributing to the mainstream economy. It was then that the government sprung into action.

An NBFC is a company registered under the Companies Act, 1956, engaged in the business of loans and advances among other functions. It is also a company which receives deposits under any scheme or arrangement in one lump sum or in installments by way of contributions or in any other manner, as its principal business.


Source: Business Standard

Over 2.09 lakh firms struck off, bank accounts frozen: Govt

In a major clampdown against black money, the government on Tuesday directed freezing bank accounts of more than 2.09 lakh companies whose names have been struck off from the records and said action would be taken against more such firms.

Banks have also been asked to step up their vigil against those companies that are non-compliant with various regulations and not carrying out business activities for long, a senior finance ministry official said as authorities continue their crackdown against shell entities The official said banks have been directed to freeze the bank accounts of these deregistered companies.

While warning that action would be taken against erring firms, the official said the efforts would help in enhancing corporate governance standards as well as clean up the system that otherwise is prone to be misused.

The names of over 2.09 lakh firms have been struck off from register of companies for failing to comply with regulatory requirements

“The names of 2,09,032 companies have been struck off from the register of companies under Section 248 (5) of the Act. The existing directors and authorised signatories of such struck-off companies will now become ex-directors or ex- authorised signatories,” an official release said

Section 248 of the Companies Act – which is implemented by the corporate affairs ministry – provides powers to strike off names of companies from the register on various grounds including for being inactive for long.

According to the official, since these companies had ceased to be legal entities, there was no reason having active bank accounts which could be prone to misuse.

Once these companies become compliant, banks would activate their accounts, the official added. “Furthering our war against #BlackMoney, banks have been advised to immediately restrict bank accounts of struck-off companies,” Minister of State for Corporate Affairs P P Chaudhary said in a tweet.

The official said a detailed analysis has been initiated to check whether these deregistered companies were used as conduits for channelising unaccounted money into the system, especially during demonetisation.

Amid efforts against shell companies which are allegedly used as conduits for illicit fund flows and tax evasion, the government said the directors of deregistered firms would not be able to operate the bank accounts till these entities are legally restored

About the directors and signatories of the over 2.09 lakh firms, the government said they would not be able to operate bank accounts of such companies till these entities are legally restored. The restoration, as and when it happens, would be reflected in the official records by way of change in the status from ‘struck off’ to ‘active’. “Since such ‘struck off’ companies have ceased to exist, action has been initiated to restrict the operation of bank accounts of such companies,” the release said.

The Department of Financial Services, through the Indian Banks Association, has advised banks that they should take immediate steps to put restrictions on bank accounts of such struck-off companies. “In addition to such struck-off companies, banks have also been advised to go in for enhanced diligence while dealing with companies in general,” the release said.

A company even having an active status on the corporate affairs ministry website but defaulting in filing of its due financial statements or annual returns, among others, “should be seen with suspicion as, prima facie, the company is not complying with its mandatory statutory obligations”. In another tweet, Chaudhary said the ministry is committed “in attaining @narendramodi ji’s vision of eliminating black money”.

Source:DD News

SEBI plans stricter norms for Independent Directors

Markets watchdog Securities and Exchange Board of India (SEBI) plans to overhaul the regulatory framework for corporate governance, including appointment and removal of independent directors, people familiar with the matter said.

Besides, a high level panel is looking at corporate governance issues such as those pertaining to related party transactions, auditing and effectiveness of board evaluation practices, the people added.

Against the backdrop of recent instances of boardroom battles involving large corporates, the SEBI is looking to revamp the norms and the matter is expected to be discussed at its board meeting later this month.

Strengthening corporate governance practice is a focus area for the regulator, with SEBI chairman Ajay Tyagi recently saying, “independent directors are not independent”.

The regulator is keen on stricter norms for independent directors, including with respect to their appointment, removal and larger responsibility as part of a company’s board, the people said.

Currently, an independent director can be removed by way of an ordinary resolution — which requires the approval of at least 50 percent shareholders of a particular company.

However, when it comes to re-appointment of independent directors, the firm concerned has to move a special resolution under which nod from 75 percent or more shareholders is required.

According to sources, SEBI wants to make it special resolution mandatory for removal of an independent director as such a provision will reduce the arbitrariness of promoters in deciding upon the ouster of such directors.

Besides, stringent disclosure requirements for independent directors, including at the time of their appointments, are being looked at, sources said.

Corporate governance issues will be among the slew of developments that are to be discussed during the SEBI board meeting scheduled for June 21.


Earlier this month, the watchdog set up a 21-member committee under the chairmanship of veteran banker Uday Kotak to suggest ways to further improve corporate governance standards of listed companies.

The panel will make recommendations on ensuring independence in spirit of independent directors and their active participation in functioning of the company.

Besides, measures to address issues faced by investors on participation in general meetings and ways for improving effectiveness of board evaluation practices will be suggested by the committee.

Apart from Kotak, who is the chairman of Kotak Mahindra Bank, other members include HDFC CEO Keki Mistry, Wipro chief strategic officer Rishad Premji, L&T Whole Time Director R Shankar Raman and BSE CEO Ashishkumar Chauhan.

In April, Tyagi had said there were too many lacunae with respect to the concept of independent directors with many having “no commitment to any cause”.

“I must admit I have no solutions on what should be done but it will be anyone’s case that existing system has lot of lacunae,” he had said.

Some independent directors are appointed at the mercy of promoters “(with) no prescribed qualifications or procedures, favouritism, (many are from) closed clubs (such as) only those people being in all boards, no commitment to any cause – Ajay Tyagi, Chairman, SEBI


Earlier this year, the regulator came out with detailed corporate governance norms for listed companies that provide for stricter disclosures and protection of investor rights, including equitable treatment for minority and foreign shareholders.

The new rules, which would be effective from October 1, require companies to get shareholders’ approval for related party transactions, establish whistle blower mechanism, elaborate disclosures on pay packages and have at least one woman director on their boards.

Source: https://www.bloombergquint.com/law-and-policy/2017/06/12/market-regulator-sebi-plans-stricter-norms-for-independent-directors

Government prepares to strike off registration of over 2 lakh companies

Defunct or Inactive Companies - Fast Track Exit Scheme / Strike off of companies under Companies Act, 2013
Defunct or Inactive Companies – Fast Track Exit Scheme / Strike off of companies under Companies Act, 2013

The government plans to cancel the registration of more than two lakh companies that have not been carrying out business for a considerable period of time, amid stepped up efforts to tackle the black money menace.

More than two lakh companies, spread across various states, have been served with show cause notices as they have not been carrying out any operation or business activity for a prolonged time.

The Corporate Affairs Ministry’s move also comes against the backdrop of overall efforts by the authorities to crack the whip on shell companies, suspected to be used for money laundering activities.

The Registrars of Companies (RoCs) in various states and union territories have issued notices to more than two lakh firms under the Companies Act, 2013, according to information available with the Ministry.

These notices have been issued under Section 248 of the Act, which is implemented by the Ministry. This section pertains to striking off names of companies on certain grounds.

With the issuance of notices, the companies concerned have to explain their position and if the responses are not satisfactory, then their names would be struck off by the Ministry.

Data showed that RoC Mumbai has issued notices to more than 71,000 companies while RoC Delhi has served notices to over 53,000 firms, among others.

As per the regulations, an RoC can seek explanation from a company if the latter has not commenced business within one year of getting incorporated under the Act.

Notice is also issued if a particular company has not been carrying out business for at least two continuous financial years and has not applied for dormant status.

Such entities are given a time of 30 days to submit objections if any.

The Ministry has power to remove or strike off the names of such entities from the “register of companies” if the response is not satisfactory.

Earlier this month, the Ministry had amended the Companies (Removal of Names of Companies from the Register of Companies) Rules.

There are more than 15 lakh registered companies in the country.