MCA scanner on banks lending to deregistered companies

So far 13 banks have provided information to the government on 13,140 accounts of 5,820 deregistered companies, with the most startling details emerging from IDBI Bank, Bank of Baroda and Canara Bank.

The corporate affairs ministry is likely to ask the department of financial services to take action against the banks which have continued lending to companies that have been deregistered.

The ministry is also likely to raise the issue of banks not showing urgency in sharing information on transactions of these companies before and after the announcement of demonetisation on November 8 last year.

The Registrar of Companies, which comes under the corporate affairs ministry, had struck off 2.09 lakh companies from the list of active establishments after they failed to comply with regulatory requirements. Banking transactions of these companies are restricted only for settling liabilities.

Despite this, according to sources, one government-owned bank has lent more than Rs 280 crore to a company after it was deregistered. Such transactions are likely to have occurred among other public sector banks as well, but the government still doesn’t have detailed data on the dealings, they said. “There is a need for greater transparency. We are simply waiting for the banks to come up with more information. Only a few have shared (the information) so far,” a senior government official said.
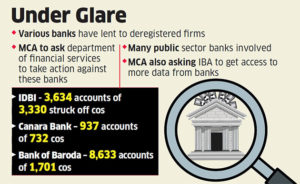
So far 13 banks have provided information to the government on 13,140 accounts of 5,820 deregistered companies, with the most startling details emerging from IDBI Bank, Bank of Baroda and Canara Bank.

Earlier this month, the government said these 5,820 companies had deposited Rs 4,573 crore post demonetisation in banks and withdrew Rs 4,552 crore, even as they held balances of just Rs 22 crore on the day demonetisation was announced. This number is likely to go up manifold once the banks share more data.

The government is probing accounts of all the 2.09 lakh companies that were struck off the registry, which previously had about 13 lakh companies.

Four banks — Qatar National Bank, Doha Bank, Emirates NBD Bank and Punjab Gramin Bank — stated that they didn’t hold any accounts of the suspect companies.
A few companies were found to be having multiple accounts in some banks, like Bank of Baroda, where one company held as many as 915 accounts.

Government tightens screws on assets owned by deregistered companies

According to the minister, since the country-wide land records have been computerised, it would not take much time for the states to provide the requisite information to the district authorities and the central government.

The corporate affairs ministry today asked states to complete identification of properties owned by deregistered companies at the earliest and ensure district administrations prevent transactions in those assets.

Amid intensifying efforts to fight the black money menace, the ministry has also urged the states to initiate disciplinary action against the officials concerned in case such transactions go through.

The names of around 2.25 lakh companies which have not been carrying out business activities for long have been struck off the official records and a number of directors associated with such firms have been disqualified.

Against this backdrop, Minister of State for Corporate Affairs P P Chaudhary today held a review meeting with representatives from various states on action taken with respect to properties belonging to around 2.09 lakh deregistered companies.

During the meeting, Chaudhary asked the states’ representatives to complete the process of identification and tracking of properties belonging to such companies at the earliest, according to an official release.

In this regard, the states have been requested to share information with the ministry in a time-bound manner.

On September 12, the ministry had sent a letter to states for identification and tracking of properties belonging to around 2.09 lakh companies that were deregistered. Now, the number of such firms is about 2.25 lakh.

Additional state-wise information pertaining to such companies was also shared with the state representatives.

According to the minister, since the country-wide land records have been computerised, it would not take much time for the states to provide the requisite information to the district authorities and the central government.

Since the names of the companies have been struck off, any transaction pertaining to properties owned by them, their directors or authorised signatories would be “void ab initio and a nullity till such companies are restored by an order of the National Company Law Tribunal (NCLT), the release said.

“In fact, by virtue of the company’s name having been struck off from the Register of Companies under the Companies Act, 2013, its identity as a legal person had been lost and hence, the legal ownership of properties belonging to such a company was non-existent,” it added.

Chaudhary advised the representatives to ensure that requisite directions are urgently issued to all the district authorities dealing with registration of properties to put in place appropriate mechanism to prevent transactions in properties belonging to the deregistered companies.

Officials allowing registration of transactions in such properties by ignoring the requisite directions may be subjected to disciplinary action, he told the representatives.

Emphasising that tackling of shell companies is an imperative element in the fight against black money, Chaudhary said such a drive would help unearth benami properties and discourage illegal practices, which would create a healthy economic environment for honest businessmen.

Exporters can claim refund this week for GST paid in August, September

GST Network (GSTN), the company handling IT infrastructure for the indirect tax regime, has from October 10 started issuing refunds to exporters for Integrated GST (IGST).

Exporters can soon start claiming refunds for GST paid in August and September as GSTN will this week launch an online application for processing of refund, its Chief Executive Officer Prakash Kumar said today.

GST Network (GSTN), the company handling IT infrastructure for the indirect tax regime, has from October 10 started issuing refunds to exporters for Integrated GST (IGST) they paid for the month of July, after matching GSTR-3B and GSTR-1.

For August and September, while the initial return GSTR- 3B has already been filed, the final return GSTR-1 has not yet been filed.

“A separate online app for claiming Integrated GST (IGST) refunds for August and September would be made available on GSTN portal this week,” Kumar told .

GSTN has developed the app wherein exporters can save and upload their sales data which are part of GSTR-1 after filling up export details in Table 6A.

The table will be then extracted separately and after exporters digitally sign it, it would automatically go to the customs department.

The customs department will then validate the information provided in the table with the shipping bill data and also the taxes paid in GSTR-3B. The refund amount would be either credited to exporter’s bank account through ECS or a cheque would be issued.

As per data, 55.87 lakh GSTR-3B returns were filed for July, 51.37 lakh for August and over 42 lakh for September. Preliminary returns GSTR-3B for a month is filed on the 20th day of the next month after paying due taxes.

Thereafter, final returns in form GSTR-1, 2, 3 are filed by businesses giving invoice wise details of sales. The final return filing for August and September has not started yet.

Over July-August, an estimated Rs 67,000 crore has accumulated as the Integrated GST (IGST), of which only about Rs 5,000-10,000 crore will be due as refunds to exporters.

The Goods and Services Tax (GST), the amalgamation of over a dozen indirect taxes like excise duty and VAT, does not provide for any exemption, and so exporters are required to first pay Integrated-GST (IGST) on manufactured goods and claim refunds after exporting them. This had put severe liquidity crunch, particularly on aggregators or merchant exporters.

To ease their problems, the GST Council earlier this month decided a package for them that includes extending the Advance Authorisation / Export Promotion Capital Goods (EPCG) / 100 per cent EOU (Export Oriented Unit) schemes to sourcing inputs from abroad as well as domestic suppliers till March 31, thus not requiring to pay IGST.

The government is aiming to clear pending GST refunds of exporters by November-end. The first cheque after processing of July refunds was issued on October 10.

India should prioritise public banking sector reforms: IMF

Country's growth is expected to accelerate in the medium-term as temporary disruptions due to demonetization and GST.
Country’s growth is expected to accelerate in the medium-term as temporary disruptions due to demonetization and GST.

India must prioritise implementation of public banking sector structural reforms, enhance the efficiency of labour and product markets, and modernise agriculture sector to accelerate its growth, the IMF said Friday.

The country’s growth is expected to accelerate in the medium-term as temporary disruptions due to demonetisation and the Goods and Services Tax (GST) fade, the International Monetary Fund said in its Asia and Pacific Regional Economic Outlook Update.

The economic growth slowed in India in recent quarters due to the temporary disruptions from the currency exchange initiative demonetisation that took place in November 2016, and the recent rollout of the GST, it said.


The GST is a landmark tax reform that should help unify the domestic market and encourage businesses to move from the informal to the formal sector, the IMF noted.

Inflation has been low compared with the mid-point target in recent months, driven by lower food prices, allowing the central bank to cut its policy rate in August, it added.

“Growth in 2017 was revised downward to reflect the recent slowdown, but is expected to accelerate in the medium term as these temporary disruptions fade,” it said.

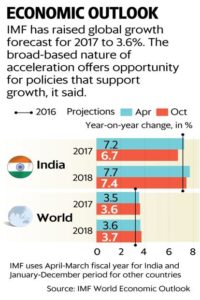
In India, growth was revised down to 6.7 per cent in FY2017 and to 7.4 per cent in FY2018.

“Growth will be underpinned by private consumption, which has benefited from low food and energy prices, as well as civil service allowance increases,” IMF said.

Headline inflation is projected to stay close to the midpoint of the target band (4 per cent 2 per cent) in FY2017, while moving to the upper half of the target band in the medium term as food prices recover, it said.

The current account deficit should remain modest, financed by robust foreign direct investment inflows, it noted.

According to the outlook, in India, priorities should be strengthening public banks loss-absorbing buffers, implementing further public banking sector structural reforms, and enhancing public banks debt recovery mechanisms.

“Reform efforts should aim at tackling supply bottlenecks, enhancing the efficiency of labour and product markets, and modernising the agricultural sector,” the IMF said, adding that labour market reforms should be a priority to facilitate greater and higher-quality job creation.


Source: Deccan Chronicle

IMF favors three structural reforms in India

According to IMF’s Regional Economic Outlook, India’s growth slowed in recent quarters due to the temporary disruptions from the currency exchange initiative– demonetisation and GST.

The IMF has suggested a three- pronged approach for structural reform in India that includes addressing the corporate and banking sector weaknesses, continued fiscal consolidation through revenue measure, and improving the efficiency of labour and product markets.

Deputy Director Asia Pacific Department of IMF, Kenneth Kang, said the favorable outlook for Asia was an important opportunity for India to push forward with difficult reforms.

“As such, there should be three policy priorities in the area of structural reforms,” Kang, Deputy Director Asia pacific Department IMF told reporters at a news conference here.

“First priority is to address the corporate and banking sector weaknesses, by accelerating the resolution of non- performing loans, rebuilding the capital buffers for the public sector banks, and enhancing banks’ debt recovery mechanisms,” he said.Secondly, Kang said, India should continue with the fiscal consolidation through revenue measures, as well as further reductions in subsidies.

“And lastly, it’s to maintain the strong momentum for structural reforms in addressing the infrastructure gaps, improving the efficiency of labour and product markets as well as furthering agricultural reforms,” said Kang.

Responding to a question on labour market reforms, Kang suggested reforming the market regulations in order to create a more favorable environment for investment and employment.

“There is a need to reduce the number of labour laws which currently number around 250 across the central and the state level,” said Kang.He said India should also focus on closing the gender gap which may help a great deal in boosting the employment opportunities for women in India.

“Improvements in infrastructure can be one important way to facilitate the entry of women into the labour force. But in addition, there is a need to strengthening the implementation of specific gender regulations, as well as to invest more in gender-specific training and education,” Kang said.

According to IMF’s Regional Economic Outlook, India’s growth slowed in recent quarters due to the temporary disruptions from the currency exchange initiative– demonetisation– that took place in November 2016, and the recent roll-out of the Goods and Services Tax (GST).

The report, however, went on to say that the growth in 2017 was revised downward to reflect the recent slowdown, but is expected to accelerate in the medium term as these temporary disruptions fade.

IMF says global growth recovery an opportunity for Indian economy

IMF expects the Indian economy to recover sharply in 2018 to grow at 7.4%, though 30 basis points lower than its earlier estimate in April.

The International Monetary Fund (IMF) on Tuesday pared its growth forecast for the Indian economy by half a percentage point to 6.7% for 2017, blaming the lingering disruptions caused by demonetisation of high value currencies last year and the roll out of the Goods and Services Tax (GST).

However, IMF said the structural reforms undertaken by the Prime Minister Narendra Modi-led government would trigger a recovery—above 8% in the medium term.

In its latest World Economic Outlook, IMF said the global economy is going through a cyclical upswing that began midway through 2016. It raised the global growth estimate marginally for 2017 to 3.6% while flagging downside risks. The upward revisions in its growth forecasts including for the euro area, Japan, China, emerging Europe, and Russia more than offset downward revisions for the United States, the United Kingdom, and India.

“In India, growth momentum slowed, reflecting the lingering impact of the authorities’ currency exchange initiative as well as uncertainty related to the midyear introduction of the countrywide Goods and Services Tax,” it said in the WEO.

However, IMF expects the Indian economy to recover sharply in 2018 to grow at 7.4%, though 30 basis points lower than its earlier estimate in April.

One basis point is one-hundredth of a percentage point.

In its South Asia Economic Focus (Fall 2017) released on Monday, the World Bank reduced India’s GDP growth forecast to 7% for 2017-18 from 7.2% estimated earlier, blaming disruptions caused by demonetisation and GST implementation, while maintaining at the same time that the Indian economy would claw back to grow at 7.4% by 2019-20.

Both the Asian Development Bank as well as the Organisation for Economic Cooperation and Development (OECD) have also cut their growth projections for India to 7% and 6.7%, respectively, for fiscal 2017-18.

IMF said a gradual recovery in India’s growth trajectory is a result of implementation of important structural reforms. GST, “which promises the unification of India’s vast domestic market, is among several key structural reforms under implementation that are expected to help push growth above 8% in the medium term,” it added.

The multilateral lending agency said India needs to focus on simplifying and easing labour market regulations and land acquisition procedures which are long-standing requirements for improving the business climate. It also called for briding the gender gap in accessing social services, finance and education to accelerate growth in developing countries like India.

IMF said given faster-than-expected declines in inflation rates in many larger economies, including India, “the projected level of monetary policy interest rates for the group is somewhat lower than in the April 2017 WEO.”

In its monetary policy review last week, the Reserve Bank of India (RBI) kept its policy rates unchanged and marginally raised its inflation forecast for rest of the year.

Highlighting the growing income inequality within and among emerging market economies, IMF said a country’s growth rate does not always foretell matching gains in income for the majority of the population. “In China and India, for example, where real per capita GDP grew by 9.6% and 4.9% a year, respectively, in 1993–2007, the median household income is estimated to have grown less—by 7.3% a year in China and only 1.5% a year in India,” it said.

Source: Live Mint

GST crashes even money lenders’ usurious rates

Rates have dipped to a third to 6 per cent from 9-18 per cent about 6-9 months ago.

Interest rates that money lenders charged borrowers hardly budged for decades irrespective of policy decisions. But even that is collapsing faster than what it is in the formal banking system, thanks to the implementation of Goods and Services Tax.

Borrowing in the informal market is no more lucrative.

Lenders who fund small traders and merchants have lowered their rates to just a third of what they were charging, but still the demand is not showing up.

Rates have dipped to a third to 6 per cent from 9-18 per cent about 6-9 months ago, said two dealers aware of the market dynamics.

“Those businessmen have now limited options to run operations in cash especially after GST implementation and demonetisation,” said a textile business owner, who did not want to be identified.

“From a local politician to an industrialist or local trader whoever has additional unaccounted cash are normally the lenders in this informal loan market.”

A huge army of businessmen borrowed in an informal market from money lenders to avoid getting trapped by the banking system and the tax department. This was known as ‘Kachha Credit’ among practitioners.

With the implementation of GST which produces a chain of transactions till it reaches the ultimate consumer, merchants have little scope to escape accounting for their trades.

So, instead of funding their purchases through informal credit at high rates which was beneficial since it allowed escaping the tax net, they are choosing to fund businesses through formal credit. To keep businesses running, money lenders have lowered rates.

Since the tax department is keeping close watch on businesses, all traders preferred anonymity. This market is known as a plat form for lending and borrowing unaccounted or untaxed money without any collateral. Traders now shy away from availing such credit amid cash squeeze triggered by reform measures like GST and demonetisation. Sometimes, people take highly leveraged positions borrowing such money, which a bank would have declined.

A garment trader who may be eligible to borrow say, Rs 10 lakh in the absence of creditworthy balance sheet, can take a loan up to Rs 50 lakh due to personal knowledge of businesses, dealers said. The practice is prevalent in the garment industry.

Mumbai’s Bhiwandi, a business centre, used to be the hotbed of it. It has died down after the Central Value Added Tax, a central government tax levy introduced by Vajpayee led NDA, was introduced.


Source: Economic Times