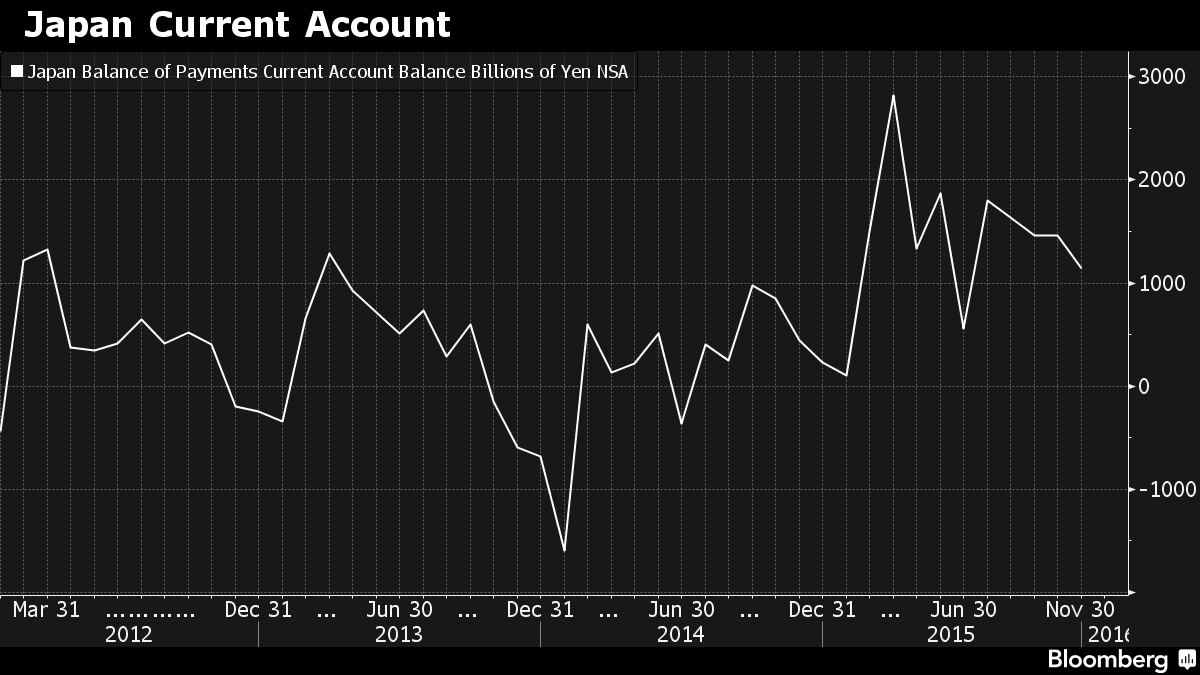
Japan posted a current account surplus for the 17th consecutive month in November, providing support for Prime Minister Shinzo Abe’s efforts to boost the world’s third-largest economy.
The excess in the widest measure of the nation’s trade was 1.14 trillion yen ($9.7 billion) in November, up from 440.2 yen billion a year earlier, the Finance Ministry said Tuesday in Tokyo. The median estimate of 23 economists surveyed by Bloomberg was for a surplus of 895 billion yen.
The surplus was supported by a rise in income from investments abroad by Japanese companies as well as a gain in services, which came with an influx of tourists after the yen weakened. The boost helps an economy that has been hurt by a slowdown in exports including to China, Japan’s biggest trading partner.
“The wider current account surplus bodes well for Japan’s economy,” said Junko Nishioka, chief economist for Japan at Sumitomo Mitsui Banking Corp. in Tokyo. “Going forward, Japan will likely hold onto the surplus trend.”
Declining oil prices and recent gains in the yen, which may push down import prices and improve the trade balance, is expected to help Japan maintain the current-account surplus in coming months, Nishioka said.
The primary income surplus was 1.54 trillion yen in November, the largest on record for November, according to the report. The services balance had a surplus of 61.5 billion yen, helped by charges for the use of intellectual property rights and travel.
FTA with EU: India to take up ‘stock-taking exercise’ for a free trade agreement with the EU later this month, after a gap of three years, and pitch for greater market access in services..
India will undertake a “stock-taking exercise” for a free trade agreement with the EU later this month, after a gap of three years, and pitch for greater market access in services once the stage is set for further negotiations, a senior commerce ministry official said.
Before engaging in serious formal talks on the EU-India Bilateral Trade and Investment Agreement (BTIA), a “stock-taking exercise” will be undertaken, as some contours of the earlier negotiations have to be altered, keeping in view the changes that have taken place since the talks were stuck in 2013, Arvind Mehta, additional secretary in the commerce ministry, told FE.
For instance, India has further liberalised many sectors for foreign investments, including some of the areas where the EU had interests, over the past three years. For instance, the FDI cap in insurance has been raised to 49% from 26% and 100% FDI is allowed in telecoms. In private sector banking, full fungibility of foreign investment is now permitted and accordingly FIIs/FPIs/QFIs can now invest up to a sectoral limit of 74%, with certain conditions.
While India feels the flexibilities shown by it in further opening up to foreign investments should be considered positively by the EU, it also expects some reciprocal measures by the 28-member bloc to address its concerns, especially on data privacy and market access in the services sector. However, there will be no binding commitments until India’s core concerns are addressed suitably, Mehta said. The BTIA negotiations cover boosting goods and services trade as well as investment.
India seeks a data secure status because the high compliance cost with EU’s data protection laws will hit small and medium enterprises (SMEs) of India and make them un-competitive.
Mehta said India will be betting for a trade facilitation agreement (TFA) in services at the World Trade Organisation — similar to the TFA in goods — that would focus on liberalised visa regime, long term visas for business community and freer movement of professionals for the greater benefit of both India and the world. India will pursue it vigorously in negotiations for the BTIA as well as Regional Comprehensive Economic Partnership. RCEP is a proposed FTA between the Asean members and the six states with which it has forged FTAs, including India.
India is keen on services, as they account for over a half of its GDP. The EU is India’s largest trade partner, accounting for close to 15% of trade in both goods and services. It is a major market for Indian textiles, garments, pharmaceuticals, gems and jewellery and IT. The EU is also the largest source of FDI inflows to India, accounting for over one-fourth of the total. However, India ranks only ninth among the EU’s top trade partners, making up for just about 2% of its total merchandise goods in 2014.
BTIA talks were to be revived last year, but the EU’s surprise ban on 700 products of GVK shocked India, which then called off the negotiations. Prior to that, the negotiations centred around India’s demand for.
The EU is interested in further liberalisation of FDI in multi-brand retail and insurance, and closed sectors like accountancy and legal services. The underutilised private banking space in India is another draw. India’s intellectual property regime (IPR), which is unlikely to allow ever-greening of patents, remains a concern for European pharma majors. Moreover, the EU has been seeking a cut in the high import duties on assembled vehicles and wines and spirits. In case of assembled vehicles, the import duties remain in the range of 60-75%.
The Cabinet today approved conversion of MUDRA Ltd, an NBFC, into MUDRA Bank and also setting up of a Credit Guarantee Fund for loans disbursed under the Pradhan Mantri Micro Units Development Refinance Agency (MUDRA) Yojana.
Prime Minister Narendra Modi cleared creation of a Credit Guarantee Fund for MUDRA loans and to convert MUDRA Ltd into MUDRA Small Industries Development Bank of India (SIDBI) Bank as a wholly owned subsidiary of SIDBI, an official statement said.
“The MUDRA (SIDBI) Bank will undertake refinance operations and provide support services with focus on portal management; data analysis etc apart from any other activity entrusted or advised by Government of India,” it said.
The Credit Guarantee Fund is expected to guarantee more than Rs 1 lakh crore worth of loans to micro and small units in the first instance, it said, adding it will help in reducing risk taken by banks and financial institutions in case of default under the scheme.
A Credit Guarantee Fund for MUDRA Units (CGFMU) for guaranteeing loans – sanctioned under the scheme with effect from April 8, 2015 – will be set up.
The National Credit Guarantee Trustee Company Ltd (NCGTC Ltd), a wholly-owned company of Government of India, constituted under the Companies Act to manage and operate various credit guarantee funds, shall be the Trustee of the Fund, it said.
The guarantee would be provided based on a portfolio basis to a maximum extent of 50 per cent of amount in default in the portfolio.
Three products available under the PM MUDRA Yojana are Shishu, Kishor and Tarun to signify the stage of growth and funding needs of the beneficiary micro unit or entrepreneur.
Shishu covers loans up to Rs 50,000 while Kishor covers above Rs 50,000 and up to Rs 5 lakh. Tarun category provides loans of above Rs 5 lakh and up to Rs 10 lakh.
MUDRA Bank and a Credit Guarantee Fund was proposed to be set up with a refinance corpus of Rs 20,000 crore and a corpus of Rs 3,000 crore respectively in the Budget 2015-16.
As a precursor to the launch of the Pradhan Mantri MUDRA Yojana (PMMY) in April 2015, MUDRA Ltd was set up as a corporate subsidiary of SIDBI in March 2015.
The RBI has allocated Rs 20,000 crore and the first tranche of Rs 5,000 crore has been received by MUDRA as refinance.
If you missed your 120 days ITR-V verification deadline, there is good news. The income tax department has extended the verification deadline till 31st January.
If you missed your 120 days ITR-V verification deadline, there is good news. The income tax department has extended the verification deadline till 31st January.
Although it has not been officially notified yet, taxpayers have been receiving this information via email from the I-T department. However, you won’t be able to e-verify. Like old times, will have to physically mail the signed ITR V to CPC Bangalore.
“The electronic verification option gets switched-off automatically after 120 days of the taxpayer filing the return. However, the extended deadline to physically submit the ITR-V is open for all,” says Archit Gupta, founder and CEO, Cleartax.in. The 120 days countdown begins from the date the taxpayer submits their income tax returns forms.
The tax department had extended the filing deadline to September 7 this years. So, people who had filed on the last date still have a window of one day to e-verify. Post that you too will have to mail the ITR-V. The last date to do so will still remain 31st January.
Many individuals who, who had e-verified their return using Aadhar or Net banking, are receiving reminder letters from the CPC at Bangalore to physically send their ITR-V acknowledgement forms on or before the 31st of January, 2015.
“Those trying to e-verify their return once again with reference to the above are getting the message “No returns pending for e-verification” when they try to do so,” says Varun Advani, COO, makemyreturns.com. CAs advice them to re-send their ITR-Vs physically to the department before the deadline to aviod any further problems.
At least Rs 14,680 crore of funds have been raised in sector so far in current investment cycle.
Foreign investors’ interest in Indian real estate is on the rise after almost five years, India-specific fundraisings indicate.
The cycle started gaining momentum just before the 2014 general elections and at least $2.2 billion (Rs 14,680 crore) of funds have been raised so far in the current investment cycle, indicating an improvement in foreign investors’ confidence in Indian real estate, said consultancy firm JLL India. “During the pre-GFC (global financial crisis) phase, 82% of funds got raised in US dollar.
This reduced to 57% in post-GFC phase when micro-market understanding was required more than banking on the macro-economy,” said Shobit Agarwal, managing director of capital markets at JLL India. “Interestingly, the contribution, 2014-onwards, has increased considerably to 70% – hinting that the positivity is here to stay for some time.”
Recent easing of foreign direct investments rules is expected to bring in more capital into the property sector. PE funds are also looking to leverage on this rising interest among foreign investors.
“We believe this is an opportune time to invest in Indian real estate, with rigorous risk management and strong asset management.
Offshore funds are showing interest in Indian real estate and there is lot of interest from FDI funds back in Indian real estate,” said Rubi Arya, chief executive of Milestone Capital Advisors. “We are planning to leverage further on our structured debt and commercial platform to raise money from offshore funds.”
According to Arya, FDI funds are looking to invest in pre-leased commercial assets, create strategic-level partnerships with reputed developers mainly through equity deals and make structured debt investments in residential projects.
India-specific cumulative fundraising attained its peak in the pre-GFC period. During this period between 2005 and 2008, there were 50 such funds that raised $16 billion in total. However, post-GFC, only 29 funds got raised in five years, with cumulative fundraising of $3.9 billion, said the JLL India report.
Not only has the volume of investment increased, but there has also been an increase in the average investment size from $134 million to $184 million in the current cycle that started in 2014.
The national exchequer received Rs 2,428.4 crore in payments from disclosures made during a three-month long compliance window under the Black Money (Undisclosed Foreign Income and Assets) and Imposition of Tax Act last year, bolstering tax revenue collections.
This is 97 per cent of the amount due from 644 declarations made from holders of black money stashed overseas by December 31, the last day of payment.
The amount included tax and penalty on the declarations made under the three-month compliance window that ended September 30 last year on total disclosures of Rs 4,147 crore.
This added to government’s gross tax revenue collection, which touched 66 per cent of Budget Estimates for the full financial year till December, a sharp uptick from 52.4 per cent till November.
Even as government targets a fiscal deficit of 3.9 per cent during 2015-16, it is expecting a shortfall of Rs 30,000-40,000 crore in direct taxes this financial year. Besides, lower than expected nominal GDP (gross domestic product) growth at close to eight per cent will exert further pressure on the fiscal deficit target.
“The amount collected under black money disclosure is Rs 2,428 crores (97 per cent of amount due) by December 31, which was the last date of payment. The total tax revenue collected up to December this year is Rs 9.5 lakh crore, 66 per cent of Budget Estimates,” said Revenue Secretary Hasmukh Adhia in a tweet.
The Union Cabinet on Wednesday approved the setting up of two credit guarantee funds to facilitate loans to micro and small entrepreneurs through MUDRA (Micro Units Development Refinance Agency) and the Stand Up India scheme. The corpus of credit guarantee fund for MUDRA will be Rs 3,000 crore and for Stand Up India Rs 5,000 crore. Finance minister Arun Jaitley said these schemes will improve funding to micro and small entrepreneurs and help boost economic activity.
Under MUDRA, the agency refinances loans up to Rs 10 lakh to micro and small units, and has so far disbursed loans worth Rs 72,000 crore to 1.73 crore beneficiaries. MUDRA was launched in April last year.
The Stand Up India scheme seeks to provide refinance window through Small Industries Development Bank of India (SIDBI) with an initial amount of Rs 10,000 crore.
The Stand Up India scheme is distinct as its objective is to help entrepreneurs from scheduled castes, scheduled tribes and women entrepreneurs.
Each branch of all banks, including private banks, will fund at least two entrepreneurs in the SC/ST category and one in women category, Jaitley said. The government aims to refinance loans of 2.5 lakh borrowers in 36 months under Stand Up India. The credit guarantee fee under both the funds will be paid by the banks and not passed on to the borrowers, banking secretary Anjuly Chib Duggal said.
She said the National Credit Guarantee Trustee Company Ltd (NCGTC) would be the trustee for both the credit guarantee funds of MUDRA as well as Stand Up India.
The Stand Up India scheme will handhold borrowers both at the pre-loan stage and during operations. “This would include increasing their familiarity with factoring services, registration with online platforms and e-market places as well as sessions on best practices and problem solving,” the government said in a statement. Under the scheme, the margin money would be up to 25 per cent, while remaining would be funded by the bank.
The credit guarantee fund for MUDRA is expected to guarantee more than Rs 1 lakh crore worth of loans to micro and small units in the first instance, the government said. It will help in reducing risk taken by banks and financial institutions in case of default under the scheme. The government will provide guarantee on portfolio basis to maximum extent of 50 per cent of the amount in default in portfolio.
The Cabinet also approved conversion of MUDRA Ltd, currently a non banking finance company, into a bank called MUDRA-SIDBI Bank, a wholly owned subsidiary of SIDBI.