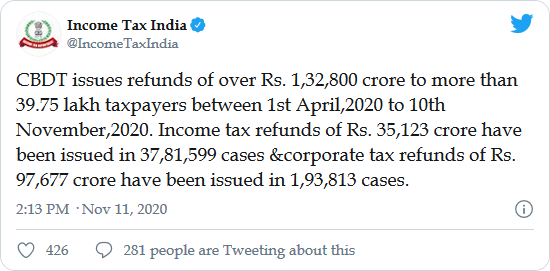Amid a severe hit to the Indian economy by the Covid pandemic in the past eight months, the country’s foreign exchange reserves increased by more than $100 billion since the Covid-induced lockdown was enforced in March-end.
From $469.9 billion in the week ended March 20, 2020, the forex reserves jumped by $102.8 billion to a lifetime high of $572.7 billion in the week ended November 13, 2020, according to the data released by the Reserve Bank of India.
Importantly, the reserves grew by $4.277 billion from the week ended November 6, 2020. The jump was on account of Foreign Currency Assets (FCA), a major component of the country’s reserves, that increased by $5.526 billion to $530.2 billion from $524.7 billion in the preceding week.
However, the gold reserves reduced by $1.233 billion from $37.587 billion to $36.354 billion in the week. On the other hand, the special drawing rights with the International Monetary Fund (IMF) were unchanged from the preceding week at $1.488 billion, the data showed.
Foreign portfolio investors (FPI) have invested Rs 49,553 crore in Indian markets in November so far on the back of high liquidity along with improving global indicators and clarity after the US presidential elections, PTI reported.
The investment stood at Rs 44,378 crore in equities and Rs 5,175 crore in the debt segment between November 3-20 while FPI’s October investment was Rs 22,033 crore.
On the other hand, India saw its highest ever Foreign Direct Investment (FDI) during the first five months April-August of the current financial year. The total inflow was $35.73 billion, according to the Ministry of Commerce and Industry that was also 13 per cent up from the year-ago period.
Meanwhile, bank credit grew 5.67 per cent to Rs 104.04 lakh crore in the fortnight ended November 6, 2020, according to the RBI data.
The bank credit stood at Rs 98.46 lakh crore in the fortnight ended November 8, 2019. Moreover, deposits had jumped 10.63 per cent to Rs 143.80 lakh crore from Rs 129.98 lakh crore during the said period.
This include Personal income tax (PIT) refunds amounting to Rs 35,123 crore and corporate tax refunds amounting to Rs 97,677 crore during this period.
The Income Tax department has issuedrefundsworth over Rs1.32lakh crore to over 39 lakhtaxpayers so far this fiscal.
This include Personal income tax (PIT) refunds amounting to Rs 35,123 crore and corporate tax refunds amounting to Rs 97,677 crore during this period.
“CBDT issues refunds of over Rs 1,32,800 crore to to more than 39.75 lakh taxpayers between April 1,2020 to November 10,2020.
Income tax refunds of Rs 35,123 crore have been issued in 37,81,599 cases and corporate tax refunds of Rs 97,677 crore have been issued in 1,93,813 cases,” the I- T department tweeted.
For improving the ease of doing business in India and to reduce the cost of compliance, RBI has made a review of requirements of submission of various forms and reports under FEMA and has decided to discontinue submission of 17 such returns/ reports with immediate effect.
Discontinuation of Returns/ Reports under Foreign Exchange Management Act, 1999
1. The attention of Authorised Persons is invited to the Master Direction- Reporting under Foreign Exchange Management Act, 1999 dated January 01, 2016, as amended from time to time, and other reporting related instructions issued by the Reserve Bank of India.
2. With a view to improve the ease of doing business and reduce the cost of compliance, the existing forms and reports prescribed under FEMA, 1999, were reviewed by the Reserve Bank. Accordingly, it has been decided to discontinue the 17 returns/ reports as listed in the Annexure with immediate effect.
3. The Master Direction- Reporting under Foreign Exchange Management Act, 1999 dated January 01, 2016, shall accordingly be updated to reflect the above changes. AD banks may bring the contents of this circular to the notice of their constituents.
4. The directions contained in this circular have been issued under Section 10(4) and 11(2) of the Foreign Exchange Management Act, 1999 (42 of 1999) and are without prejudice to permissions/ approvals, if any, required under any other law.
List of Discontinued Reports
Sl. No.
Name of Report
Reporting Entity
Frequency
1
Category-wise transaction where the amount exceeds USD 5000 per transaction
AD Category-II
Monthly
2
Category-wise, transaction-wise statement where the amount exceeds USD 25,000 per transaction
AD Category- II
Monthly
3
Statement of Purchase transactions of USD 10,000 and above (including transactions of their franchisees)
FFMCs and AD Category- II
Monthly
4
Extension of Liaison Offices (LOs)
AD Category-I banks
As and when extension is granted
5
Extension of Project Offices (POs)
AD Category-I banks
As and when extension is granted
6
FII/FPI daily: Daily inflow/outflow of foreign fund on account of investment by FPIs
AD banks
Daily
7
FII/FPI Return (Monthly): Data relating to actual inflow/ outflow of remittances on account of investments by Foreign Institutional Investors (FIIs) in the Indian Capital market
AD Category-I banks
Monthly
8
FVCI reporting: Inflows/outflows of remittances on account of investments by Foreign Venture Capital Investor (FVCIs) and Market value of Investments made by FVCIs
AD Category-I banks/Custodian banks
Monthly
9
Reporting of Inflow/ Outflow details in respect of Mutual Fund by Asset Management Companies
Asset Management Companies
Quarterly
10
Market value of FII Investment in India on fortnightly basis
AD Category-I banks
Fortnightly
11
Market value of FII Investment in India on Monthly basis
AD Category-I banks
Monthly
12
FII holdings as percentage of floating stock
AD Category-I banks
Monthly
13
Form DRR for Issue/ transfer of sponsored/ unsponsored Depository Receipts (DRs)-Hardcopy**
Custodian
At the time of issue/transfer of depository receipts
14
ADR/ GDR Movement Report- two way fungibility
AD Category-I banks
Monthly
15
Repatriation of Sales proceeds of underlying shares represented by FCCBs/ GDRs/ ADRs
Custodian
Monthly
16
GDR/ ADR underlying shares issued, re deposited and released monthly reporting
Custodian
Monthly
17
Monitoring of disinvestments by Overseas Corporate Bodies
AD banks
Monthly
** Please note that it is only the hardcopy filing of form DRR that has been discontinued. The domestic custodian may continue to report the form DRR on FIRMS application in terms of Regulation 4(5) of FEM (Mode of Payment and Reporting of Non-Debt Instruments) Regulations, 2019.
– The rate of interest as of February 29 that will be used to calculate the interest differential will not include any penalties or any penal rate of interest applied to the loan. – The package will be available for eligible borrowers irrespective of whether they have availed or partially availed or not availed the moratorium on repayment announced by RBI
Borrowers will not need to apply for the interest-on-interest waiver scheme for the six-month loan moratorium, the finance ministry has said, asking lenders to credit ex-gratia relief amount into the accounts of those eligible.
The ministry late Tuesday issued a set of 20 clarifications on the scheme in form of frequently asked questions or FAQs
The lending institutions will draw up a list of their borrowers eligible under the criteria laid down by the government and refund the difference between the compound interest and simple interest paid between March 1 and August 31.
The benefit is available to all eligible borrowers including those who did not opt for moratorium. The lenders can seek a refund from the government that will foot the bill.
According to a Crisil report, 75% of borrowers will be covered under the scheme, which likely to cost the government Rs 7,500 crore.
The scheme is not applicable to accounts classified as non-performing assets (NPAs) at the end of February as also loans against fixed deposits, bonds, shares or other interest-bearing instruments and loans given for investment in financial assets such as shares and debentures.
While the scheme includes any outstanding amount on credit cards, relief will not be paid to those credit card holders with a card balance in ‘credit’, as per the FAQs.
The Rs 2 crore limit is based on the borrower’s aggregate loans across lending institutions as on February 29.
Non-fund based limits such as letters of credit and guarantees would not count towards the Rs 2 crore limit.
For calculating the interest differential, lending institutions will consider the contracted interest rate on loans as of February 29. For zero interest loans, the lender’s base rate should be used while for credit card dues, the weighted average lending rate for the transactions between March 1 and August 31 should be applied, the ministry said.
On October 23, the government had announced the scheme for ex-gratia payment of difference between compound interest and simple interest for six months (March 1, 2020 to August 31, 2020) to borrowers in specified loan accounts.
The move was in response to the Supreme Court (SC) seeking clarity on the waiver of ‘interest on interest’ in the ongoing case filed for relief of borrowers availing the moratorium on loan repayments granted by the Reserve Bank of India (RBI).
The case was filed on behalf of borrowers, seeking relief from payment of the interest accruing on the monthly instalments that were paused for six months.
The SC has set the next hearing for November 2 to assess the implementation of the scheme, which the government said would be completed by November 5.
“Banks will not have to go through individual borrowers, only the categories need to be selected and the scheme needs to be applied. It will all be system-based, there is not much manual intervention required,” said Mukesh Kumar Jain, former managing director and CEO of the erstwhile Oriental Bank of Commerce.
The FAQs said banks would use the information they had along with information from credit bureaus to assess a borrower’s aggregate loans. Jain said this should not be an issue as, “Normally, loans up to Rs 2 crore are taken from a single bank since it is a relatively small amount”.
The Income Tax department on Friday said it has issued refunds worth Rs 88,652 crore to over 24 lakh taxpayers so far this fiscal.
This include personal income tax (PIT) refunds amounting to Rs 28,180 crore issued to over 23.05 lakh taxpayers and corporate tax refunds amounting to Rs 60,472 crore to over 1.58 lakh taxpayers during this period.
“CBDT has, so far, issued refunds of over Rs 88,652 crore to more than 24.64 lakh taxpayers from 1st April, 2020 onwards.
Income tax refunds of Rs 28,180 crore have been issued in 23,05,726 cases & corporate tax refunds of Rs 60,472 crore have been issued in 1,58,280 cases,” the Income Tax department tweeted.
The Central Board of Direct Taxes (CBDT) is the apex decision-making body in direct tax matters, administers personal income tax and corporate tax.
The government has emphasized on providing tax related services to taxpayers without any hassles during COVID-19 pandemic and to that end has been clearing up pending tax refunds.
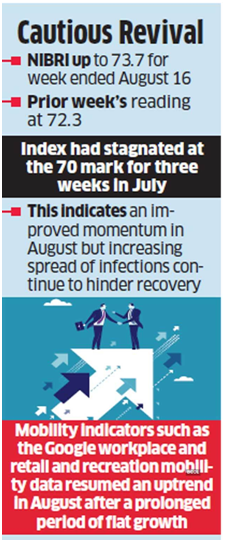
The Nomura India Business Resumption Index inched up to 73.7 for the week ending August 16, over the previous week’s reading of 72.3. This came after the NIBRI, a weekly tracker of the pace at which economic activity normalises, stagnated at the 70-mark for three weeks through July.
The economy sustained an increasing pace of recovery through August so far after a prolonged period of plateauing trends in July, according to a Nomura note on Monday.
The Nomura India Business Resumption Index (NIBRI) inched up to 73.7 for the week ending August 16, over the previous week’s reading of 72.3.
This came after the NIBRI, a weekly tracker of the pace at which economic activity normalises, stagnated at the 70 mark for three weeks through July.
While this indicated an improved momentum in August over the moderation in July, the rising spread of infections continued to hinder recovery.
“Nevertheless, the recovery is uneven, and the risk of reversal in momentum from a second wave of COVID-19 cases joining a ‘rolling wave’ in traditional safer states (in the south and the east) remains high,” the note said.
Mobility indicators such as the Google workplace and retail and recreation mobility data resumed an uptrend in August after a prolonged period of flat growth, Nomura said.
However, this was still materially below pre-pandemic levels, it added.
There was a steady pick up in the labour participation rate 42.2% as against 40.6% in the previous week.
On the other hand, the unemployment rate showed a steady uptrend rising to 9.1% compared to the 8.2% recorded last week, which grew from 7.2% reported the week before that.
The deterioration was spread both over rural and urban areas, the note said.
Power demand also showed a steady trend albeit in the opposite direction with a steep weekly contraction of 6.4% over the 0.8% contraction of the week earlier, it said.
Faceless e-assessment will have no human interface and it’s purpose will be to eliminate instances of “undesirable practices” on the part of tax officials.
The Central Board of Direct Taxes (CBDT) on Thursday revised the ‘E-assessment Scheme, 2019’ notified on September 12, 2019. The Government notified that now, the e-Assessment scheme shall be called Faceless Assessment.
Now, the National e-Assessment Centre shall intimate the assessee for the conduct of faceless assessment in case wherein notice has been issued by AO.
The Board has also extended its scope to cover best judgment assessments.
E-Assessment was a roadway towards a paperless, faceless assessment stripping away at bureaucratic layers. E-Assessment was earlier tried and tested by the Income-tax Department, before going forth with the E-Assessment Scheme, 2019.
The Board notified that in the notification dated September 12, 2019, in the opening portion, for the word “E-assessment”, the words “Faceless Assessment” shall be substituted. The Board notified the procedure for the faceless assessment wherein the National e-Assessment Centre shall serve a notice on the assessee under sub-section (2) of section 143, specifying the issues for selection of his case for assessment.
Promoting a transparent and fair tax regime, Prime Minister Narendra Modi unveiled ‘taxpayers’ charter’, enshrining rights of assesses in a statute under the Income tax law. With the launch of ‘Transparent Taxation — Honoring the Honest’ platform, Modi also unveiled faceless appeal and expanded the scope of faceless assessment, eliminating physical interface between taxpayers and tax authority.
Step wise process for Faceless Assessment, scope extended to cover best judgement assessment:
Introduction
The Central Board of Direct Taxes (CBDT) has revised the ‘E-assessment Scheme, 2019’ notified on September 12, 2019. Now, e-assessment scheme shall be called Faceless Assessment.
The National e-Assessment Centre shall intimate the assessee for conduct of faceless assessment in case wherein notice has been issued by AO. The Board has also extended its scope to cover best judgment assessments.
What was the E-assessment Scheme, 2019?
Finance Minister Nirmala Sitharaman had announced the e-assessment scheme in her Budget speech on July 5, 2019, which was subsequently inaugurated on October 7, 2019.
This was aimed at moving to faceless scrutiny and elimination of human interface in assessment proceedings. The scheme was set to bring in a “paradigm shift” in taxation by eliminating human interface in the income tax assessment system.
The Ministry of Finance vide Central Board of Direct Taxes (CBDT) notification No 61 & 62 dated 12th September 2019 has respectively notified the E- assessment Scheme 2019 & gave directions for its implementation.
E-assessment Scheme, 2019 to be now called as “Faceless Assessment”
Step wise process for Faceless Assessment
By the Notification issued by CBDT on 13th August, 2020, “E-assessment” will be now called as “Faceless Assessment”. Faceless assessment shall be made as per the following procedure:-
Step 1 – Issue of Notice on Assessee
National e-Assessment Centre shall serve a notice on the assessee under section 143(2), specifying the issues for selection of his case for assessment
Assessee may, within 15 days from the date of receipt of notice, file his response to the National e-assessment Centre
Step 2 – Case to be assigned to Assessment Unit
1.National e-assessment Centre shall assign the case selected for the purposes of e-assessment to a specific assessment unit in any one Regional e-assessment Centre through an automated allocation system
2. Where a case is assigned to the assessment unit, it may make a request to the National e-assessment Centre for:-
a. obtaining such further information, documents or evidence from the assesse or any other person
b. conducting of certain enquiry or verification by verification unit
c. seeking technical assistance from the technical unit
3. Where a request for obtaining further information, documents or evidence from the assessee or any other person has been made, the National e-assessment Centre shall issue appropriate notice or requisition to the assessee or any other person for obtaining the information, documents or evidence requisitioned by the assessment unit
4. Where a request for conducting of certain enquiry or verification by the verification unit has been made, the request shall be assigned by the National e-assessment Centre to a verification unit through an automated allocation system
5. Where a request for seeking technical assistance from the technical unit has been made, the request shall be assigned by the National e-assessment Centre to a technical unit in any one Regional e-assessment Centre through an automated allocation system
6. The assessment unit shall, after taking into account all the relevant material available on the record, make in writing, a draft assessment order either accepting the returned income of the assessee or modifying the returned income of the assessee, and send a copy of such order to the National e-assessment Centre with details of the penalty proceedings to be initiated therein, if any.
Step 3 – Draft Assessment Order
1.National e-assessment Centre shall examine the draft assessment order in accordance with the risk management strategy specified by the Board, including by way of an automated examination tool, whereupon it may decide to:-
a. finalise the assessment as per the draft assessment order and serve a copy of such order and notice for initiating penalty proceedings, if any, to the assessee, alongwith the demand notice, specifying the sum payable by, or refund of any amount due to, the assessee on the basis of such assessment, or
b. provide an opportunity to the assessee, in case a modification is proposed, by serving a notice calling upon him to show cause as to why the assessment should not be completed as per the draft assessment order, or
c. assign the draft assessment order to a review unit in any one Regional e-assessment Centre, through an automated allocation system, for conducting review of such order;
2. Review unit shall conduct review of the draft assessment order, referred to it by the National e-assessment Centre whereupon it may decide to:-
a. agree with the draft assessment order and intimate the National e-assessment Centre about such agreement; or
b. suggest such modification, as it may deem fit, to the draft assessment order and send its suggestions to the National e-assessment Centre;
3. National e-assessment Centre shall, upon receiving concurrence of the review unit, follow the procedure laid down in sub point (a) or (b) of point (1), as the case may be
4. National e-assessment Centre shall, upon receiving modification suggestions from the review unit, communicate the same to the Assessment unit
5. Assessment unit shall, after considering the modifications suggested by the Review unit, send the final draft assessment order to the National e-assessment Centre
6. The National e-assessment Centre shall, upon receiving final draft assessment order, follow the procedure laid down in sub point (a) or (b) of point (1),as the case may be
7. The assessee may, in a case where show-cause notice has been served upon him, furnish his response to the National e-assessment Centre on or before the date and time specified in the notice
8. The National e-assessment Centre shall,-
a. in a case where no response to the show-cause notice is received, finalise the assessment as per the draft assessment order; or
b. in any other case, send the response received from the assessee to the assessment unit;
9. The assessment unit shall, after taking into account the response furnished by the assessee, make a revised draft assessment order and send it to the National e-assessment Centre
Step 4 – Final Order and Completion of Assessment
The National e-assessment Centre shall, upon receiving the revised draft assessment order:-
a. in case no modification prejudicial to the interest of the assessee is proposed with reference to the draft assessment order, finalise the assessment or
b. in case a modification prejudicial to the interest of the assessee is proposed with reference to the draft assessment order, provide an opportunity to the assessee
c. the response furnished by the assessee shall be dealt with as per the procedure laid down in point 7, 8, 9 of Step 3
2. The National e-assessment Centre shall, after completion of assessment, transfer all the electronic records of the case to the Assessing Officer having jurisdiction over such case for:
a. imposition of penalty
b. collection and recovery of demand
c. rectification of mistake;
d. giving effect to appellate orders
e. submission of remand report, or any other report to be furnished, or any representation to be made, or any record to be produced before the Commissioner (Appeals), Appellate Tribunal or Courts, as the case may be
f. proposal seeking sanction for launch of prosecution and filing of complaint before the Court;
3. National e-assessment Centre may at any stage of the assessment, if considered necessary, transfer the case to the Assessing Officer having jurisdiction over such case.
Faceless assessment facility was extended to the entire country on 13th August, 2020, ending territorial jurisdiction and individual discretion, where an officer was the whole and sole to the assessee. Scrutiny will be allotted on a random basis. Assessment of a taxpayer in Delhi could well be carried by an officer sitting in Pune. It will put an end to needless litigation. Best Judgements Assessments under Section 144 will be also now covered under Faceless Assessment.
What is the meaning of Best Judgement Assessment?
The Best Judgment Assessment is a procedure under the Income Tax Act to comply with the principles of natural justice. Vide Section 144 of the Income Tax Act, 1961 the Assessing Officer is under an obligation to make an assessment of the total income or less to the best of his judgment in the following cases:
If the person fails to file a return required under section 139(1) and he has not filed a revised return.
If any person fails to comply with all the terms and conditions stipulated under a notice under section 142 or fails to comply with the directions requiring him to get his accounts audited in terms of section 142(2A).
If any person, after having filed a return fails to comply with all the terms of a notice under section 143(2) requiring his presence or production of evidence and documents; or
If the Assessing officer is not satisfied about the correctness and the completion of the accounts of the assessee if no method of accounting has been regularly employed by the assessee.
While Faceless Assessment and Taxpayers Charter came in force already, Faceless Appeal will be available from September 25, 2020. Under the Faceless Appeals system introduced by the government, appeals will be randomly allotted to any officer across the country and the identity of the officer deciding the appeal will remain unknown. The decisions will be team-based.

 Amid a severe hit to the Indian economy by the Covid pandemic in the past eight months, the country’s foreign exchange reserves increased by more than $100 billion since the Covid-induced lockdown was enforced in March-end.