The Micro, Small and Medium Enterprises Development (Amendment) Bill, 2026 Passed by Parliament: A New Era for India’s MSME Sector

A New Era for India’s MSME Sector

In a significant legislative development, the Indian Parliament has passed the Micro, Small and Medium Enterprises Development (Amendment) Bill, 2026, marking one of the most important reforms to the MSME ecosystem since the enactment of the MSMED Act, 2006. The Bill was passed by the Rajya Sabha on 3 August 2026 and subsequently approved by the Lok Sabha on 7 August 2026.

The amendment seeks to modernize the legal framework governing MSMEs, improve ease of doing business, address the chronic issue of delayed payments, strengthen dispute resolution mechanisms, and promote digital governance. Given that MSMEs contribute significantly to employment, manufacturing, exports, and economic growth, the reform is expected to have far-reaching implications for India’s business landscape.

Why the amendment was needed

The MSMED Act was enacted in 2006, and over the past two decades India’s business environment has undergone substantial transformation due to technological advancements, digitization, evolving market dynamics, and growing integration with global supply chains. The government recognized the need to update the Act to reflect these changes and provide stronger institutional support to millions of enterprises across the country.

One of the most pressing challenges faced by MSMEs has been the issue of delayed payments from buyers, which often creates severe liquidity constraints. The new Bill addresses this challenge through stricter timelines, enhanced enforcement provisions, and modern dispute resolution mechanisms.

Key Features of the Amendment Bill

  1. Revised MSME Classification Framework

The Bill empowers the Central Government to classify enterprises as MSMEs based on two criteria:

  • Investment in plant and machinery or equipment
  • Annual turnover

The thresholds will be notified by the government from time to time, providing flexibility to adapt to changing economic realities.

  1. Permanent Digital Registration Platform

The amendment institutionalizes the Udyam Registration Portal as a free, digital, and voluntary registration platform for MSMEs. State governments may also establish linked digital platforms to facilitate registration and access to government benefits.

This move is expected to promote formalization and simplify compliance for businesses across the country.

  1. Strengthening Delayed Payment Resolution

Perhaps the most impactful reform is the strengthening of mechanisms to address delayed payments.

The Bill introduces:

  • Online Dispute Resolution (ODR) systems.
  • Faster mediation and arbitration processes.
  • Stronger enforcement of awards and settlements.

These measures are intended to reduce litigation costs and improve access to justice for small businesses.

  1. Mandatory Timelines for Dispute Resolution

The amendment provides specific timelines for dispute resolution:

  • Mediation must be completed within 90 days from the date of first appearance.
  • If mediation fails, the matter must be referred to arbitration within 30 days.
  • The arbitral award must be delivered within 90 days after completion of pleadings.

Such timelines can significantly reduce delays that have historically burdened MSMEs.

  1. Enhanced Protection During Appeals

The Bill empowers courts to direct payment of at least 50% of the awarded amount to MSME suppliers when an application challenging the award remains pending for more than six months.

This provision is expected to improve liquidity and discourage frivolous delays by buyers.

  1. Recovery of Awards as Arrears of Land Revenue

To ensure effective enforcement, mediated settlements and arbitral awards can be recovered as arrears of land revenue through the District Collector, Deputy Commissioner, or other notified authorities where the buyer’s assets are located.

This provision strengthens the ability of MSMEs to realize their dues.

  1. Mandatory Use of TReDS by CPSEs

The Bill makes it mandatory for Central Public Sector Enterprises (CPSEs) to route settlement of MSME invoices through the Trade Receivables Discounting System (TReDS) platform. Governments may also extend similar requirements to other public sector entities.

This measure can improve cash flow and provide faster access to working capital for MSMEs.

  1. Rationalization of Compliance Framework

The amendment also seeks to replace certain conviction-based penalties with graded civil penalties and administrative measures, thereby reducing regulatory burdens and promoting a more business-friendly environment.

Expected Impact on the MSME Sector

The amendment is expected to produce several positive outcomes:

Improved Cash Flow

Mandatory TReDS adoption and stronger payment enforcement can significantly reduce payment delays and improve working capital availability.

Faster Dispute Resolution

Defined mediation and arbitration timelines are likely to shorten dispute settlement cycles.

Greater Digital Adoption

The strengthened Udyam registration ecosystem and digital dispute resolution mechanisms support the government’s vision of digital governance.

Enhanced Investor Confidence

Clear legal protections and stronger enforcement mechanisms can encourage entrepreneurship and investment in the MSME sector.

Better Ease of Doing Business

Reduced compliance burdens and streamlined procedures can help MSMEs focus more on growth and innovation.

Challenges Ahead

While the amendments are promising, effective implementation will be critical. Success will depend on:

  • Adequate digital infrastructure.
  • Capacity building of Facilitation Councils.
  • Awareness among MSMEs about their rights and remedies.
  • Efficient coordination between central and state authorities.
  • Timely enforcement of dispute resolution timelines.

Without strong execution, the intended benefits may not fully materialize.

Conclusion

The Micro, Small and Medium Enterprises Development (Amendment) Bill, 2026 represents a landmark reform aimed at strengthening the backbone of India’s economy. By addressing delayed payments, promoting digital governance, streamlining dispute resolution, and enhancing liquidity for small businesses, the legislation seeks to create a more supportive and growth-oriented environment for MSMEs.

As India continues its journey toward becoming a global economic powerhouse, the successful implementation of these reforms could play a crucial role in unlocking the full potential of the MSME sector, fostering innovation, employment generation, and sustainable economic growth.

The Micro, Small and Medium Enterprises Development (Amendment) Bill, 2026 passed by Parliament
 

GST 2.0: What changed at the recent GST Council meeting – rates, processes and what it means

GST Council, has recommended to reduce / waive the interest/ late fee for delayed filing of GSTR 3B by small taxpayers (having turnover upto Rs. 5 crores) for the tax period from July 2017 to July 2020
The GST Council has announced major rate cuts and compliance reforms in its September 2025 meeting. Highlights of new GST slabs, effective dates, process changes, and how businesses should prepare.

India’s GST system just received its biggest shake-up since rollout: the GST Council approved a major rate rationalisation (moving to a much simpler slab structure), together with a package of taxpayer-friendly process reforms. The changes – aimed at reducing complexity, lowering prices for many everyday goods, and speeding up compliance/refunds for businesses – are to be implemented from 22 September 2025 (with a few exceptions and phased rollouts). Here’s a clear, practical, and source-backed breakdown of what happened, why it matters, and what businesses and consumers should expect next.


Main Highlights

  • Two main GST slabs: 5% (merit/essential) and 18% (standard) — the 12% and 28% slabs are being collapsed into these. A special de-merit 40% rate is proposed for a small set of luxury/sin goods (tobacco, very high-end vehicles, etc.).


  • Implementation date: Most changes effective 22 Sept 2025 (Navratri start). Tobacco/pan masala items will have separate timing. Some elements may be phased to manage compensation fund impacts.


  • Process reforms: Faster/automated registration for low-risk businesses, pre-filled returns, auto/refund acceleration, risk-based provisional refunds for exporters and a timeline to operationalise many tech changes.


  • Anti-profiteering approach: legal anti-profiteering machinery (Section 171) hasn’t been reinstated in an aggressive form — the government is asking industry to pass on benefits while monitoring and states are pushing for safeguards. Expect guidance from tax authorities.


What exactly changed – the rate map (summary)

The Council rationalised slabs to simplify compliance and broaden the “common man” gains.

  • 5% slab — Will cover a large set of essentials, many medicines/healthcare inputs, basic food items and several household staples and smaller consumer items previously at 12%/18%. (Examples reported: roti, many edible goods, certain medicines and diagnostic kits, small household appliances in some categories).


  •  8% slab — The standard rate now for most manufactured goods and many services previously at 18%/28%/12% where reclassification makes sense (e.g., many auto components, some consumer durables moved to 18%).


  • 40% de-merit slab — A higher, selective rate for luxury and sin goods (tobacco products, very high-end cars, other items identified by the Council). These are explicitly carved out to preserve revenue and to tax dis-incentivise harmful/very high-end consumption.


Implementation mechanics & phasing

  • Effective date: The Council recommended implementation from 22 September 2025 for most goods/services. Tobacco and tobacco-related items will have separate treatment (different effective date to be notified) because of compensation cess and administrative considerations. Some elements (especially where compensation cess/compensation fund is concerned) may be phased to smooth state receipts.


  • Why phased? Several states flagged potential revenue loss concerns; the Council stressed consensus but also acknowledged fiscal impacts and decided to manage timing and the compensation cess account accordingly. Expect circulars from CBIC explaining exact implementation steps (tariff notifications, HSN crosswalks, valuation/credit rules). 


Process reforms (big ticket operational changes)

The meeting wasn’t just about rates – there’s a parallel package to make compliance quicker and less painful:

  1. Automated/simplified registration for low-risk applicants (target: 3 days/automated approval for eligible applicants). This aims to cut onboarding friction for SMEs and startups.


  • Prefilled returns & auto refunds — prefilled return architecture and auto refunds (including provisional/90% provisional refunds for exporters based on risk evaluation for specific sectors) to speed liquidity to business. Rollouts/timelines were announced — many measures to be operationalised by October–November 2025.


  • Faster refund windows (seven-day targets for specific exporters/priority cases) and risk-based provisional mechanisms to reduce stuck refunds.


  • Tribunal and dispute reforms — strengthening appellate/ADR mechanisms (e.g., national benches for Advance Rulings) to improve consistency in rulings.

These process reforms are intended to complement rate rationalisation so taxpayers – especially MSMEs and exporters — face lower compliance cost and faster cash flows. 


Anti-profiteering and price transmission

  • The Council/officials have made it clear that industry is expected to pass benefits of lower GST to consumers. The strict anti-profiteering law (Section 171) hasn’t been robustly re-invoked as a new enforcement blitz, but states have insisted on safeguards and monitoring. Tax authorities and state governments will watch prices and may ask for evidence of benefit transmission; businesses should act cautiously and transparently. 

Practical tip for retailers/manufacturers: document the cost/repricing methodology, issue credit notes where appropriate and update pricing policies — this is both good business practice and a defensive step in case of state queries.


Sectoral winners and losers — who gains, who pays more

  • Likely beneficiaries (cheaper): FMCG staples, many food items, certain medicines & diagnostic reagents, entry-level autos and components, many household goods and some construction materials (cement, tiles — reported moves from 28→18% / 12→5% for specific items). These cuts will help consumer demand and reduce input costs for industries like housing and consumer durables. 


  • Likely paying more / targeted up-taxed: Very high-end cars, tobacco & pan masala, certain luxury goods moved into the 40% de-merit slab (aim: revenue neutrality and disincentive). 

Stakeholder notes: Auto dealers, consumer durables firms and textiles have broadly welcomed the move as demand stimulative; states with manufacturing-heavy revenue bases have flagged short-term revenue pain and asked for compensatory arrangements. 


How decisions were made (short explanation of the Council process)

  • The GST Council is a constitutional body (Article 279A) that makes recommendations on rates and other GST matters. Decisions are taken with a weighted voting mechanism (Centre has one-third weight, states two-thirds) and normally by a three-fourths weighted majority — but in practice the Council aims for consensus. The 56th meeting reported unanimous consensus on the package. 

What to watch next

  • Notifications from CBIC/CBIC circulars giving precise tariff/HSN crosswalks, valuation rules and timeline for phased items. (Those will be the legally binding documents.) 


  •  State responses about compensation/temporary support if they claim revenue shortfalls — any fiscal transfers or special measures will be announced in coming weeks.


  • Price monitoring: watch for state consumer affairs departments and tax authorities asking firms to show price transmission evidence.


Final take

This is a large, pro-consumer and pro-growth move designed to simplify GST’s complexity and spur demand ahead of the festive season — while also modernising the compliance stack (faster registration/refunds). It’s politically significant (broad consensus) and technically big — businesses should act fast to align systems, pricing and documentation. States’ fiscal positions will be the main political/implementation watchpoint, so expect more operational clarifications from CBIC in the coming days.


Ubharte Sitaare Fund: Rs 250-crore export-oriented fund for MSMEs launched

The initiative would play a catalytic role in contributing to the growth of the identified companies and would also have downstream benefits such as growth and diversification of India’s exports, impetus to brand India, and employment generation.

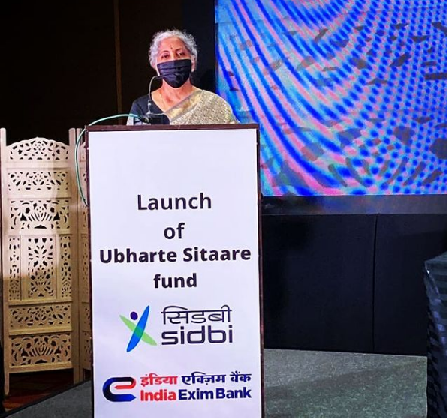
Union finance minister Nirmala Sitharaman on Saturday launched the Ubharte Sitaare Fund (USF) for export-oriented small and mid-sized companies and startups in Lucknow. Sitharaman had announced the fund in her Budget speech in 2020 in the backdrop of constraints faced by small and mid-sized companies in realising their export ambitions, stating that micro, small and medium enterprises (MSMEs) were important to keep the “wheels of the economy moving”.

The fund, jointly sponsored by Exim Bank and SIDBI, has a size of Rs 250 crore with a green shoe option of Rs 250 crore. The fund will invest by way of equity, and equity-like products, in export-oriented units, both in the manufacturing and services sectors.

Stating that the ambitious programme was to support the champion sectors, she said some developed countries like Germany have already tried this by identifying, supporting and hand-holding the champion sectors and giving them necessary technology and fund infusion. Ubharte Sitaare largely follows the same principal, she said, adding that induction of tech will itself bring a big difference to the small and medium units.

“A project that was tailormade for MSMEs to identify champions among them and also support them now also gets the additional benefit of UP’s one-district-one-product (OPOD) programme. UP has already completed the identification process of every product in every district, and also the champions in the state. So UP justifies the launch of Ubharte Sitaare programme,” she said, adding that this will help Sidbi to extend the credit and technology facility and boost capacity to go to the market to raise funds.

The FM highlighted the efforts taken by the government to provide a boost to the MSME sector in the country, including the launch of the production-linked incentive scheme and noted that the USF would make investments in export-oriented small and mid-sized companies by way of equity and equity-like products, and thereby help script a new paradigm of growth in exports. The initiative would play a catalytic role in contributing to the growth of the identified companies and would also have downstream benefits such as growth and diversification of India’s exports, impetus to brand India, and employment generation.

Harsha Bangari, deputy managing director, India Exim Bank, said India Exim Bank has developed a robust pipeline of over 100 potential proposals and supported several companies across a diverse range of sectors. SIDBI chairman & managing director Sivasubramanian Ramann highlighted several initiatives that have been taken in the recent past for the benefit of MSMEs in the country, more so in the state of Uttar Pradesh. Meanwhile, in another event, Punjab National Bank MD & CEO SS Mallikarjuna Rao handed over a loan sanction letter of Rs 5,100 crore for implementation of the Ganga Expressway project to the Uttar Pradesh Expressways Industrial Development Authority (UPEIDA).

The 594 km-long, eight-lane expressway project from Meerut to Prayagraj will cost nearly Rs 36,000 crore and will pass through 12 districts in UP. The amount of Rs 5,100 crore, under the securitisation process will be repaid to the bank within a period of 15 years from the toll to be received on the Agra-Lucknow Expressway. During this period of loan repayment, the expressway would continue to be owned and operated by UPEIDA.

Source: Financial Express

New MCA rules make cryptocurrencies, benami, loan disclosures mandatory

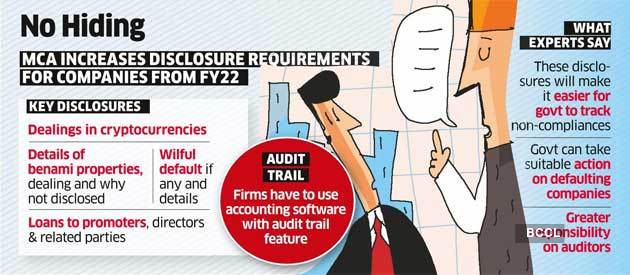
Starting April 1, companies must state if they have been declared wilful defaulters by banks, financial institutions or other lenders. The ministry also mandated companies to record audit trails of their accounts. Firms using accounting software to maintain their books need to use features that can record the audit trail of each transaction and create an edit log, including the date of such changes.

India Inc will have to declare investments in cryptocurrencies, relationships with dissolved companies and loans extended to related parties, among a host of other disclosures mandated by the government to improve transparency.

Starting April 1, companies must state if they have been declared wilful defaulters by banks, financial institutions or other lenders.

 The ministry of corporate affairs announced a new set of disclosures rules under the Companies Act on Wednesday, significantly enhancing financial and general reporting requirements for companies.

The ministry also mandated companies to record audit trails of their accounts. Firms using accounting software to maintain their books need to use features that can record the audit trail of each transaction and create an edit log, including the date of such changes.

Amending the Companies (Accounts) Rules, the ministry said firms must ensure the audit trail feature on the accounting software cannot be disabled. The move is aimed at curbing backdated entries and will affect mainly smaller companies as the bigger ones already use such software, according to Shalu Kedia, a partner at Nangia & Co.

Additional disclosures to be made under schedule III of the Companies Act, 2013, relate to matters such as corporate social responsibility spending, cryptocurrency dealings, benami property, relationship with struck-off, or dissolved, companies, and ageing of payables & receivables with vendors.

These disclosures will make it easier for the government to track non-compliance and take action against defaulting companies, experts said.

“Earlier, the companies were only required to disclose trade payables and receivables, but there was no requirement to provide ageing details. This disclosure will mandate the company to disclose the ageing payment cycle for MSMEs and non-MSME vendors,” said Nischal Arora, a partner at Nangia Andersen LLP.

Dealings in cryptocurrencies must be disclosed with details of the profit or loss on such transactions, amounts of such currency held and deposits or advances from any person for trading or investing in these currencies.

“While the government is already working on a bill on cryptocurrency, the disclosure for such currency has made it clear that the government wants to gather data on cryptocurrency,” said Arora.

Another important change was related to the disclosure of any benami property holdings.

“This disclosure is another step to improve transparency for the stakeholders as they will have to disclose any proceeding that has been initiated or pending against the company for holding any benami property and also provide a reasoning and view on the same,” said Amit Maheshwari, a partner at AKM Global.

The additional disclosures will make it mandatory for companies to provide details of shortfall in CSR spending for the previous years, including reasons for not meeting targets.

Loans granted to promoters, directors and related parties that are repayable on demand or without specific repayment terms from companies must be declared in terms of amount and percentage to total loans granted.

While this will push firms to regularly service their loans, it “will be helpful for the investor and other lenders to be aware about these types of companies before making any investment or lending the money,” Maheshwari said.

Schedule III Amendment Notification_24032021

Source: Economic Times

The Micro Small and Medium Enterprises (MSMEs) hit by Covid pandemic may have something to cheer at last.

Insolvency and Bankruptcy Board of India (IBBI) has formulated a Special Resolution Process (SRP) for MSMEs who find their financial position unmanageable due to Covid crisis.


While presenting the ‘Atma Nirbhar Bharat’ package Finance Minister had announced to come out with a Special insolvency resolution framework for MSMEs under section 240A of the Insolvency and Bankruptcy Code.

According to sources close to the development, the scheme would be available to corporate MSMEs, that is, units incorporated as Companies or LLP.

The salient features of the scheme are proposed to be:

  —   If an MSME finds it unable to meet its financial obligations, the insolvency resolution process could be initiated on the occurrence of default of at least Rs.1 lakh

  —   It can be triggered by the MSME promoter/ owner only (not by the Financial or other creditors)

  —   During the process of resolution, the MSME owner remains in control and keeps running the unit but all legal proceedings to take control of assets by creditors are stopped.

  —   It provides first right of offer to promoters of the MSME to submit resolution plans

  —   It proposes a simplified claim verification process and preparation of information memorandum

  —   It expands the scope of interim finance to facilitate rescue financing of the CD during COVID-19 with the approval of 3/4th financial creditors in value.

Federation of Indian Micro and Small & Medium Enterprises (FISME) which facilitated a consultation round of MSME associations with IBBI shared that most participants found the scheme potentially useful.

According to Lucknow based V K Agarwal Managing Director of Shashi Cables Ltd and former FISME President, the scheme seemed to be modelled on insolvency provisions under US chapter-11, was very promising indeed but some way needed to be found to make financial creditors to come on board and cooperate.

The scheme envisages appointment of an Insolvency Professional (IP) as Resolution Professional to conduct the process, with the consent of the unrelated financial creditors having at least 25% of the outstanding financial claims.

The scheme is under final stages of approval and is expected to be announced soon.

GST Council provides relief for GSTR 3B delays

GST Council, has recommended to reduce / waive the interest/ late fee for delayed filing of GSTR 3B by small taxpayers (having turnover upto Rs. 5 crores) for the tax period from July 2017 to July 2020
The ministry further said it has also taken a note of difficulties and concerns expressed by the taxpayers regarding filing of GSTR-3B and other returns.

The 40th GST Council met under the Chairmanship of Union Finance & Corporate Affairs Minister Smt Nirmala Sitharaman through video conferencing here today- 12th June 2020. The meeting was also attended by Union Minister of State for Finance & Corporate Affairs Shri Anurag Thakur besides Finance Ministers of States & UTs and senior officers of the Ministry of Finance& States/ UTs.

GST Council, has recommended to reduce / waive the interest/ late fee for delayed filing of GSTR 3B by small taxpayers (having turnover upto Rs. 5 crores) for the tax period from July 2017 to July 2020, as under:

  1. Reduction in Late Fee for Past Returns (July 2017 to January 2020)

As a measure for trade facilitation and to clean-up the pendency in filing of GSTR 3B for the period from July 2017 to January 2020, the GST Council has recommended to reduce/ waive the late fee for past returns, as under:

  1. a) ‘NIL’ late fee if there is no tax liability;
  2. b) Maximum late fee capped at Rs. 500/- per return if there is any tax liability.

The reduced rate of late fee would apply for all the GSTR-3B returns furnished between 01.07.2020 to 30.09.2020.

  1. Relief for filing of returns for February – April 2020

Further GST Council has recommended to provide relief for small taxpayers (having turnover upto Rs. 5 Crores) by way of reduced interest of 9% in lieu of 18% upto 30 Sept. 2020, for late filing of returns for the tax periods February, March and April 2020. This interest shall be charged beyond specified last date (staggered upto 6th July 2020) for filing of GSTR 3B return for the said tax periods.

  1. Relief for filing of returns for May – July 2020

Also, GST Council has recommended to provide relief for small taxpayers (having turnover upto Rs. 5 Crores) by way of waiver of interest and late fee upto 30 Sept. 2020, for late filing of GSTR 3B return for the tax periods May, June and July 2020.

Recommendations of GST council related to Law & Procedure

The GST Council has made the following recommendations on Law & Procedures changes.

  1. Measures for Trade facilitation:
  2. Reduction in Late Fee for past Returns:

As a measure to clean up pendency in return filing, late fee for non-furnishing FORM GSTR-3B for the tax period from July, 2017 to January, 2020 has been reduced / waived as under: –

  1. i) ‘NIL’ late fee if there is no tax liability;
  2. ii) Maximum late fee capped at 500/- per return if there is any tax liability.

The reduced rate of late fee would apply for all the GSTR-3B returns furnished between 01.07.2020 to 30.09.2020

  1. b) Further relief for small taxpayers for late filing of returns for February, March & April 2020 Tax periods:

For small taxpayers (aggregate turnover upto Rs. 5 crore), for the supplies effected in the month of February, March and April, 2020, the rate of interest for late furnishing of return for the said months beyond specified dates (staggered upto 6th July 2020) is reduced from 18% per annum to 9% per annum till 30.09.2020. In other words, for these months, small taxpayers will not be charged any interest till the notified dates for relief (staggered upto 6th July 2020)and thereafter 9% interest will be charged till 30.09.2020.

  1. c) Relief for small taxpayers for subsequent tax periods (May, June & July 2020):

In wake of COVID-19 pandemic, for taxpayers having aggregate turnover upto Rs. 5 crore, further relief provided by waiver of late fees and interest if the returns in FORM GSTR-3B for the supplies effected in the months of May, June and July, 2020 are furnished by September, 2020 (staggered dates to be notified).

  1. d) One time extension in period for seeking revocation of cancellation of registration:

To facilitate taxpayers who could not get their cancelled GST registrations restored in time, an opportunity is being provided for filing of application for revocation of cancellation of registration up to 30.09.2020, in all cases where registrations have been cancelled till 12.06.2020.

  1. Certain clauses of the Finance Act, 2020 amending CGST Act 2017 and IGST Act, 2017 to be brought into force from 30.06.2020.

Note: The recommendations of the GST Council have been presented in this release in simple language for information of all stakeholders. The same would be given effect through relevant Circulars/ Notifications which alone shall have the force of law.

Council to meet again in July to specially discuss how the government can pay off states for the compensation cess dues, since the funds are falling short.

Despite pandemic, Tamil Nadu attracts 17 investors worth Rs.15,128

The companies which signed the MoUs are from Germany, Finland, Taiwan, France, South Korea, Japan, China, USA, Australia, UK

As many as 17 MoUs’ to bring in fresh industrial investments worth Rs 15,128 crore into Tamil Nadu were signed between a host of foreign companies and the Tamil Nadu government in the presence of chief minister Edappadi K Palaniswami on Wednesday.

These projects in areas such as commercial vehicle manufacture, electronics, footwear, information technology, medical equipment and energy are expected to generate 47,150 jobs in Tamil Nadu, an official release here said.

The companies which signed the MoUs are from Germany, Finland, Taiwan, France, South Korea, Japan, China, USA, Australia, UK and the Netherlands, indicating that Tamil Nadu continues to be a destination for foreign direct investment (FDI).

Palaniswami’s government has been taking a number of initiatives for economic revival.  They include appointment of a high-power committee of economic experts led by former RBI governor C Rangarajan to chalk out strategies in the medium-term, the Industrial Guidance Bureau facilitating single-window clearance of investment proposals, the recent policy announced to boost production of medical equipment and drugs in the wake of Covid-19 and TIDCO offering a Rs.102 crore package to meet working capital requirement of 799 MSMEs’, an official release said.

The MoUs signed today include the following projects: Daimler India is to expand its commercial vehicle manufacturing at its Oragdam factory in Kancheepuram district involving an investment of Rs.2,277 crore, creating 400 more jobs.

Finnish firm Salcomp will invest Rs.1,300 crore in the Nokia special economic zone in Sriperumbudur to manufacture mobile phone components, to generate 10,000 additional jobs in Kancheepuram district and this project would help to rejuvenate the Nokia SEZ in that district.

The MoUs further include Rs. 900 crore investment by Japan’s Polymatech Electronics to make semiconductor chips at the Oragadam SIPCOT industrial park, a Rs.350 crore joint venture footwear manufacture project by Taiwan’s Chung Jye Company Ltd and Aston Shoes, a Rs.400 crore industrial park to be developed at Mappedu in Kancheepuram district by Australian firm, Lai Investment Manager Pvt Ltd., South Korea’s ‘Mando Automotive India  Pvt Ltd.  to invest Rs.150 crore in Pillaipakkam SIPCOT industrial park in Kancheepuram district, Netherlands’ Dinex to invest Rs.100 crore in the Mahindra City Industrial Park in Chengalpattu district for auto-components manufacture, a 750-mw gas-based power project at Ponneri in Thiruvallur district by Indo-UK joing venture, Chennai Power Generation Limited’ involving an investment of Rs.3,000 crore, and France’s IGL India Transplantations Solutions Ltd to invest Rs. 18 crore in medical equipment in SIPCOT park at Cheyyar in Tiruvannamalai district.

Down south in Thoothukudi and Tirunelveli districts, a huge investment of Rs. 2,000 crore is envisaged by Vivid Solaire Energy Private Limited of France, to manufacture wind mills equipment, the release said. The USA’s HDCI Data Centre Holdings Chennai LLP will invest in an IT project in Ambattur in Chennai involving an investment of Rs. 2,800 crore, it said.

While Singapore’s ST Tele Media will invest Rs. 1,500 crore in a new IT project in Chennai, wind mill components will be made by Germany’s Baetter in Chennai involving an investment of Rs.210 crore. Besides there, there are four more industrial investments in the pipeline in Kancheepuram, Thiruvallur and Chengalpattu districts including China’s ‘BYD India Private Ltd’, to invest Rs.50 crore in an electric vehicle manufacture project.

Mahindra Origins in a JV with a Taiwanese company, TJR Precision Technology Company, will invest Rs.46 crore in making precision components at Ponneri. Further, USA’s Lincoln Electric will invest Rs.12 crore in an R & D Centre at Mahindra Industrial Park in Chengalpattu district, the release added.

Top officials including Chief Secretary, Mr. K Shanmugam, Industries Secretary, N Muruganandam, State Guidance Bureau managing director, Ms. Karkala Usha, its executive director Mr. Aneesh Shekhar, and representatives of the various companies were among those who were present on the occasion.

Source: Deccan Chronicle