Silicon Valley venture capitalists raise more money, give less away

Venture capitalists are raising money at the fastest rate in a decade, raking in about $13 billion in the first quarter of 2016.

But much of that cash won’t flow into new startups anytime soon. Rather, venture firms are bracing for a downturn and boosting reserves to keep companies they have already backed from going bust, said venture capitalists and limited partners.

“They are squirrels trying to pack their cheeks full of nuts,” said Ben Narasin, a partner at Canvas Ventures. “Everyone has been waiting for winter to start for a long time.”

The paradox of rising venture fundraising and falling venture investing is the latest sign of a tectonic shift in the tech startup realm. The extraordinary growth of so-called “unicorn” companies such as Uber and Airbnb – now valued at tens of billions of dollars, based on venture investments – has left many high-value startups with no “exit strategy,” in Silicon Valley parlance.

Burned by previous busts, Wall Street has lost its appetite for initial public offerings from money-losing companies. No venture-backed tech startup has gone public this year, and the few that did last year – including enterprise storage company Pure Storage, and cloud storage and file-sharing firm Box – have seen their share prices steadily sink. High valuations have also scared off potential acquirers.

Scale Venture Partners exemplifies the cautious approach taking hold in the VC industry. It chose to do one fewer investment from its last fundraising round and to increase its reserves by more than 10 percent.

“We will have to support our companies longer,” said Rory O’Driscoll, a partner at the firm, which raised a $335 million fund in January.

Accel Partners has reduced its pace of new investments since the middle of last year, while increasing its follow-on funding for portfolio companies, according to an analysis by venture capital database CB Insights.

The venture firm raised $2 billion in March, but it won’t tap into the new fund until late fall, said managing director Richard Wong.

Total U.S. venture investment fell to $12.1 billion in the first quarter – down 30 percent from the most recent peak of $17.3 billion in the second quarter of last year.

Chris Douvos, managing director of Venture Investment Associates, an investor in early-stage venture funds, says the funds he backs are increasing their reserves by 10 percent to 25 percent over what they had in previous funds.

The $13 billion raised by VCs is the third-largest quarter for fundraising since the dot-com peak in 2000, according to Thomson Reuters data. There is now $382 billion of dry powder – cash available to spend – held by both venture capital and private equity firms that invest in technology companies, according to investment banking and consulting firm Bulger Partners.

“It’s fast, and it’s a lot of dollars this year,” said Beezer Clarkson, managing director at Sapphire Ventures, which invests in early-stage venture funds.

Many VCs believe that more reserves will be needed for the big cash infusions that startups often need after establishing themselves but before turning a profit.

VCs are also seeing mutual funds retreat from late-stage startup financing deals. Mutual funds led just eight deals in the fourth quarter of last year, down from 26 in the second quarter, according to the research firm CB Insights.

The confluence of trends means that money-losing startups likely will struggle more for venture capital. That, in turn, could lead to more companies failing or cutting staff, cooling the red-hot market for tech talent. It could also strengthen the hand of dominant tech companies, who may face fewer disruptive rivals and attract employees tired of volatile startup life, according to tech recruiters.

CASH BURN

Until recently, many venture capitalists have had a land-grab mentality, even with more obscure startups such as Magic Leap – an augmented reality company that raised about $800 million in February – or Social Finance, a startup in the highly scrutinized fintech sector that raised $1 billion in September.

Investors competed fiercely to finance hot companies they believed could be the next Google or Facebook. Higher prices for smaller stakes drove up valuations in companies, including many who burned cash quickly in a quest for growth. Many venture capitalists say they overpaid by 20 to 30 percent, and now have to keep those companies afloat.

Over the past six months, however, nervous whispers about a tech bubble have sparked rising skepticism of venture-dependent startups with stratospheric price tags.

The same venture capitalists who jousted in bidding wars for the next great deal just six months ago are now fending off appeals.

Canvas Ventures, Norwest Venture Partners and Accel Partners – among Silicon Valley’s more prominent firms – say they are getting more calls from peers asking them to join a late-stage round for companies running out of cash.

“We get a lot more ‘special opportunities, just for you,'” said Wong, of Accel Partners. “We get the phone calls, along with everyone else.”

PAPER GAINS

For now, venture capitalists have little problem raising money, despite their new hesitance to spend it and the inability of many startups to turn profits or go public.

That’s in part because many VC firms are currently showing huge paper gains in the value of their portfolios. Many firms are raising as much as possible now, in case valuations drop in so-called “down rounds,” when later stage investors pay less for company stakes than earlier ones, and the returns on their investments plummet, according to limited partners.

Signs of falling returns are already emerging. Cambridge Associates, an investment advisor, measured a -0.4 percent return on the U.S. Venture Capital Index for the third quarter of last year, the first down quarter since 2011.

First Round Capital, an early-stage venture firm, warned its limited partners in a letter a year ago that the seed-stage venture capital deals will see much lower returns in the next several years.

But that warning didn’t scare Douvos, an investor in First Round, which was an early backer of Uber and made a bundle on the IPOs of Square and OnDeck Capital.

“Fund performance will soften,” Douvos said. But, he said, “The returns from First Round are so good that nothing else really matters.”

Read Source: http://www.reuters.com/article/us-venture-fundraising-idUSKCN0Y41DQ
 

Clean energy projects get Rs 86,000 crore investment

Renewable energy projects have received Rs 86,000 crore investment, most of it from private sector, in the last three years with Madhya Pradesh at top garnering Rs 14,313.80 crore.

“Most of the investment in renewable energy came from private sector. Total estimated investment in renewable energy power projects during the last three years is around Rs 86,000 crore,” New and Renewable Energy Minister Piyush Goyal said in a written reply to Lok Sabha today.

According to the statement, around 15,400 million units has been generated through solar power projects during the last three years.

Madhya Pradesh remained at the top, recording maximum investment in clean energy projects at Rs 14,313.80. It was followed by Maharashtra at Rs 13,743.01 crore, Rajasthan at Rs 11,632.96 crore, Karnataka at Rs 9,586.31 crore, Andhra Pradesh at Rs 9,539.12 crore, Tamil Nadu at Rs 8,961.28 crore and Gujarat at Rs 6,646.35 crore.

The minister also stated that Pondicherry, Laskhwadeep, Dadar & Nagar Haveli, Sikkim, Manipur, Meghalaya and Goa received no investment at all for renewable energy projects in last three years.

According to a separate reply to the House, as on March 31, 2016, a cumulative capacity of 42.76 GW has been installed from various renewable energy sources, which include 26.78 GW from Wind, 6.76 GW from solar, 4.27 from small hydro power and 4.95 GW from bio power.

In another reply to the House, the Maharashtra will require the maximum solar power generation capacity of 13,270 MW by 2021-22 as per tentative renewable purchase obligation (RPO) requirement estimated by the ministry.

The ministry has estimated 1,02,021 MW solar power generation capacity to be installed in the entire country by 2021-22.

After Maharashtra, Uttar Pradesh’s solar power generation capacity by 2021-22 as per RPO requirement would be the second highest at 12,124 MW followed by Gujarat at 9,796 MW, Tamil Nadu at 9,398 MW and Rajasthan 6,953 MW.

Under RPO, states are mandated by power regulators to have certain proportion of renewable energy capacity in their total power mix to promote clean and green sources like solar and wind.

The minister in another reply to the House stated that the new pithead thermal power plants have the lowest tariff of Rs 3.75 per unit in the first year of operation compared Rs 4.5 per unit for solar, Rs 4.6 for hydro, Rs 4.94 for atomic power and Rs 5.49 for non-pithed thermal plants.

However, the levellised tariff for hydro power plants is the lowest at Rs 4 per units compared Rs 4.5 for solar, Rs 5 for atomic power, Rs 4.57 for pithead based thermal power and Rs 7.57 per unit for non-pithead based thermal power plant.

Source:http://economictimes.indiatimes.com/articleshow/52125394.cms

IRDAI okays 16 FDI proposals worth Rs 14,592 crore

Insurance regulator IRDAI has approved as many as 16 proposals amounting to Rs 14,591.9 crore as foreign investment, Parliament was informed today.

“Post notification of the Insurance Laws (Amendment) Act, 2015, Irdai has approved 16 proposals amounting to Rs 14,591.89 crore as foreign investment in the insurance sector,” Minister of State for Finance Jayant Sinha said in a written reply in the Rajya Sabha.

The Insurance Laws (Amendment) Act, 2015, provides for an increase of foreign investment cap in an Indian insurance company to 49 per cent from 26 per cent with the safeguard of Indian ownership and control, he said.

The government had notified the Indian Insurance Companies (Foreign Investment) Rules, 2015, to facilitate foreign investment in the insurance sector.

“Indian Insurance Companies (Foreign Investment) Rules, 2015, have been amended on March 16, 2016, to allow foreign investment up to 49 per cent through automatic  route in the insurance sector,” Sinha said.

To bring clarity on ‘Indian owned and controlled’, the Insurance Regulatory and Development Authority of India (Irdai) has issued guidelines on the same.

In December, Irdai chief T S Vijayan had said higher foreign participation in the insurance sector will attract more capital and increase sectoral penetration in India.

Source : http://economictimes.indiatimes.com/articleshow/52094191.cms

China commends India’s GDP growth; says keen to invest more

China has complimented India for “doing a good job” in maintaining an impressive growth rate despite a global slowdown and is keen on working together to push for reforms in the international financial system to offset the inherent weaknesses.

Stating that his country was keen to ramp up investments in India, Chinese Foreign Minister Wang Yi said the two major emerging economies can contribute significantly in helping the world economy by keeping up their growth momentum.

“First of all, we both need to grow our own national economies. On this front, we want to commend India for doing a good job in promoting economic growth,” said Wang.

Wang, who was here to attend Foreign Ministers’ meeting of RIC (Russia, India, China) grouping, further said reform of global financial system is key to protect the interest of developing countries and for recovery of the world economy.

“We need to join hands in playing a positive role in improving the global economic and financial governance because that will help protect the interests of the developing countries. It will also help the world economy to embark on a path of strong recovery,” Wang said.

He said China was “optimistic” about the prospect of deeper relationship between the two countries.

“Of course, we will be happy to invest more in India. There is no doubt about it,” he added.

After witnessing nearly three decades of close to double-digit growth, China has seen a decline in its growth rate, making room for India to replace it as the fastest-growing major economy of the world.

However, Chinese economy remains much bigger than that of India in terms of the overall size.

China clocked 6.9% growth in 2015 when India is estimated to have grown by 7.3%. The IMF has projected Indian economy to grow at 7.5% in 2016 and 2017.

The Chinese Foreign Minister also said his government was “looking forward” to President Pranab Mukherjee’s upcoming visit to China.

Sebi may soon revisit start-up listing norms

The Securities and Exchange Board of India (Sebi) may soon review its framework for listing of start-ups, including e-commerce firms, while incorporating suggestions from various stakeholders to make this platform much more vibrant.

The Institutional Trading Platform (ITP) is yet to see any start-up listing ever since an easier set of compliance and disclosure requirements was notified in August 2015.

These norms have been put in place to encourage Indian start-ups and entrepreneurs to remain within the country rather than go abroad for funds.

Under the rules, start-ups can list on the separate ITP of stock exchanges such as and NSE.

The platform is open to only institutional investors and high networth individuals (HNIs), while retail investors have been excluded in order to safeguard small investors against a higher level of risks associated with this platform.

Many start-ups believe that the current listing norms are unattractive for them to list in India. Moreover, not a single company got listed on the relaxed ITP platform.

Now, is likely to review the ITP norms soon. It will also incorporate suggestions from various stakeholders to make this platform much more vibrant, sources said.

Sebi’s Primary Market Advisory Committee (PMAC) has also suggested that norms should be reviewed as the matter progresses.

Under the notified rule, minimum trading lot and the minimum application size have been kept at Rs 10 lakh so that only sophisticated and large investors come in.

For their listing, Sebi also relaxed the mandatory lock-in period for promoters and other pre-listing investors to six months, as against three years for other companies.

Besides, the disclosure requirements for these companies have been relaxed.

The companies can, however, graduate to the main platform later and the small investors can also invest at that time.

Earlier this month, Infibeam Incorporation made a stock market debut becoming the first e-commerce player in the country to get listed. The firm got listed on the main-board instead of institutional trading platform.

Source: http://www.business-standard.com/article/markets/sebi-may-soon-revisit-start-up-listing-norms-116041500531_1.html

Korn Ferry to help Indian start-ups

Stephen Kaye, CEO of Korn Ferry Hay Group

US-based global management consultancy giant Korn Ferry Hay Group has embarked on an ambitious plan to support for free 100 start-ups from India that have potential to grow big, its CEO Stephen D Kaye said on Friday.

Talking about the group’s ambitious NextBig100 programme, Kaye said it is supporting the next big-100 start-ups in India and would help them as they go through various growth stages.

“We are working alongside those companies to help them move forward and to support the development of business in India.”

Source: http://www.thehindubusinessline.com/companies/korn-ferry-to-help-indian-startups/article8451964.ece

How FIIs outsmart domestic investors

Domestic investors have a lot to learn from their foreign institutional counterparts, who seem to have mastered the art of timing, raking in the moolah in the midst of market volatility.

On the other hand, domestic investors mostly buy when foreign institutional investors (FIIs) are booking profits at higher valuations, limiting their own upside.

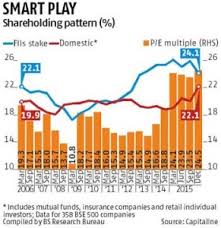
For example, in the current rally, most of the FII purchases were in 2012 and the first half of 2013, when the price-to-earnings (PE) multiple of BSE 500 companies had hit a multi-year low.

In contrast, most of the accumulation by domestic investors, through mutual funds and insurance companies, occurred in 2015 when BSE 500 companies were trading at a multi-year PE high. FIIs accumulated India’s top-listed companies at an average valuation of around 16 times and offloaded it to domestic investors at around 24 times their value (see chart).


In all, FIIs’ stake in BSE 500 companies was up 550 basis points between March 2012 and March 2015, at an average PE of around 16 times the companies’ combined trailing 12-month net profits. FIIs stake peaked in the March 2015 quarter, coinciding with the peak in valuations of BSE 500 companies. One basis point is one-hundredth of a per cent.

The analysis is based on the end-of-quarter shareholding pattern, market capitalisation and quarterly net profit of BSE 500 companies, beginning the March 2006 quarter. The sample is based on the data for 358 companies where the data is comparable across the period.

Analysts attribute this to the steady nature of fund flows FIIs receive, while domestic institutional investors are at the mercy of inflows from retail investors, which tend to take place late in the cycle.

“When FIIs were buying in 2012-13, insurance companies and mutual funds were still facing redemption, forcing fund managers to sell their holdings even when the valuations were low. Inflows turned positive only in late 2014 and 2015, when domestic retail investors were convinced about the rally,” said Dhananjay Sinha, head, institutional equities, Emkay Global Financial Services.

In comparison, FIIs receive a significant portion of their funds from large institutional investors in Europe and the US, whose investment sentiment remains steady over a long period.

Others also point to differences in the investing styles of FIIs and their domestic counterparts.

“FII investments are largely fundamental and research-driven compared to domestic investors, most of whom tend to get swayed by market sentiment and herd mentality,” said G Chokkalingam, the founder and chief executive officer of Equinomics Research & Advisory.

This explains why a majority of domestic investors fail to make money in the market, he added.

A similar trend was visible in the rally before the global financial crisis, when FIIs were net sellers for nearly two years in the run-up to the September 2008 crash while domestic investors were buyers.

Despite the trends, some analysts differ.

Nitin Jain, the president and chief executive officer of global asset and wealth management firm Edelweiss Capital, said there is no evidence of domestic investors being less smart than their foreign counterparts.

“We should not paint all FIIs with the same brush. Investment flows from exchange-traded funds, which is retail money – as volatile and sentiment-driven as domestic retail and mutual funds flows. FIIs, on the other end of the spectrum, also get pension money and sovereign wealth funds, which are long-term and their investment style is similar to that of domestic insurance companies,” said Jain.

Source: http://www.business-standard.com/article/markets/how-fiis-outsmart-domestic-investors-116032800052_1.html