Smaller VC firms ride on SIDBI and local investors

In the past six months, several venture capital (VCs) funds have raised money or are in the process of raising money. These include funds from IDG Ventures, DSG Consumer Partners, Orios Venture Partners, Kae Capital, Blume Ventures, Saama Capital, Fireside Ventures, Stellaris Venture Partners, Endiya Partners and Pravega Ventures.


What’s common between them is Sidbi, the lending institution managing several start-up funds, including the government’s, which plays an anchor investor to many of these funds with a 15-20 per cent stake. This is helping these funds raise money from other domestic investors — family offices and high networth individuals (HNIs).


‘‘Fundraising is not easy, especially for smaller VC firms. They don’t get large institutional investors; they get family offices and HNIs,” says a VC. Having an institution like Sidbi comforts other local investors.


‘‘Sidbi does extensive amount of due-diligence, reporting, appoints board members. They have a proper investment committee. So, you have comfort that there’s institutional due-diligence on the fund,” says Rehan Yar Khan, managing partner, Orios Venture Partners.


In February, Sidbi said its fund of funds operations has sanctioned Rs 1,112 crore to 30 funds in FY17, double of Rs 607 crore for 16 funds it did in FY16. Sidbi manages many fund of funds, including the government’s Rs 10,000-crore fund of funds for start-ups.


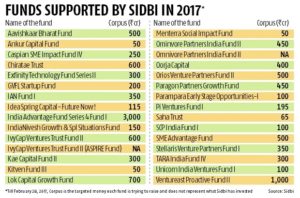
The funds, which have received Sidbi’s commitment under this programme, are Orios Venture Partners Fund II (Rs 50 crore), Kae Capital (Rs 45 crore), and two little known funds, Saha Trust (Rs 10 crore) and Kitven Fund III (Rs 5 crore), Sidbi disclosed in response to an RTI query from Business Standard. There are others like Blume Ventures, IDG Ventures, India Quotient, which have received Sidbi’s funding.


Interestingly, several funds — maiden funds and second funds — have hit the market in the past one year, all targeting domestic investors. Yet, all of them are able to raise money and announced their first or final close, which shows the increasing depth of domestic investors.


These include professionals in large firms, like Infosys founders, who have made money through ESOPs, family offices of traditional business families and others which are starting to get organised.


Many wealth management and advisory firms have come up, who are able to reach these family offices in a more effective way.  But are we seeing too many funds raising too much capital?


‘‘There’s a big need for early stage capital. In the US, the size of the VC market is $25-26 billion and the seed capital of $22 billion. As opposed to that, we are at a pittance. The game has not even started here,” says another VC. Besides, bigger VC firms like Accel, Sequoia also do seed-stage deals, but mostly do VC.
Source: http://www.business-standard.com/article/economy-policy/smaller-vc-firms-ride-on-sidbi-and-local-investors-117030900003_1.html

Fund mop-ups via IPOs in 2016 three-fold higher than a year ago

Money raised through public issues in 2016 so far is three fold higher compared to the same period in 2015. As many as 21 companies have debuted on the bourses so far raising Rs 19,379.09 crore, an increase of around 205% compared to last year when 15 companies raised Rs 6,346.02 crore, data compiled from Prime Data base shows. During the same period in 2014, four companies raised Rs 4,029 crore.


Of the issues that hit the primary markets in 2016, the Rs 6,000-crore initial public offering (IPO) of ICICI Prudential Life Insurance, a subsidiary of ICICI Bank, was the biggest. This is followed by the issue of small finance bank, Equitas Holdings which raised around Rs 2,000 crore. Punjab National Bank’s (PNB) subsidiary firm, PNB Housing Finance will hit the primary market on Oct 25,the company is expected to raise Rs 3,000 crore in a price band of Rs 750 – Rs 775.


According to data compiled from the website of Securities and Exchange Board of India (Sebi), draft documents of as many as 10 companies are under process of receiving the market regulator’s approval for their public issues. Among the companies whose issues are yet to receive Sebi’s approval include Aster DM Healthcare, Avenue Supermarts, Security &Intelligence Services (India) and Continental Warehousing Corporation. The IPOs of these companies are expected between Rs 1,000 and Rs 2,000 crore.


On the other hand, as many as 15 companies have received Sebi’s approval for their public issues which are expected to raise around Rs 4,800 crore. Of the issues, the Rs 1,000 crore IPO of pharma company Laurus Labs is the biggest issue followed by real estate firm Paranjape Schemes whose issue is expected to raise Rs 600 crore.

Source: http://www.financialexpress.com/markets/indian-markets/fund-mop-ups-via-ipos-in-2016-three-fold-higher-than-a-year-ago/428823/

DIPP notifies 100% FDI in more financial services

DIPP notifies 100% FDI in more financial services The commerce and industry ministry notified 100 percent foreign direct investment in ‘other financial services’ carried out by NBFCs.


The move will help attract foreign capital into the country. “The government has liberalised its FDI policy in Other Financial Services and non-banking finance companies (NBFCs), the DIPP said in a press note.


Other financial services will include activities which are regulated by any financial sector regulator – RBI, SEBI, IRDA, Pension Fund Regulatory and Development Authority, National Housing Bank “or any other financial sector regulator as may be notified by the government in this regard,” it said.


Such foreign investment would be subject to conditionalities, including minimum capitalisation norms, as specified by the concerned regulator or government agency, it said.


The press note, however, did not specify the sectors which have been opened up for automatic route. The present regulations on NBFCs stipulate that FDI would be allowed on automatic route for only 18 specified NBFC activities after fulfilling prescribed minimum capitalisation norms mentioned therein.


In the Budget 2016-17 Speech, Finance Minister Arun Jaitley had announced about this liberalisation.


Currently, 100 percent FDI through automatic route is permitted in 18 NBFC activities including merchant banking, under writing, portfolio management services, financial consultancy and stock broking. In 2015-16, foreign direct investment in India grew by 29 percent year-on-year to USD 40 billion.

Source: http://www.moneycontrol.com/news/economy/dipp-notifies-100-fdimore-financial-services_7829901.html


Foreign VCs can now invest in unlisted firms sans RBI nod

Foreign venture capital entities can now invest in unlisted Indian companies without Reserve Bank of India approval.

The venture capital firm will, however, have to be registered with market regulator SEBI. The investment can be made in an Indian company in 10 specific sectors or in any start-up.

The central bank on Thursday amended the regulations governing foreign venture capital investors (FVCI) in order to further liberalise and rationalise the investment regime and to give a fillip to foreign investment in start-ups.

According to the RBI, the 10 sectors in which SEBI-registered FVCIs can invest without its nod are: biotechnology, IT, nanotechnology, seed research and development, discovery of new chemical entities in pharmaceutical sector, dairy industry, poultry industry, production of bio-fuels, hotel-cum-convention centres with over 3,000 seating capacity, and infrastructure sector. FVCIs can also invest in equity, equity-linked instruments or debt instruments issued by an Indian ‘start-up’ irrespective of the sector in which it is engaged. The RBI said a start-up will mean an entity (private limited company, registered partnership firm or a limited liability partnership) incorporated or registered in India not prior to five years, with an annual turnover not exceeding Rs. 25 crore in any preceding financial year.

These start-ups should be working towards innovation, development, deployment or commercialisation of new products, processes or services driven by technology or intellectual property and satisfying certain conditions as given in the Foreign Exchange Management Regulations, 2016.

The RBI also said FVCIs can invest in units of a venture capital fund (VCF) or a Category-I alternative investment fund (AIF) or units of a scheme/fund set up by a VCF or by a Category-I AIF.

In a circular issued to banks authorised to deal in foreign exchange, the RBI said: “In order to further liberalise and rationalise the investment regime for FVCIs and to give a fillip to foreign investment in the start-ups, the extant regulatory provisions have been reviewed, in consultation with the Government of India.”

The consideration for all investments by an FVCI can be paid out of inward remittance from abroad through normal banking channels or out of sale/maturity proceeds of or income generated from investment already made. There will be no restriction on transfer of any security/instrument held by the FVCI to any person resident in or outside India.

Source: http://www.thehindubusinessline.com/todays-paper/foreign-vcs-can-now-invest-in-unlisted-firms-sans-rbi-nod/article9247432.ece

IPO fund-raising in India highest since 2011

Fund raising through initial public offerings (IPOs) has crossed $2.9 billion in 2016 and another $2.9 billion is to be raised through these offerings this year, according to a research report by Baker & McKenzie.

Around 22 companies are waiting to tap the markets bringing the year-end estimated total deal value to $ 5.8 billion, more than double last year’s $2.18 billion from 71 listings, and also the highest since 2011, the report said.

The report further said that 16 companies are in the pipeline to be listed domestically in 2017, raising as much as $5.86 billion, including Vodafone’s highly anticipated $3 billion IPO, which could potentially surpass the state-run Coal India’s IPO in 2010 to become India’s biggest IPO.

The report said the momentum in India’s IPO market continues to build, boosted by the central government’s push to ease of doing business in India.

The report added that Goods & Services Tax (GST) Bill which will take effect on 1 April 2017 will have a positive effect on the market.

“The GST Bill will not only bring about the immediate benefit of widening the country’s tax base and improving the revenue productivity of domestic indirect taxes, but more importantly, it sends the message to the people of India and the rest of the world that the Indian government is committed to the country’s economic reform, further bolstering India’s attractiveness as an investment destination,” said Ashok Lalwani, head of Baker & McKenzie’s India Practice.

The report said dual listing on both the Bombay Stock Exchange (BSE) and the National Stock Exchange (NSE) of India accounted for 98.8% of Indian companies’ listings by value in 2016 year to date, raising a total of $ 2.9 billion from 19 IPOs, including ICICI Prudential Life Insurance’s $909 million IPO, which is the country’s biggest IPO this year.

A total of 33 companies are expected to dual list on both the BSE and the NSE by the end of 2016, raising a total of $4.62 billion. Improved business confidence is also driving Indian companies to look at growth and market expansion opportunities overseas by way of cross-border IPOs, the report said.

Among the 22 IPOs in the 2016 pipeline is Strand Life Sciences’ listing on NASDAQ, which if it goes ahead, will be India’s first cross-border IPO since early 2015 when Videocon d2h got listed, the report added.

Source: http://www.financialexpress.com/industry/companies/ipo-fund-raising-in-india-highest-since-2011/415830/

Sebi deems share transfer by promoters by way of gift as sale

Any inter-se transfer of shares by a promoter to his wife will be considered as sale even if it is in the form of a gift where no monetary transaction is involved, Sebi said.

According to guidelines, the promoters are not eligible for preferential allotment of shares or warrants if there has been any inter-se transfer of shares among promoter group firms in the last six months.
Giving its views on an application filed by KJMC Financial Services, the watchdog said that as envisaged in the Sebi ICDR (issue of capital and disclosure requirements) regulations, any transfer of shares in the form of gift will be considered as sale.
As per Sebi’s ICDR regulations, if any person belonging to the promoter or promoter group in the issuer company has sold his equity shares during the six months preceding the relevant date, such entity will be ineligible for allotment of specified securities on a preferential basis.
KJMC Financial Services had sought an interpretative letter from Sebi on whether transfer of shares by its promoter to his wife by way of gift will be considered as sale under the Sebi’s ICDR regulations.
“Our view is that the inter-se transfer by way of gift will be considered as sale as envisaged… in the Sebi ICDR regulations,” Sebi said, adding that its response is based on the information given in the company’s letter. Referring to the ICDR regulations, the regulator said: “The primary intention of the regulation was not with respect to consideration, but with change in ownership of equity shares.” It added: “Different facts or conditions might lead to a different result.

Further, this letter does not express a decision of the board on the questions referred.” The watchdog also said its views are expressed with respect to the clarification sought in terms of Sebi ICDR norms and is not applicable to any other Sebi regulations.

Source: http://www.moneycontrol.com/news/economy/sebi-deems-share-transfer-by-promoters-by-waygift-as-sale_7454721.html?utm_source=ref_article


FPI inflows top Rs. 20,000 cr in Sept, at 11-month high

Foreign investors pumped in more than Rs. 20,000 crore into the capital market in September, making it the highest net inflow in 11 months.

This also marks the third consecutive month of positive inflows (equity and debt).

The trend is likely to continue in the coming weeks as regulator SEBI has decided to offer well-regulated foreign investors direct entry to invest in corporate bonds, say experts.

They attributed the latest flurry of capital to factors such as sound progress in roll-out of GST, better corporate earnings and the US Fed’s decision not to lift interest rates.

Sentiment turned better after the current account deficit (CAD) narrowed sharply to just $300 million, or 0.1 per cent of GDP, in the June quarter and domestic passenger vehicle sales grew for the 14th straight month in August, they added.

According to depositors’ data, net investment by FPIs stood at Rs. 10,443 crore in equities last month while the same for debt was Rs. 9,789 crore, taking the total inflow to Rs. 20,233 crore ($3 billion).

This was the highest net inflow in the capital markets since October 2015 when FPIs had infused Rs. 22,350 crore.

The latest inflow has taken the FPI investment tally in equities to Rs. 51,293 crore in 2016 while the same for the debt market stands at Rs. 2,441 crore, resulting in a net inflow of Rs. 53,734 crore.

Source: http://www.thehindubusinessline.com/economy/fpi-inflows-surpass-rs-20000-cr-in-sept-at-11month-high/article9176139.ece