SEBI warns of rising external debt risks as masala bonds surge

The rupee-denominated bonds, popularly known as masala bonds, are likely to add to the nation’s external liabilities even if they don’t hold any risks to currency movement, a top SEBI official said.

The rupee-denominated bonds, popularly known as masala bonds, are likely to add to the nation’s external liabilities even if they don’t hold any risks to currency movement, a top Sebi official said on Wednesday.

“When money flows into the country from foreign investments, we are attracting some risks and it is not currency risk alone. Masala bonds don’t hold any currency risks but at the same time, the external liability of the country goes up. This needs to be kept in mind,” Sebi whole- time member G Mahalingam said here.

“And a huge amount of foreign inflows at a time when the currency has been substantially appreciating is something the regulators must be concerned about,” he said, addressing a capital markets summit organised by industry lobby Ficci.

The masala bonds are debt instruments through which designated domestic entities can raise funds by accessing overseas capital markets, while the bond investors hold the currency risk. In fact, the World Bank arm IFC thus far has raised the largest amount through this instrument.

According to some estimates, the masala bonds accounted for 39 per cent of the total ECBs of USD 7.39 billion reported by the Reserve Bank in the fourth quarter of FY17, while the approvals for the same rose to USD 2.9 billion over USD 0.8 billion in the third quarter.

For the full fiscal of 2017, the aggregate stood at USD 4.6 billion, according to a recent Icra data.

Of the total masala bonds of USD 4.59 billion approved during FY17, 55 per cent were for onward lending in domestic markets, 24 per cent for refinancing of the rupee loans and 14 per cent were for general corporate purposes.

Mahalingam said the Sebi is in advanced stage of talks with other regulators on allowing participation of FPIs in commodity derivatives market.

On the mutual fund industry, he said the sector should try to bring down its total expense ratio which is far higher than the comfort level. “It is time for mutual funds to shrink its margins attract more retail investors.”

He said benchmarking of returns will be healthy step for the overall industry.

Source: MoneyControl.com

SEBI crackdown on trading in 331 shell companies blocks investors’ Rs 9,000 cr

The government crackdown against 331 “suspected shell companies” has hit several investors, including mutual funds and small investors, who hold shares worth nearly Rs 9,000 crore in these companies.


In a late circular on Monday, market regulator Securities and Exchange Board of India (Sebi) directed stock exchanges to immediately restrict trading in 331 companies identified as “shell companies” by the Ministry of Corporate Affairs in consultation with the Serious Fraud Investigation Office (SFIO) and the income-tax (I-T) department.


While, by definition, a shell company is one without any business operations or assets, several companies with active business dealings too were part of the  list with 331 names. At least five companies in the list have market capitalisation (m-cap) of over Rs 500 crore each, with diverse shareholding from institutional as well as retail investors.


These companies have been placed in the so-called graded surveillance measure (GSM) stage VI, where trading in the security is allowed only once a month with “surveillance deposit” of three times the trade value.


Companies, including J Kumar Infraprojects (m-cap of Rs 2,150 crore), Prakash Industries (Rs 2,124 crore), Parsvnath Developers (Rs 1,036 crore), and multinational company SQS India BFSI (Rs 535 crore), termed the “shell company” classification as wrongful and urged Sebi and exchanges to reconsider the directions.


graph

“It is hereby clarified J Kumar is not a shell company and the suspicion of the regulator is uncalled for. Our company’s compliance track record, both with the exchanges and Registrar of Companies, has been impeccable,” said the Mumbai-based infra developer, highlighting the various projects it currently working on, including some government contracts.


Sebi sources said over three dozen companies in the list technically don’t fall under the definition of a shell company and the circular maybe revised to correct the nomenclature.  “The regulator is verifying the companies who have raised grievances. However, a rectification may take some time as the exchange needs to conduct an audit and submit a report to Sebi. If there is an all-clear given by the auditors and the regulatory authorities involved, Sebi can lift the ban,” said a source.
Another source said the Ministry of Corporate Affairs has widened the scope of shell companies. Those with cases against them in the SFIO or those that have evaded taxes are part of the list. A finance ministry official said concerns of investors in these companies will be looked into.
Several companies made detailed representations to Sebi and corporate affairs ministry, stating they can’t be termed as shell companies. “There could be a possibility that companies who are listed in the shell categories are genuine. In that case, they can always approach Sebi and stock exchanges to remove the ban. This is more of a preventive action and could be rectified if an entity is not found guilty,” said J N Gupta, managing director at Stakeholders Empowerment Services (SES).


Experts said the while all companies may not be shell companies, it is possible that the enforcement agencies may have found some dubious links and decided to take action.


“This is in continuation of strong messages being sent to corporate entities that frauds of any nature will face strong action. Greater vigil and networking of several databases would throw up more malpractices and stricter action,” said Prithvi Haldea, founder-chairman at Prime Database.


Government’s fight against market manipulation to evade LTCG


Several probes by the I-T department and Sebi have shown that listed shell companies were being used to launder money by using the stock exchange route. The typical modus operandi has been to buy shares of shell firms, jack up the prices and sell shares after a year to claim long-term capital gains (LTCG) exemption.


The government decided to crack down on such sham transactions after the Special investigation teams (SIT) on black money suggested a mechanism to detect shell companies and put in place checks and balances to curb stock market abuse.


In the last three years, the I-T department has identified over 1,155 shell companies which were used as conduits by over 22,000 beneficiaries. The amount involved in non-genuine transactions of such beneficiaries was over Rs 13,300 crore.  So far, the I-T department has launched criminal prosecution complaints against 47 persons. The SFIO, too, has undertaken the exercise of preparing comprehensive digital database of shell companies and their associates. Based on the SFIO report, the MCA has removed 162,618 companies from the Registrar of Companies.

Companies and financial institutions mop up close to Rs 56,000 crore by way of fund raising through equities

Companies and financial institutions have mopped up close to Rs 56,000 crore by way of fund-raising through equities so far in 2017. This is about 20% higher than the amount of Rs 46,733 crore raised in 2016.

Companies and financial institutions have mopped up close to Rs 56,000 crore by way of fund-raising through equities so far in 2017. This is about 20% higher than the amount of Rs 46,733 crore raised in 2016. The fund-raising has been helped by a booming stock market; the Sensex has gained by 22% in the year so far.

On Monday, the benchmark gauge closed at 32,514.94.The Nifty has put on 23.10% in 2017 closing Monday’s session at 10,077.10.Since the beginning of the year, firms have mopped up Rs 55,905 crore through initial public offerings (IPO), offers for sale (OFS), Qualified Institutional Placements (QIP), and rights issues among others, data from Prime Database showed.

A significant portion — close to 61% — of the total equity raised this year has been by way of QIPs at Rs 34,182 crore. State Bank of India (SBI)’s Rs 15,000 crore offer has been the biggest in 2017 so far — the lender had issued around 52.21 crore new shares at a price of Rs 287.25.

The issue was aimed at augmenting the bank’s capital adequacy ratio and for general corporate purposes.This is the highest in the past eleven years. Banks constituted 84% of the amount raised through QIPs.

Market participants said the need for Tier 1 capital and the necessity to meet Basel III requirements as the reasons for banks opting for QIPs.

After QIPs, the maximum amount of money was raised through IPOs in 2017.

In 2017, companies raised Rs 14,026 crore through IPOs. Listing gains and returns by newly listed companies as also the positive sentiment in the broader market are among the reasons attributed to the trend.

BSE, HUDCO, CDSL, Avenue Supermarts, Shankara Building Products and S Chand and Company are some of the companies who completed their IPOs in the last seven months.

The newly listed companies have given good returns to investors, the BSE IPO index a gauge of newly listed companies rose by 40% year to date.

Small enterprises raised Rs 716 crore through SME IPOs, this is the highest since 2012.

Market participants said the buoyancy in the primary market is set to continue with more than a dozen companies gearing up to hit the market with their offerings.


Source: http://www.financialexpress.com/market/companies-and-financial-institutions-mop-up-close-to-rs-56000-crore-by-way-of-fund-raising-through-equities/788648/

Capital gains tax evasion under CBI scanner

The Central Bureau of Investigation (CBI) is probing if any government officials were involved in misusing stock exchange platforms to benefit from the long-term capital gains tax (LTCG) exemption.

According to sources, CBI officials visited the headquarters of the Securities and Exchange Board of India (SEBI) in Mumbai to get relevant files pertaining to LTCG cases probed by the markets regulator.

This comes at a time the income tax (I-T) department is probing the entities which had allegedly misused capital gains provisions to evade taxes worth Rs 34,000 crore.

Gains made from the sale of shares held for more than a year are exempt from taxes.

According to sources, the CBI is trying to gather information if any government official made any undue gains by being the end-beneficiaries. “We have collected some relevant documents along with transaction trails with regard to the companies that appeared to have misused the trading platforms to evade taxes. We suspect that there are high chances of government officials being involved, especially as end-beneficiaries,” a CBI source said. “The undue advantage could be hidden and may have been done in a multi-layered arrangement, which needs to be identified.”

Sources said the central agency was in the process of vetting the documents and would accordingly take a call on registering a case against the suspected beneficiaries.

The issue is critical as a few instances of abuse have been reported despite several measures taken by the regulator and the bourses. The intensity of the matter has raised the probability of revocation of capital gains benefits.

So far, investigations by the SEBI revealed that 11,000 entities have bought shares of more than Rs 5 lakh each in the past three years in listed firms that might not have any business operations. The SEBI has identified these entities using data analytics and trading and surveillance data.

The probe suggests that such deals were aimed at evading capital gains tax by showing the source of income as legitimate from stock markets. The so-called losses, actually bogus losses, are showed in the books to offset the same against capital gains.

The modus operandi is thus: Operators advise beneficiaries to invest in the listed companies, which allot shares on preferential basis at a nominal rate. These shares are under a lock-in period for a year.

Subsequently, these operators manipulate the scrip. They also rope in entities to provide the “last traded price” to book LTCG and also to buy shares at a higher price. The beneficiary pays cash to the operator through a multi-layered structure from the gains made by evading taxes.

The markets regulator had reservations that the cases were about tax evasion, which do not fall under its purview. However, if share prices were manipulated, it could proceed under section 11B of the SEBI Act, which allows it to impound the sale proceeds.

It also pointed out that the evidence provided by the tax department was not sufficient to establish connections between promoters of companies, beneficiaries and the “last traded price” and “exit” providers.

Source: http://www.business-standard.com/article/markets/capital-gains-tax-evasion-under-cbi-scanner-117062100019_1.html

SEBI plans stricter norms for Independent Directors

Markets watchdog Securities and Exchange Board of India (SEBI) plans to overhaul the regulatory framework for corporate governance, including appointment and removal of independent directors, people familiar with the matter said.

Besides, a high level panel is looking at corporate governance issues such as those pertaining to related party transactions, auditing and effectiveness of board evaluation practices, the people added.

Against the backdrop of recent instances of boardroom battles involving large corporates, the SEBI is looking to revamp the norms and the matter is expected to be discussed at its board meeting later this month.

Strengthening corporate governance practice is a focus area for the regulator, with SEBI chairman Ajay Tyagi recently saying, “independent directors are not independent”.

The regulator is keen on stricter norms for independent directors, including with respect to their appointment, removal and larger responsibility as part of a company’s board, the people said.

Currently, an independent director can be removed by way of an ordinary resolution — which requires the approval of at least 50 percent shareholders of a particular company.

However, when it comes to re-appointment of independent directors, the firm concerned has to move a special resolution under which nod from 75 percent or more shareholders is required.

According to sources, SEBI wants to make it special resolution mandatory for removal of an independent director as such a provision will reduce the arbitrariness of promoters in deciding upon the ouster of such directors.

Besides, stringent disclosure requirements for independent directors, including at the time of their appointments, are being looked at, sources said.

Corporate governance issues will be among the slew of developments that are to be discussed during the SEBI board meeting scheduled for June 21.


Earlier this month, the watchdog set up a 21-member committee under the chairmanship of veteran banker Uday Kotak to suggest ways to further improve corporate governance standards of listed companies.

The panel will make recommendations on ensuring independence in spirit of independent directors and their active participation in functioning of the company.

Besides, measures to address issues faced by investors on participation in general meetings and ways for improving effectiveness of board evaluation practices will be suggested by the committee.

Apart from Kotak, who is the chairman of Kotak Mahindra Bank, other members include HDFC CEO Keki Mistry, Wipro chief strategic officer Rishad Premji, L&T Whole Time Director R Shankar Raman and BSE CEO Ashishkumar Chauhan.

In April, Tyagi had said there were too many lacunae with respect to the concept of independent directors with many having “no commitment to any cause”.

“I must admit I have no solutions on what should be done but it will be anyone’s case that existing system has lot of lacunae,” he had said.

Some independent directors are appointed at the mercy of promoters “(with) no prescribed qualifications or procedures, favouritism, (many are from) closed clubs (such as) only those people being in all boards, no commitment to any cause – Ajay Tyagi, Chairman, SEBI


Earlier this year, the regulator came out with detailed corporate governance norms for listed companies that provide for stricter disclosures and protection of investor rights, including equitable treatment for minority and foreign shareholders.

The new rules, which would be effective from October 1, require companies to get shareholders’ approval for related party transactions, establish whistle blower mechanism, elaborate disclosures on pay packages and have at least one woman director on their boards.

Source: https://www.bloombergquint.com/law-and-policy/2017/06/12/market-regulator-sebi-plans-stricter-norms-for-independent-directors

SEBI set to block P-Note route for NRIs to prevent laundering of black money

The regulator wants to tighten the rules amid concerns that various variants of P-Notes have been floated since the implementation of GAAR on April 1.

The regulator plans to put in place a clear bar on non-resident Indians (NRIs) and entities owned by them and resident Indians subscribing to participatory notes, a move aimed at preventing possible round-tripping or laundering of black money.

The Securities and Exchange Board of India (SEBI) is set to tweak its regulations to this effect at its upcoming board meeting on April 26 after the finance ministry recently wrote to the regulator. Such a restriction is already implied through the answer to a frequently asked question (FAQ) but the regulator feels this lacks legal sanctity.

“Most of Sebi’s FAQs themselves clearly state that they should not be regarded as interpretation of law, and that they should not be treated as a binding opinion or guidance from SEBI,” said Moin Ladha, associate partner, Khaitan & Co. “Therefore, in case of any contradictions between the regulations and FAQs, the regulations would prevail. While FAQs do indicate the position SEBI is taking, they cannot be said to override or expand the scope of the regulations.”

P-notes are a derivative instruments issued offshore to those who want to bet on the country’s stocks and bonds without registering themselves with SEBI. The regulator wants to tighten the rules amid concerns that various variants of P-notes have been floated since the implementation of General Anti Avoidance Rules (GAAR) on April 1.

Investments via P-notes had declined to a 43-month low of Rs 1.57 lakh crore in December but rebounded in January to Rs 1.75 lakh crore before dropping again to Rs 1.70 lakh crore in February. There could be a resurgence in P-note issuance as these are exempted from capital gains tax under the amended tax treaties with Singapore and Mauritius that took effect on April 1.

Legal experts said the concept of NRI itself is a grey area and defining it would be crucial for regulators. They said the prohibition should be strictly enforced to prevent round-tripping of Indian money. “The concern of round-tripping of Indian money, particularly when leading industrialists may have a foreign passport, was always a concern,” said Sandeep Parekh, founder, Finsec Law Advisors. SEBI relies on the income tax definition on what constitutes an NRI.

“The concept of who is an NRI itself is a grey zone ranging from income tax definition which is based on residency to citizenship laws which are typically drafted very broadly to include any person of Indian origin and their kith and kin who are born abroad,” Parekh said. “Defining an NRI within this spectrum would be crucial to allow legitimate money in from immigrants who have left India several generations ago and are doing exceedingly well.”

In recent discussions with a leading custodian, the latter gathered the impression that the regulator was not comfortable with NRIs as a group holding a majority interest in a Category II foreign portfolio investors (FPIs) even though regulations do not restrict this. Rules require Category II FPIs to be broad-based — the minimum number of investors should be 20 and no single investor can hold more than 49%. However, NRIs as a group cannot hold more than 49% in Category III FPIs.

Source :  http://timesofindia.indiatimes.com/business/india-business/sebi-set-to-block-p-note-route-for-nris-to-prevent-laundering-of-black-money/articleshow/58215743.cms

Public investors make big bucks on D-Street even after PE exits

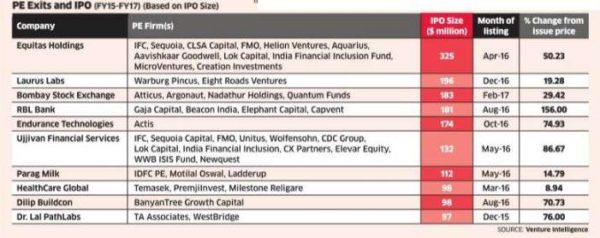
Private equity investors make big money in IPO exits. This is well known. But what is less known is that retail and other investors have also been making decent money after the exits. The largest IPO exits in the last three years made 1-14 times returns for private equity firms. But after listing, retail, HNIs and institutional investors have gained 9-156% in these firms, thanks to a strong stock market, data from Venture Intelligence show.

If the market rises further, the gains will only increase and private equity-like, super sized returns may still be possible. Investment bankers attribute this to the rising interest in equity market as well as strong fundamentals. “Stocks being valued attractively and appetite for IPOs have helped these companies,“ said Dharmesh Mehta, MD, Axis Capital. Financial stocks have obviously beaten the rest with RBL Bank surging 156% since listing in August 2016 followed by Ujjivan Financial Services with a gain of 87%.

Other gainers include Dr Lal PathLabs which has jumped 76% and Dilip Buildcon which has moved up 71%. In FY17, PE firms sold their complete stakes in 14 IPOs, as compared to 16 in FY16 and seven in FY15. According to Ajay Saraf, executive director, ICICI Securities, a PE exit augurs well for investors as the company could be expected to have better corporate governance and better fundamentals.

PE firms usually enter into sectors that have potential to do well and this gives comfort to investors while buying these stocks, said Saraf. “The PE exit trend is likely to gain further momentum going ahead,“ added Saraf.

Source:  http://economictimes.indiatimes.com/articleshow/58157676.cms