Qualified accounts can be flagged on the ministry’s portal, thereby, helping regulators to keep a check on suspicious entities
The ministry of corporate affairs (MCA) says work has begun for an “early warning system” regarding shell companies.
The term is used to refer to a company without active business operations or much of assets. This by itself isn’t illegitimate but they could be used as a manoeuvre for financial operations of a suspect or illegitimate nature.
Currently, there is no way to check shell companies systemically, an official said. Chartered accountants (CAs) do come out with qualified accounts of such companies but these come in a random way on the ministry’s MCA21 portal. Qualified accounts refer to bits of information about which CAs have doubts or disagreement with the audited entity’s management.
After the hoped-for early warning system comes, qualified accounts would be flagged on the ministry’s portal, helping it and other regulators to check on such entities. “We are yet to work out the nitty gritty of this system but are on the job,” another official said.
He said this would do away with the current system of random inspections to identify such companies. The portal will have filings by CAs in such a way that regulators will be alerted, he said.
Earlier, minister of state for corporate affairs P P Chaudhary had said the government would try to use the information technology tool of artificial intelligence in this regard.
CAs told Business Standard that an early warning system by itself wouldn’t change things by much. There should also be stringent norms to make auditors more independent. One of them said it is a company’s promoters who appoint the auditor, which means the latter does not retain the independence to openly report facts. So, a CA’s appointment would need to move away from promoters.
The ministry had recently issued rules to limit the number of subsidiaries a company may have — no more than two layers. This will apply prospectively but existing companies have to disclose details of their entire list of subsidiaries to the registrar of companies within 150 days. Banks and insurance companies are excluded from this rule.
With no limit on the number of subsidiaries, regulators found it difficult to track illicit transactions.
A multi-agency clampdown has begun on shell companies to tackle the black money menace wherein the role of auditors has come under the scanner for alleged connivance in facilitating illegal transactions.
The auditors’ role is also being looked into for not raising the red flag as several cases have come to the fore, including at listed companies, for alleged mismatch in financial statements, sharp erosion in net worth, siphoning off funds to group and promoter entities, sources said.
Stepping up the vigil, the corporate affairs ministry as well as Sebi and other regulatory authorities are keeping a close tab on activities carried out by shell companies.
Sources said regulatory agencies are examining the role of auditors to ascertain whether they were also involved in suspected illegal activities.
The ministry as well as Sebi are closely looking at the functioning of auditors in various companies, especially those that have not been carrying out business for long. After a detailed analysis, the authorities would decide on the next course of action, sources added.
Auditors, who have greater responsibilities under the Companies Act, 2013, are required to ensure that financial statements of a company are proper and can red flag dubious transactions.
As part of larger efforts to fight illicit fund flows and tax evasion, the ministry has already struck off the names of over two lakh companies from the records and further action is expected.
Besides, Sebi has taken against 331 listed entities that are suspected shell companies. While the watchdog had imposed strict trading restrictions on these scrips, curbs have been eased in some cases after the companies went on appeal against Sebi’s move.
On Tuesday, the government said more than 1.06 lakh directors would be disqualified for their association with shell companies.
The ministry, which is implementing the companies law, has also identified professionals, chartered accountants, company secretaries and cost accountants associated with the defaulting companies.
Besides, such people “involved in illegal activities have been identified in certain cases and the action by professional institutes such as ICAI, ICSI and ICoAI is also being monitored”, an official release said on Tuesday.
Separately, authorities are looking at the possibility of having stricter scrutiny of global auditing firms to make them more accountable with such auditors coming under the lens in various corporate misdoings.
A big area of concern pertains to the big guns seeking to wash off their hands whenever their names crop up in any accounting wrong-doing while their delaying tactics in the name of jurisdiction have also been noticed, an official had said earlier.
While the existing legal framework provides for stringent provisions for auditing activities, there is no specific system in place when it comes to overseas audit firms.
While discussions on having tighter regulations for foreign audit firms are going on, the ministry is already examining the recommendations of the 3-member expert panel on various issues related to audit firms amid concerns over certain practices circumventing regulations.
The expert panel, headed by Teri Chairman Ashok Chawla, had submitted its report in March this year.
Enforcement action by the income tax department will be reserved for cases where specific tip-offs regarding large-scale tax evasions have been received
The income tax department will maintain the number of income tax returns (ITRs) chosen for scrutiny at the current level of less than 1% of all returns, in spite of a surge in individual tax filings to keep the process non-intrusive and taxpayer-friendly.
Gentle persuasion through text messages, emails and advertisements will remain the department’s main ways of interacting with taxpayers, while enforcement action will be reserved for cases where specific tip-offs regarding large-scale evasions have been received.
Out of the 52.8 million income-tax returns filed for the 2015-16 fiscal year, only about 300,000 cases, or around 0.6%, were scrutinized, a person privy to the deliberations within the tax department said on condition of anonymity.
“Even when the number of our assessees grow, scrutiny will be limited to this level—250,000-400,000 cases. It will always be less than 1% of returns received. We are absolutely non-intrusive to almost everyone. Even in most of the cases scrutinized, we do not hold searches or surveys,” the person cited above said, adding that the income-tax department vests its faith in taxpayers.
Searches conducted by the tax authorities—about 600 such cases happen in a year—will also stay at this level in future. “Only when we get very, very specific information of tax evasion of a substantial amount, we take enforcement action,” said the person.
The department recently sent 17 million text messages to individuals urging them to file returns for fiscal 2017 before the due date of 5 August, said the official.
This has led to a 25% jump in personal income-tax return filings for fiscal year 2016-17 to 27.9 million before the due date compared to the same period in the previous year.
Going by past trends, this figure could rise to about 66 million returns by the end of March 2018. Returns for a particular fiscal year can be filed by the end of the next year, called the assessment year, with interest on tax dues if any.
Close to three-fifths of the 52.8 million returns the department received for 2015-16 had come in after the due date in August 2016.
“Engaging with people through electronic means is easy and is a better strategy to ensure compliance than scrutinizing more tax returns. It is important for taxpayers to meticulously keep a record of their financial matters to remain compliant,” said Rahul Garg, a partner at consulting firm PwC India.
The income-tax department is also processing refunds faster. It has started issuing refunds within 10 days to taxpayers who have met the 5 August deadline for filing returns.
Individuals who make large purchases, such as houses, or cars priced above Rs10 lakh, but do not file income-tax returns figure among those who receive gentle reminders to file their returns as the authority secures information about such transactions from other sources.
Linking the permanent account number (PAN) used in filing tax returns with Aadhaar, the 12-digit number issued by Unique Identification Authority of India that identifies individuals using biometrics, is also enabling officials to check if the investments and spending of income-tax assessees are in line with their known sources of income.
So far, 94 million PANs have been linked with Aadhaar numbers after the central government made quoting the unique identification number compulsory for the filing of income-tax returns from July onwards.
According to RBI data, PSU banks in FY17 have written off Rs 81,683 crore against Rs 2.49 lakh crore in the past five years.
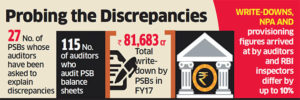
The Reserve Bank of India (RBI) has questioned scores of auditors at 27 public sector banks on the process and logic they had used to compute and report write-downs at the lenders, two people close to the development told ET.
The RBI has sought written explanation on differences in the write-down assessments by its own inspectors and those certified by the auditors. A write-down is a reduction in the estimated and nominal value of an asset, and is charged off as a loss to the profit and loss account for the relevant period. In some cases, the RBI has also questioned the provisioning methodology and non-performing asset (NPA) figures arrived at by the auditors at a few public sector banks, sources told ET.
The banking regulator is examining whether auditors at these state-run lenders followed RBI guidelines on write-downs, provisioning and NPAs. “This is part of RBI’s annual assessment. Auditors will have to explain how they provisioned for NPA and how they calculated write-downs,” said a person aware of the matter.
The write-downs, NPA and provisioning figures arrived at by the auditors and RBI inspectors differ by up to 10%.
WRITE-DOWNS & PROVISIONING
According to RBI data, PSU banks in FY17 have written off Rs 81,683 crore against Rs 2.49 lakh crore in the past five years. In a few cases, the audit reports of some of these lenders do not reflect these write-downs, said one of the persons cited above. Most banks do not separately report write-downs in their accounts, combining them often with quarterly provisioning.
Most Indian public sector banks use more than one auditor due to the enormous size of their balance sheets. Most auditors are mid-to-small Indian firms that audit several branches. The 27 public sector banks collectively employ 115 auditors, according to data analysed by the ET Intelligence Group.
According to the people in the know, auditors at State Bank of India, Punjab National Bank, Bank of Baroda, Canara Bank, Allahabad Bank and Bank of India (BoI) were sent the show-cause notices about two weeks ago.
ET’s detailed email queries to the regulator and the affected lenders – SBI, PNB, BoB, IDBI, Indian Overseas Bank, Canara Bank, BoI, Oriental Bank of Commerce (OBC) and Allahabad Bank – did not elicit any response.
REGULATOR HAS PRIVILEGED ACCESS’
According to a major bank’s auditor who did not wish to be identified, the differences are not unexpected. “The RBI has access to information an auditor may not. Like, if a loan in bank X has gone toxic, the auditor of bank Y may not know, but the RBI would,” he said. He added that there is a time lapse between auditors preparing an account and the RBI conducting inspections. “What you must look at is the impact on the P&L of a bank due to divergence. In most cases, that is not much,” he said.
To be sure, there may have been ‘technical’ errors in interpreting the writedown rules, resulting in the differences. “There is a direct impact of the new accounting standards on the way write-downs are arrived at,” said a senior executive at a top audit firm. “Under the old accounting system, the rules around write-downs were not as precise, and there is a possibility that some auditors may have ignored this.”
For decades, Sugal & Damani Group focused on lotteries before it entered the online bill payment business with Payworld.
Now, it has become a GST service provider (GSP), an entity that will help businesses register, upload electronic invoices and file on the technology platform, and plans to leverage its network.
Pune-based Vayana Network has been working with small and medium enterprises (SMEs) to arrange funds and has no experience of taxation, but it too has become a GSP and is eyeing business from companies, their vendors as well as standalone SMEs.
Besides GSPs, GST has given birth to another set of entities called ‘application service providers’ or ASPs that will use sales and purchase data from taxpayers and convert it into GST returns for filing online.GST is spawning a $2 billion-3 billion (Rs 13,000 crore-20,000 crore) industry comprising software service providers, ASPs and GSPs, chartered accountants and consulting firms as the entire industry is undergoing business process re-engineering.
SAP and Oracle, the big daddies of the ERP business, may mop up revenues of at least $1 billion (Rs 6,500 crore) over the next two years, industry players say.
Homegrown Tally Solutions, which has close to 11 lakh users of its accounting software, has already got around six lakh subscriptions from businesses, which entitles them to free upgrades and access to all information.
While the cost of software varies between Rs 18,000 and Rs 54,000, each annual subscription fetches the company Rs 3,600 (for a single user) to Rs 10,800 (multiple users).
With 10,000 melas planned in the next one month, the company is out to garner as much business as possible while helping businesses tackle GST, said Tally Systems executive director Tejas Goenka.
Even a smaller player like the newly set up Ginesys is eyeing a turnover of around Rs 100 crore in three years, said co-founder Ashish Mittal. Then, there are the likes of ClearTax, which was set up to file income tax returns. Sensing a huge business opportunity it has expanded into the GST arena with its software and tie-ups with around 10,000 chartered accountants, said ClearTax founder CEO Archit Gupta.
Not surprisingly, companies have hired big time to meet the required demand. SAP and its partners have around 500-600 people working on implementing ERP solutions, business filing, supply chain and the app for filing returns, said Neeraj Athalye, who leads the firm’s GST adoption drive. Cleartax has hired around 400 in the last one year or so.The big four accounting firms too have ramped up. Deloitte’s indirect tax team has around 250 new recruits, while PwC has expanded its pool of CAs and systems executives by 200-250. While the billing for large companies runs into crores, including consulting services, the smaller companies are banking on volumes with some charging a fee of as low as Rs 100-200 a month for filing returns.
The fate of three near-bankrupt steel companies — Essar Steel, Bhushan Steel and Electrosteel Steels — which together owe lenders nearly Rs.1 lakh crore will now be decided by the National Company Law Tribunal (NCLT).
The fate of three near-bankrupt steel companies — Essar Steel, Bhushan Steel and Electrosteel Steels — which together owe lenders nearly `1 lakh crore will now be decided by the National Company Law Tribunal (NCLT). Having failed to recover their dues or rope in either strategic or financial investors, lenders to these companies finally agreed on Thursday to resort to the Insolvency and Bankruptcy Code (IBC), bankers familiar with the development said. The decision follows a directive by Reserve Bank of India (RBI) on June 13 to banks asking them to refer a dozen troubled companies — with a combined debt of close to Rs.2.4 lakh crore — to the tribunal.
Corporate watchers said a new chapter was unfolding for India Inc, traditionally unfamiliar with insolvencies and, more often than not, able to wrangle concessions and bailouts, often with the help of those in power. Both the RBI and the government are attempting a speedy resolution to the problem of non-performing assets (NPAs) that is paralysing banks and stymieing investments.
While it has been known for several years now that many of the country’s top corporates are financially fragile, it was former RBI governor Raghuram Rajan who first forced banks to accept the reality and classify assets correctly in December 2015.
Bankers have been given a fortnight within which to move the tribunal. Among the other companies that have been refereed to the NCLT are Jyoti Structures, Lanco Infratech, Monnet Ispat and JP Infratech. The 12 accounts identified by the central bank are those to which banks have an exposure of more than Rs 5,000 crore, more than 60% of which has been recognised as NPAs. Once these cases are with the NCLT, the lenders need to set up a committee of creditors that will come up with a plan on how the asset will be tackled. If the committee is unable to find a solution within 180 days — this can be extended to 270 days — the borrowing entity will go into liquidation.
The three steelcos — Essar, Bhushan and Electrosteel — together have a manufacturing capacity of close to 18 million tonnes per annum. The total debt of the Essar Group is estimated at Rs.1.17 lakh crore. Most private banks have sold off their Essar Steel exposure to asset reconstruction companies, taking a haircut of more than 50%; most PSU banks have declared Essar Steel an NPA.
Essar Steel, promoted by the Ruias, had at a meeting last year requested banks to convert Rs.12,200 crore of loans into preference capital and equity shares.
While Rs.9,000 crore was sought to be converted into preference shares, to be redeemed after 12-18 years, the company had requested the remaining Rs 3,200 crore be converted into common equity. For the balance Rs 31,800 crore, the company had sought a prolonged repayment period. Senior bankers had told FE such a deep restructuring proposal, if approved by the consortium, would amount to taking a haircut of nearly 30%.
Bhushan Steel, promoted by the Singals, has been unable to service its loans for several years now thanks to the stress on cash flows, partly the result of large steel imports into the country which drove down prices. While banks had been monitoring the company’s operations and financials, they were unable to come up with a solution. In August 2014, a senior company executive was arrested around the time the former chairman and managing director of Syndicate Bank SK Jain was arrested in an alleged case of bribery.
In the case of Electrosteel Steels, banks decided to initiate a strategic debt restructuring, with a view to roping in a new investor and beefing the equity capital of the company. However, despite many attempts, banks were unable to find a buyer within the stipulated 18 months, and were compelled to classify the account as an NPA.
State Bank of India seeks applications for empanelment, sets stiff conditions
The Reserve Bank of India’s (RBI’s) move to push 12 large non-performing assets (NPAs) of the banking system into the insolvency process has created a massive business opportunity of up to Rs.2,500 crore for insolvency professionals.
To put the numbers in perspective, the RBI list comprises four companies with dues of over Rs.35,000 crore each. Even if one puts together all the few hundred cases handled by the six-month old framework, it would be a struggle to cross Rs.20,000 crore.
While the huge influx is likely to test the capacity of most players who are literally months old in the profession and present a steep learning curve, it will be a great stimulus for entry of stronger hands and investment in the segment.
According to the insolvency law, the entire process of corporate insolvency needs to be managed by a resolution professional appointed by a committee of creditors. The resolution professional, who will effectively become the chief executive officer of the business during the process period of 180 days, can charge a fee for his services. Besides, banks are also looking to appoint insolvency professionals to populate committees of creditors, which need to be formed for each of these companies.
With over Rs. 2.5 lakh crore debt coming in the top 12 companies in the first list, a one per cent charge works out to Rs. 2,500 crore. While this would be a ballpark figure, regulations do not prescribe a limit or range of fees, leaving a free hand for market forces. Globally, insolvency professionals work on various structures such as a fixed fee, time and effort-based charges, or a percentage of realisation. In some cases, a combination of these three methods could also be used. Banks would have pricing power, but good insolvency professionals would have their levers to charge a decent number, given the complexities involved and short supply.
Pavan K Vijay, managing director of Corporate Professionals, a Delhi-based firm that is looking at this opportunity, says the move gives a big boost to the nascent profession. “Even if the one per cent number does not work out, as there are bound to be negotiations, it could be around Rs.1,500 crore to Rs.2,000 crore. It is not small.”
The State Bank of India (SBI), the country’s largest lender, which also has the lion’s share of these 12 large accounts, has begun the process of empanelling insolvency professionals by issuing advertisements recently.
“The bank (SBI) seeks to empanel IRPs (insolvency resolution professionals) as resolution professionals in applications filed before the National Company Law Tribunal for resolution and/or liquidation proceedings, including for representing the bank in the committee of creditors as per the provisions of the code/and the regulations,” said the advertisements issued early last week.
Other banks are likely to follow similar processes in selecting insolvency professionals, as the public sector is generally process driven, regulatory officials say.
According to the Insolvency and Bankruptcy Board of India (IBBI) website, there were some 977 registered insolvency professionals in the inaugural limited period criteria and another 350 in the regular category, which requires passing the national insolvency examination. Lawyers, chartered accountants, and company secretaries form a majority. However, not all of them might be able to handle the large mandates. Given the large accounts it handles, the SBI has set stiff eligibility criteria for the applicants. It wants people with experience in debt restructuring, who are also experts in company law, etc. The application window closes early next week. Since the big accounts bring with them a lot of complexities, individual professionals might not be able to handle the entire task, Vijay said.
Several top lawyers such as Shardul Shroff and Pallavi Shroff of Shardul Amarchand Mangaldas, Alok Dhir of Dhir & Dhir, Bahram Vakil and Dushyant Dave are among the registered insolvency professionals. These would have established infrastructure and people to support their functions.
Also, the insolvency law provides for Insolvency Professional Entities (IPEs), which are corporate structures where two or more professionals can come together as partners or directors. However, there are only seven such registered IPEs as of today, according to the IBBI website. These are IRR Insolvency Professionals, a firm floated by Delhi-based lawyer Alok Dhir, AAA Insolvency Professionals, Witworth Insolvency Professionals, Gyan Shree Insolvency Professionals, A2Z Insolvency Services, Turnaround Insolvency and Nangia Insolvency Professionals.
Sandeep Gupta of Witworth, which is already handling a few mandates, feels while the opportunity is big, capacity and capabilities also need to be built up. “It is the beyond the means of an individual to handle a book size of several thousand crores. A company of such a size would have numerous non-financial creditors as well. These need to be handled in a given time frame. The resolution professional would need adequate support in terms of people and infrastructure,” he said.
For instance, Gupta said, he might hire a few freelance chief financial officers to manage one of the big accounts. Considering all this, calculating fee on a percentage basis could be misleading. It should be calculated, based on time and effort put in by the insolvency professional, he argued.
The SBI advertisement asks applicants to provide “tentative fees proposed to be charged” for various roles such as interim resolution professional, resolution professional on behalf of the committee of creditors or for being appointed as an insolvency professional to represent the bank in the committee of creditors. The bank also wanted to know whether the applicant would be “willing to abide by the fees decided by the bank.”

 He said this would do away with the current system of random inspections to identify such companies. The portal will have filings by CAs in such a way that regulators will be alerted, he said.