GST 2.0: What changed at the recent GST Council meeting – rates, processes and what it means

GST Council, has recommended to reduce / waive the interest/ late fee for delayed filing of GSTR 3B by small taxpayers (having turnover upto Rs. 5 crores) for the tax period from July 2017 to July 2020
The GST Council has announced major rate cuts and compliance reforms in its September 2025 meeting. Highlights of new GST slabs, effective dates, process changes, and how businesses should prepare.

India’s GST system just received its biggest shake-up since rollout: the GST Council approved a major rate rationalisation (moving to a much simpler slab structure), together with a package of taxpayer-friendly process reforms. The changes – aimed at reducing complexity, lowering prices for many everyday goods, and speeding up compliance/refunds for businesses – are to be implemented from 22 September 2025 (with a few exceptions and phased rollouts). Here’s a clear, practical, and source-backed breakdown of what happened, why it matters, and what businesses and consumers should expect next.


Main Highlights

  • Two main GST slabs: 5% (merit/essential) and 18% (standard) — the 12% and 28% slabs are being collapsed into these. A special de-merit 40% rate is proposed for a small set of luxury/sin goods (tobacco, very high-end vehicles, etc.).


  • Implementation date: Most changes effective 22 Sept 2025 (Navratri start). Tobacco/pan masala items will have separate timing. Some elements may be phased to manage compensation fund impacts.


  • Process reforms: Faster/automated registration for low-risk businesses, pre-filled returns, auto/refund acceleration, risk-based provisional refunds for exporters and a timeline to operationalise many tech changes.


  • Anti-profiteering approach: legal anti-profiteering machinery (Section 171) hasn’t been reinstated in an aggressive form — the government is asking industry to pass on benefits while monitoring and states are pushing for safeguards. Expect guidance from tax authorities.


What exactly changed – the rate map (summary)

The Council rationalised slabs to simplify compliance and broaden the “common man” gains.

  • 5% slab — Will cover a large set of essentials, many medicines/healthcare inputs, basic food items and several household staples and smaller consumer items previously at 12%/18%. (Examples reported: roti, many edible goods, certain medicines and diagnostic kits, small household appliances in some categories).


  •  8% slab — The standard rate now for most manufactured goods and many services previously at 18%/28%/12% where reclassification makes sense (e.g., many auto components, some consumer durables moved to 18%).


  • 40% de-merit slab — A higher, selective rate for luxury and sin goods (tobacco products, very high-end cars, other items identified by the Council). These are explicitly carved out to preserve revenue and to tax dis-incentivise harmful/very high-end consumption.


Implementation mechanics & phasing

  • Effective date: The Council recommended implementation from 22 September 2025 for most goods/services. Tobacco and tobacco-related items will have separate treatment (different effective date to be notified) because of compensation cess and administrative considerations. Some elements (especially where compensation cess/compensation fund is concerned) may be phased to smooth state receipts.


  • Why phased? Several states flagged potential revenue loss concerns; the Council stressed consensus but also acknowledged fiscal impacts and decided to manage timing and the compensation cess account accordingly. Expect circulars from CBIC explaining exact implementation steps (tariff notifications, HSN crosswalks, valuation/credit rules). 


Process reforms (big ticket operational changes)

The meeting wasn’t just about rates – there’s a parallel package to make compliance quicker and less painful:

  1. Automated/simplified registration for low-risk applicants (target: 3 days/automated approval for eligible applicants). This aims to cut onboarding friction for SMEs and startups.


  • Prefilled returns & auto refunds — prefilled return architecture and auto refunds (including provisional/90% provisional refunds for exporters based on risk evaluation for specific sectors) to speed liquidity to business. Rollouts/timelines were announced — many measures to be operationalised by October–November 2025.


  • Faster refund windows (seven-day targets for specific exporters/priority cases) and risk-based provisional mechanisms to reduce stuck refunds.


  • Tribunal and dispute reforms — strengthening appellate/ADR mechanisms (e.g., national benches for Advance Rulings) to improve consistency in rulings.

These process reforms are intended to complement rate rationalisation so taxpayers – especially MSMEs and exporters — face lower compliance cost and faster cash flows. 


Anti-profiteering and price transmission

  • The Council/officials have made it clear that industry is expected to pass benefits of lower GST to consumers. The strict anti-profiteering law (Section 171) hasn’t been robustly re-invoked as a new enforcement blitz, but states have insisted on safeguards and monitoring. Tax authorities and state governments will watch prices and may ask for evidence of benefit transmission; businesses should act cautiously and transparently. 

Practical tip for retailers/manufacturers: document the cost/repricing methodology, issue credit notes where appropriate and update pricing policies — this is both good business practice and a defensive step in case of state queries.


Sectoral winners and losers — who gains, who pays more

  • Likely beneficiaries (cheaper): FMCG staples, many food items, certain medicines & diagnostic reagents, entry-level autos and components, many household goods and some construction materials (cement, tiles — reported moves from 28→18% / 12→5% for specific items). These cuts will help consumer demand and reduce input costs for industries like housing and consumer durables. 


  • Likely paying more / targeted up-taxed: Very high-end cars, tobacco & pan masala, certain luxury goods moved into the 40% de-merit slab (aim: revenue neutrality and disincentive). 

Stakeholder notes: Auto dealers, consumer durables firms and textiles have broadly welcomed the move as demand stimulative; states with manufacturing-heavy revenue bases have flagged short-term revenue pain and asked for compensatory arrangements. 


How decisions were made (short explanation of the Council process)

  • The GST Council is a constitutional body (Article 279A) that makes recommendations on rates and other GST matters. Decisions are taken with a weighted voting mechanism (Centre has one-third weight, states two-thirds) and normally by a three-fourths weighted majority — but in practice the Council aims for consensus. The 56th meeting reported unanimous consensus on the package. 

What to watch next

  • Notifications from CBIC/CBIC circulars giving precise tariff/HSN crosswalks, valuation rules and timeline for phased items. (Those will be the legally binding documents.) 


  •  State responses about compensation/temporary support if they claim revenue shortfalls — any fiscal transfers or special measures will be announced in coming weeks.


  • Price monitoring: watch for state consumer affairs departments and tax authorities asking firms to show price transmission evidence.


Final take

This is a large, pro-consumer and pro-growth move designed to simplify GST’s complexity and spur demand ahead of the festive season — while also modernising the compliance stack (faster registration/refunds). It’s politically significant (broad consensus) and technically big — businesses should act fast to align systems, pricing and documentation. States’ fiscal positions will be the main political/implementation watchpoint, so expect more operational clarifications from CBIC in the coming days.


Government waives late fee for delayed GST filings

The Central Board of Indirect Taxes and Customs (CBIC) announced a waiver of late fees for delayed filings of reconciliation statements and annual returns (GSTR-9C) for the financial years 2017-18 to 2022-23. Taxpayers must file the reconciliation statement by March 31, 2025, to avail the waiver.

The Central Board of Indirect Taxes and Customs (CBIC) Thursday announced a waiver of late fees for delayed filings of reconciliation statements and annual returns for the financial years 2017-18 to 2022-23.

The Ministry of Finance has issued a notification relevant for Goods and Service Tax (GST) registered taxpayers who failed to file the annual reconciliation statement through the GSTR-9C form.


As per the circular eligible GST taxpayers now have an opportunity to get a waiver of any pending late fees for filing GSTR-9C for FY 2017-18, FY 2018-19, FY 2019-20, FY 2020-21, FY 2021-22 or FY 2022-23. However, for availing the benefit of waiver of late fees. you need to file any pending GSTR-9C on or before March 31, 2025.


The original deadline to file GSTR-9 and GSTR-9C, both for any particular financial year is December 31. While the GSTR-9 annual return can very well be filed without the GSTR-9C return, the law recommends both the returns be filed together.

The present notification is relevant for those taxpayers who didn’t follow this recommendation and skipped filing GSTR-9C.

Additionally, no refund will be provided for any late fees already paid for the delayed furnishing of GSTR-9C for these financial years, the notification said.

This move is expected to bring relief to taxpayers who have delayed filing reconciliation statements in the past. The government’s decision is seen as a step towards easing the compliance burden on taxpayers and promoting voluntary compliance.

Chairman, CBIC has launched CBIC’s WhatsApp Channel – ‘CBIC India’

In the weekly newsletter dated January 8, 2024, Chairman Sanjay Kumar Agrawal of the Central Board of Indirect Taxes and Customs (CBIC) shared noteworthy updates.

From the launch of CBIC’s WhatsApp channel to commendable achievements, the newsletter provides insights into the latest developments within the organization.

Here are the detailed Analysis:

==========================

  1. WhatsApp Channel Launch:

Chairman Agrawal introduced the recently launched CBIC India WhatsApp channel. With a presence on various social media platforms, including Twitter, Facebook, Instagram, YouTube, and Koo, CBIC aims to enhance taxpayer information and facilitation. The WhatsApp channel, a pioneering move by a government department, already boasts around 7,500 followers.

  1. IRS Officers Passing Out Ceremony:

The newsletter highlights the Passing Out Ceremony of the 73rd Batch of IRS (C&IT) Officers. Chairman Agrawal emphasizes the significance of knowledge, citing the academy’s motto. The trained officers, ready to serve, demonstrate espirit de corps and are prepared to administer customs and indirect taxes.

  1. Medals and Recognitions:

Exceptional officers are recognized during the ceremony, with medals awarded for outstanding performance during their probationary period. Notable achievements include the FM and Chairman Gold Medal, Kaushalya Narayanan Memorial Gold Medal, Director General Gold Medal, and N. K. Upadhyay Memorial Gold Medal.

  1. Vigilance Achievements:

CBIC achieved a record number of disposals of vigilance cases in 2023, with 524 disciplinary proceedings disposed of. The Chairman commends the collective effort and expresses confidence in sustaining this momentum for the upcoming year, aiming for new heights in vigilance administration.

5. Relief Measures for Rain-Affected Areas:

Due to heavy rains in Tamil Nadu, CBIC approved the extension of due dates for filing GSTR-3B and Annual Return. This decision aims to provide relief to taxpayers in rain-affected areas.

  1. Customs Success Story:

The newsletter highlights a successful case booked by Trichy Customs (Preventive) Commissionerate, showcasing the vigilance and teamwork of officers. A specific intelligence-led operation led to the recovery of 7.70 kgs of gold worth Rs. 4.85 Crore.

Conclusion: Chairman Sanjay Kumar Agrawal’s weekly newsletter encapsulates the dynamism of CBIC, showcasing achievements, recognitions, and significant initiatives.

From technological advancements like the WhatsApp channel launch to the vigilance administration accomplishments, the newsletter underscores CBIC’s commitment to efficiency, transparency, and serving the public interest.

Stay tuned for more updates and insights in the weeks to come, as CBIC continues its journey towards excellence in customs and indirect taxes administration.

WhatsApp Channel

Read More

Extension of time for GSTR-3B Filing for November 2023 in specific districts of Tamil Nadu

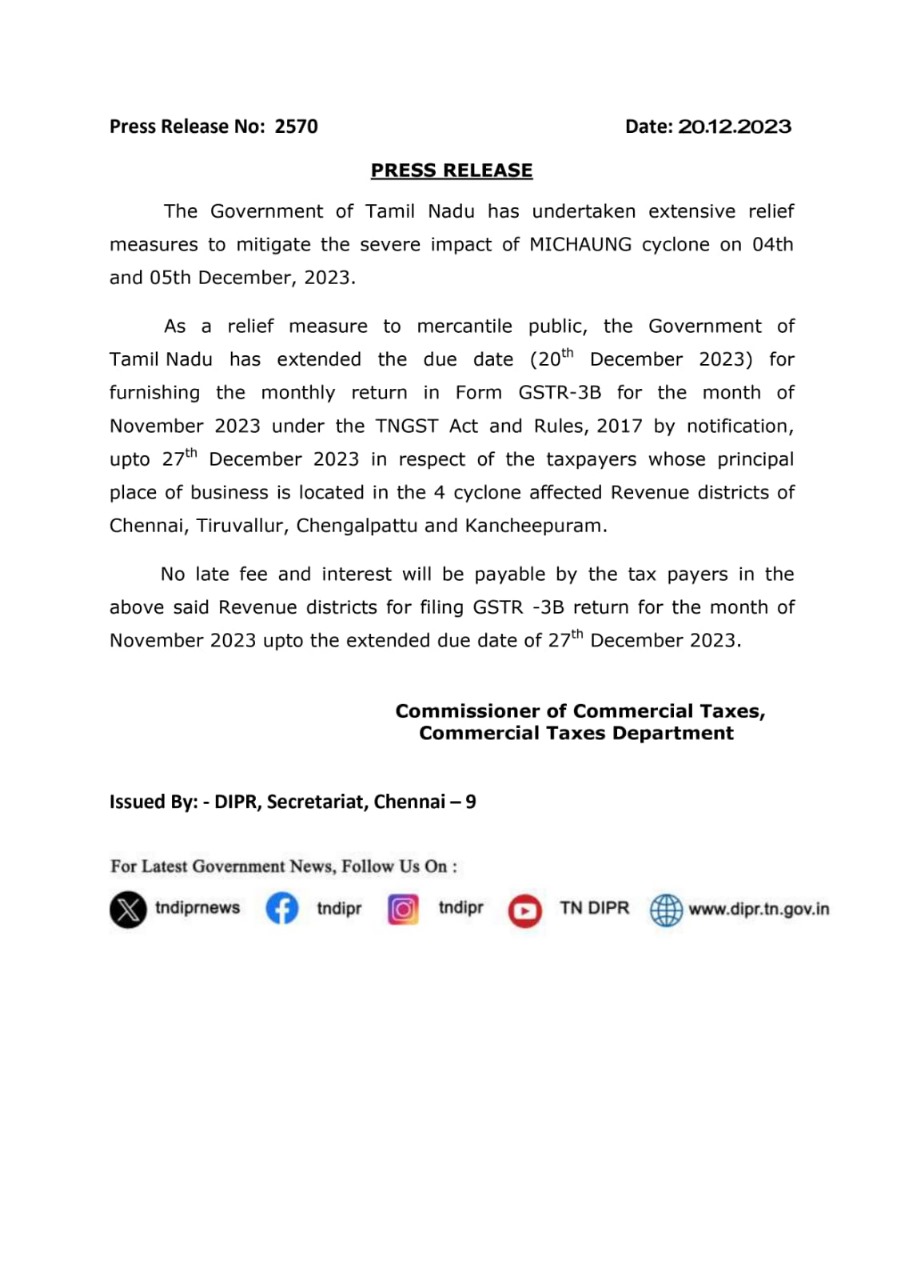
In response to the devastation caused by the MICHAUNG cyclone in early December 2023, the deadline for monthly GST returns has been extended, in respect of the taxpayers whose principal place of business is located in the four cyclone-affected districts of Chennai, Tiruvallur, Chengalpattu and Kancheepuram, as per release from Commercial Taxes Department.


The CBIC vide Notification No. 55/2023 – Central Tax dated December 20, 2023, extends the deadline for filing FORM GSTR-3B for November 2023 until December 27, 2023.

This extension applies to registered individuals with their principal place of business in specific districts of Tamil Nadu (Chennai, Tiruvallur, Chengalpattu, Kancheepuram), as recommended by the Council under section 39(1) and rule 61(1)(i) of the Central Goods and Services Tax Rules, 2017 (“the CGST Rules”).

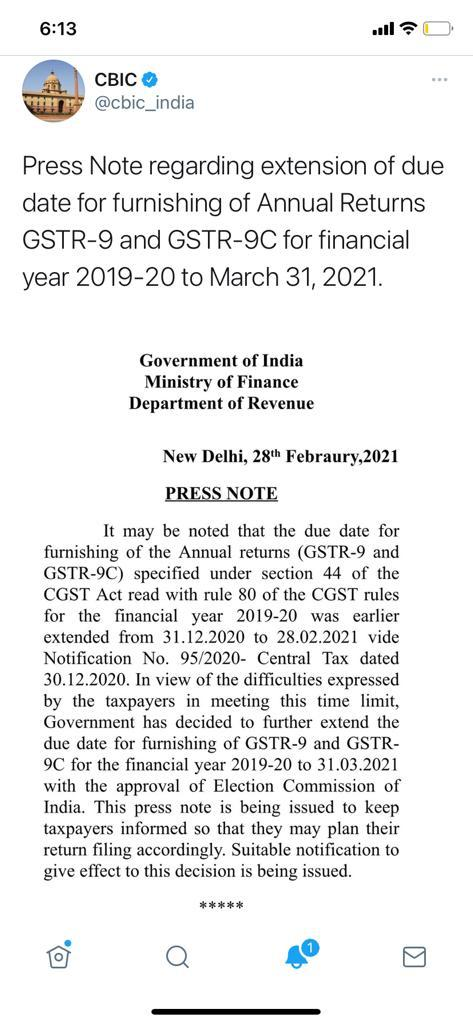
Extension of due date for furnishing of Annual Returns GSTR-9 and GSTR-9C for financial year 2019-20 to March 31, 2021

CBIC had extended, vide Press Note regarding extension of due date for furnishing of Annual Returns GSTR-9 and GSTR-9C for financial year 2019-20 to March 31, 2021.

This is the second extension given by the government. The deadline was earlier extended from December 31,2020 to February 28.

6 Crucial changes in GST Rules applicable from January 1st, 2021

The year 2021 has come up with the various changes in Goods and Service Tax (GST) Rules which will have a direct impact on the business registered under the GST regime and the businessmen who are planning to get themselves registered under GST.
 
Firstly, the CBIC has revised the extent of provisional Input Tax Credit (ITC) claims from 10% to 5%, with effect from 1 January 2021.
 

Firstly, the CBIC has revised the extent of provisional Input Tax Credit (ITC) claims from 10% to 5%, with effect from 1 January 2021. As per the sub-rule (4) inserted in rule 36 of the Central Goods and Service Tax Rules, 2017, a taxpayer filing GSTR-3B can claim ITC only to the extent of 5% of the eligible credit available in GSTR-2A. The amount of eligible credit is arrived upon those invoices or debit notes, the details of which have been uploaded by the suppliers in the GSTR-2A only. The new percentage applies from 1 January 2021 onwards. The ITC claim was earlier restricted to 10% between 1 January 2020 and 31 December 2020 whereas it was 20% for the period from 9 October 2019 till 31 December 2019.

Secondly, the CBIC has amended the Rule 21, which is in respect of the suspension or cancellation of GST Registration. The amendment inserted the additional situation wherein the registration of a person can be suspended if he avails input tax credit in violation of the provisions of section 16 of the Act or the rules; or furnishes the details of outward supplies in FORM GSTR-1 for one or more tax periods which is in excess of the outward supplies declared by him in GSTR 3B for the said tax periods, or violates the provision of rule 86B.

Thirdly, the Board inserted Rule 86B wherein all the registered persons have to pay 1% cash liability so as to curb tax evasion by way of fake invoicing. The Rule 86B is applicable to only those registered persons whose value of taxable supply, other than exempt supply and export, in a month exceeds Rs 50 lakh that means those whose annual turnover is more than 6 crore.

For example, if a dealer has made a sale of Rs 1 crore of the goods whose tax rate is 12% and if he is discharging his tax liability more than 99% though ITC, then he has to pay only Rs.12,000 under this rule. On the other hand, a composition dealer would have paid Rs.1 lakh in cash with this volume of sale.

Fourthly, the CBIC has amended Rule 8 and 9 which pertained to New GST Registration, which provides for the biometric verification i.e. Aadhaar authentication and taking photographs or taking biometric information, photograph and verification of such other KYC documents for the applications for new registration.

However, in the case of those opting not to use Aadhaar, GST registration would be given only after physical verification of the business premise, which could take upto 21 days and in case a notice is issued, even more time.

Fifthly, the Board has amended Rule 59, not to permit the taxpayer to file GSTR 1 if the taxpayers have not furnished the return in FORM GSTR-3B for the preceding two months (for a taxpayer filing monthly returns); he has not furnished the return in FORM GSTR-3B for preceding tax period (for a taxpayer filing quarterly returns) and he is required to discharge the tax liability of at least 1% by cash (see the discussion on Rule 86B) and he has not furnished the return in FORM GSTR-3B for preceding tax period instead of two months.

Sixthly, the CBIC has amended Rule 138(10) which related to E-way Bill wherein the available travel time has been enhanced to 200 Kms. For example, goods dispatched to the destination located at a distance of 550 kms have taken place on February 1, 2021. As per the existing rule, the validity of the E-way bill generated would have expired on February 7, 2021, i.e. one day for 100km starting from the midnight of the generation of the E-way bill. However, as per the amendment, the e-way bill will expire on February 4, 2021, and hence the goods must reach the destination within the time frame.

GSTN will re-credit late fees collected

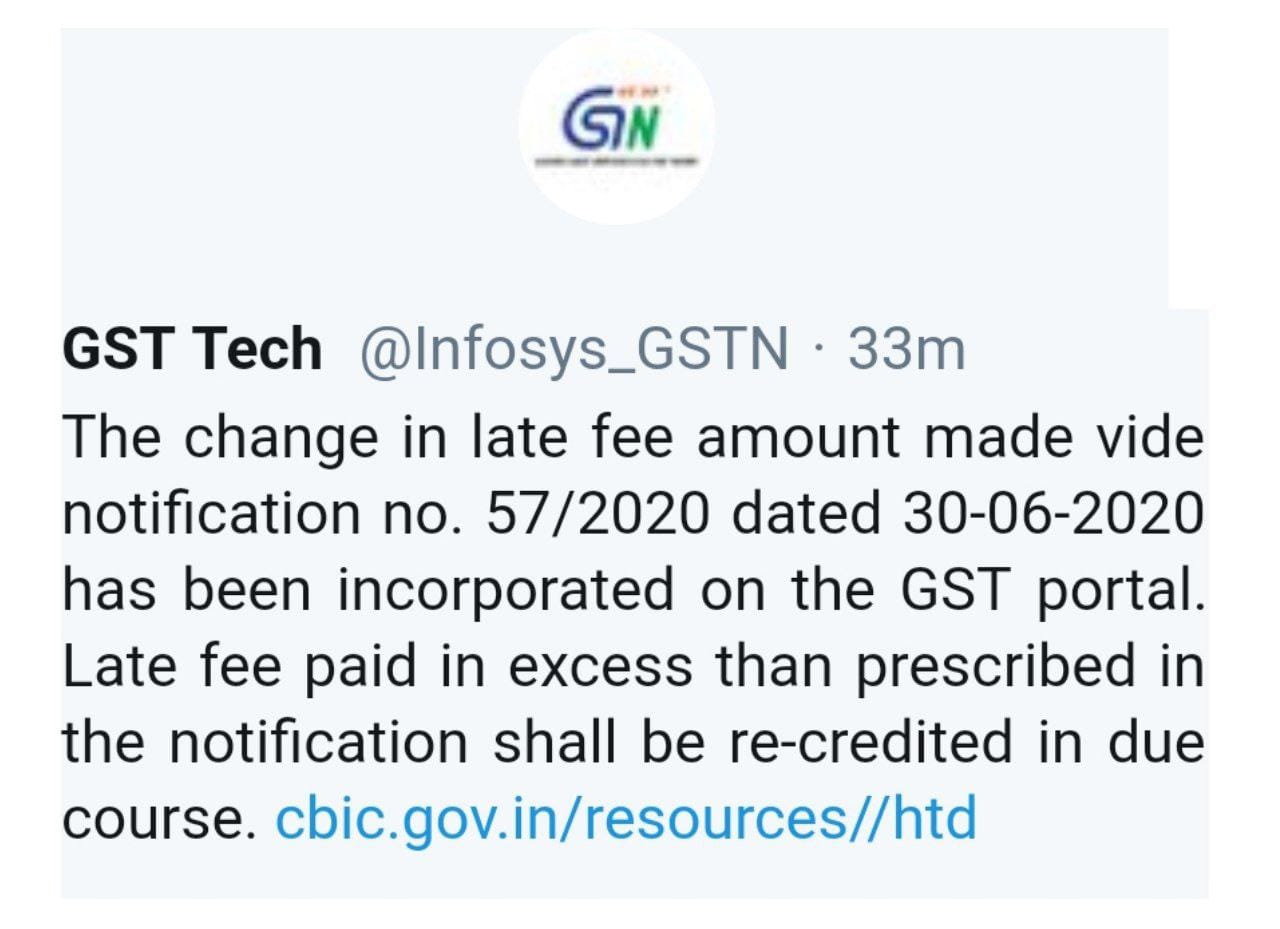
The change in late fee amount made vide notification no. 57/2020 dated 30-06-2020 has been incorporated on the portal. Late fee paid in excess than prescribed in the notification shall be re-credited in due course.

CBIC had vide Noti 57/2020 has stated that that maximum Late Fee for Form GSTR 3B has been capped at Rs. 500 for tax period July 2017 to July 2020 subject to returns being filed before 30th September 2020.

But portal was not updated and it has levied late fees as per old calculation. Hence, GSTN Tech twitter posted that “The change in late fee amount made vide notification no. 57/2020 dated 30-06-2020 has been incorporated on the GST portal.

Late fee paid in excess than prescribed in the notification shall be re-credited in due course.”

[To be published in the Gazette of India, Extraordinary, Part II, Section 3, Sub-section (i)]
Government of India
Ministry of Finance
(Department of Revenue)
Central Board of Indirect Taxes and Customs
Notification No. 57/2020 – Central Tax

New Delhi, the 30th June, 2020

G.S.R…..(E).— In exercise of the powers conferred by section 128 of the Central Goods and Services Tax Act, 2017 (12 of 2017) (hereafter in this notification referred to as the said Act), read with section 148 of the said Act, the Government, on the recommendations of the Council, hereby makes the following further amendments in the notification of the Government of India in the Ministry of Finance (Department of Revenue), No. 76/2018– Central Tax, dated the 31st December, 2018, published in the Gazette of India, Extraordinary, Part II, Section 3, Sub- section (i) vide number G.S.R. 1253(E), dated the 31st December, 2018, namely :–

In the said notification, after the third proviso, the following provisos shall be inserted, namely: –
“Provided also that for the class of registered persons mentioned in column (2) of the Table of the above proviso, who fail to furnish the returns for the tax period as specified in column (3) of the said Table, according to the condition mentioned in the corresponding entry in column (4) of the said Table, but furnishes the said return till the 30th day of September, 2020, the total amount of late fee payable under section 47 of the said Act, shall stand waived which is in excess of two hundred and fifty rupees and shall stand fully waived for those taxpayers where the total amount of central tax payable in the said return is nil:

Provided also that for the taxpayers having an aggregate turnover of more than rupees 5 crores in the preceding financial year, who fail to furnish the return in FORM GSTR-3B for the months of May, 2020 to July, 2020, by the due date but furnish the said return till the 30th day of September, 2020, the total amount of late fee under section 47 of the said Act, shall stand waived which is in excess of two hundred and fifty rupees and shall stand fully waived for those taxpayers where the total amount of central tax payable in the said return is nil.”.

2. This notification shall be deemed to have come into effect from the 25th day of June, 2020.

[F. No. CBEC-20/06/08/2020-GST]
(Pramod Kumar)
Director, Government of India

Note: The principal notification No. 76/2018-Central Tax, dated 31st December, 2018 was published in the Gazette of India, Extraordinary, vide number G.S.R. 1253(E), dated the 31st December, 2018 and was last amended vide notification number 52/2020 – Central Tax, dated the 24th June, 2020, published in the Gazette of India, Extraordinary, Part II, Section 3, Sub-section (i) vide number G.S.R.405 (E), dated the 24th June, 2020.

Govt Notification