GST 2.0: What changed at the recent GST Council meeting – rates, processes and what it means

GST Council, has recommended to reduce / waive the interest/ late fee for delayed filing of GSTR 3B by small taxpayers (having turnover upto Rs. 5 crores) for the tax period from July 2017 to July 2020
The GST Council has announced major rate cuts and compliance reforms in its September 2025 meeting. Highlights of new GST slabs, effective dates, process changes, and how businesses should prepare.

India’s GST system just received its biggest shake-up since rollout: the GST Council approved a major rate rationalisation (moving to a much simpler slab structure), together with a package of taxpayer-friendly process reforms. The changes – aimed at reducing complexity, lowering prices for many everyday goods, and speeding up compliance/refunds for businesses – are to be implemented from 22 September 2025 (with a few exceptions and phased rollouts). Here’s a clear, practical, and source-backed breakdown of what happened, why it matters, and what businesses and consumers should expect next.


Main Highlights

  • Two main GST slabs: 5% (merit/essential) and 18% (standard) — the 12% and 28% slabs are being collapsed into these. A special de-merit 40% rate is proposed for a small set of luxury/sin goods (tobacco, very high-end vehicles, etc.).


  • Implementation date: Most changes effective 22 Sept 2025 (Navratri start). Tobacco/pan masala items will have separate timing. Some elements may be phased to manage compensation fund impacts.


  • Process reforms: Faster/automated registration for low-risk businesses, pre-filled returns, auto/refund acceleration, risk-based provisional refunds for exporters and a timeline to operationalise many tech changes.


  • Anti-profiteering approach: legal anti-profiteering machinery (Section 171) hasn’t been reinstated in an aggressive form — the government is asking industry to pass on benefits while monitoring and states are pushing for safeguards. Expect guidance from tax authorities.


What exactly changed – the rate map (summary)

The Council rationalised slabs to simplify compliance and broaden the “common man” gains.

  • 5% slab — Will cover a large set of essentials, many medicines/healthcare inputs, basic food items and several household staples and smaller consumer items previously at 12%/18%. (Examples reported: roti, many edible goods, certain medicines and diagnostic kits, small household appliances in some categories).


  •  8% slab — The standard rate now for most manufactured goods and many services previously at 18%/28%/12% where reclassification makes sense (e.g., many auto components, some consumer durables moved to 18%).


  • 40% de-merit slab — A higher, selective rate for luxury and sin goods (tobacco products, very high-end cars, other items identified by the Council). These are explicitly carved out to preserve revenue and to tax dis-incentivise harmful/very high-end consumption.


Implementation mechanics & phasing

  • Effective date: The Council recommended implementation from 22 September 2025 for most goods/services. Tobacco and tobacco-related items will have separate treatment (different effective date to be notified) because of compensation cess and administrative considerations. Some elements (especially where compensation cess/compensation fund is concerned) may be phased to smooth state receipts.


  • Why phased? Several states flagged potential revenue loss concerns; the Council stressed consensus but also acknowledged fiscal impacts and decided to manage timing and the compensation cess account accordingly. Expect circulars from CBIC explaining exact implementation steps (tariff notifications, HSN crosswalks, valuation/credit rules). 


Process reforms (big ticket operational changes)

The meeting wasn’t just about rates – there’s a parallel package to make compliance quicker and less painful:

  1. Automated/simplified registration for low-risk applicants (target: 3 days/automated approval for eligible applicants). This aims to cut onboarding friction for SMEs and startups.


  • Prefilled returns & auto refunds — prefilled return architecture and auto refunds (including provisional/90% provisional refunds for exporters based on risk evaluation for specific sectors) to speed liquidity to business. Rollouts/timelines were announced — many measures to be operationalised by October–November 2025.


  • Faster refund windows (seven-day targets for specific exporters/priority cases) and risk-based provisional mechanisms to reduce stuck refunds.


  • Tribunal and dispute reforms — strengthening appellate/ADR mechanisms (e.g., national benches for Advance Rulings) to improve consistency in rulings.

These process reforms are intended to complement rate rationalisation so taxpayers – especially MSMEs and exporters — face lower compliance cost and faster cash flows. 


Anti-profiteering and price transmission

  • The Council/officials have made it clear that industry is expected to pass benefits of lower GST to consumers. The strict anti-profiteering law (Section 171) hasn’t been robustly re-invoked as a new enforcement blitz, but states have insisted on safeguards and monitoring. Tax authorities and state governments will watch prices and may ask for evidence of benefit transmission; businesses should act cautiously and transparently. 

Practical tip for retailers/manufacturers: document the cost/repricing methodology, issue credit notes where appropriate and update pricing policies — this is both good business practice and a defensive step in case of state queries.


Sectoral winners and losers — who gains, who pays more

  • Likely beneficiaries (cheaper): FMCG staples, many food items, certain medicines & diagnostic reagents, entry-level autos and components, many household goods and some construction materials (cement, tiles — reported moves from 28→18% / 12→5% for specific items). These cuts will help consumer demand and reduce input costs for industries like housing and consumer durables. 


  • Likely paying more / targeted up-taxed: Very high-end cars, tobacco & pan masala, certain luxury goods moved into the 40% de-merit slab (aim: revenue neutrality and disincentive). 

Stakeholder notes: Auto dealers, consumer durables firms and textiles have broadly welcomed the move as demand stimulative; states with manufacturing-heavy revenue bases have flagged short-term revenue pain and asked for compensatory arrangements. 


How decisions were made (short explanation of the Council process)

  • The GST Council is a constitutional body (Article 279A) that makes recommendations on rates and other GST matters. Decisions are taken with a weighted voting mechanism (Centre has one-third weight, states two-thirds) and normally by a three-fourths weighted majority — but in practice the Council aims for consensus. The 56th meeting reported unanimous consensus on the package. 

What to watch next

  • Notifications from CBIC/CBIC circulars giving precise tariff/HSN crosswalks, valuation rules and timeline for phased items. (Those will be the legally binding documents.) 


  •  State responses about compensation/temporary support if they claim revenue shortfalls — any fiscal transfers or special measures will be announced in coming weeks.


  • Price monitoring: watch for state consumer affairs departments and tax authorities asking firms to show price transmission evidence.


Final take

This is a large, pro-consumer and pro-growth move designed to simplify GST’s complexity and spur demand ahead of the festive season — while also modernising the compliance stack (faster registration/refunds). It’s politically significant (broad consensus) and technically big — businesses should act fast to align systems, pricing and documentation. States’ fiscal positions will be the main political/implementation watchpoint, so expect more operational clarifications from CBIC in the coming days.


GST Invoice Management System: A game changer for businesses from October 2024

The GSTN has introduced a transformative feature called the IMS on the GST portal aimed at simplifying the process of correcting invoices

Through an advisory issued on September 3, 2024, the IMS is set to go live for taxpayers starting October 1, 2024, marking a significant milestone in the evolution of GST compliance procedures.

Key Features of the GST Invoice Management System (IMS)

The GST Invoice Management System (IMS) offers businesses a streamlined approach to managing their GST invoices, particularly in cases where discrepancies or amendments are necessary.

According to the GSTN advisory, “To enable taxpayers to efficiently address invoice corrections/amendments with their suppliers through the portal, a new communication process called the Invoice Management System (IMS) is being brought up at the GST portal.”

This system is designed to help businesses reconcile their GST records with those issued by their suppliers, ensuring ITC claims are compliant and accurate.

One of the standout features of IMS is that it allows taxpayers to accept, reject, or keep invoices pending before including them in their GST ITC claims.

This ensures that businesses can review the accuracy of each GST invoice and avoid potential issues during audits. The flexibility offered by the system allows businesses to defer action on GST invoices and address them in future tax periods, if necessary.

Taxpayers can update their GST invoice records anytime before filing their GSTR-3B return, a critical component in the GST compliance process.

Impact of the GST Invoice Management System on the ITC Ecosystem

The IMS is expected to significantly enhance the efficiency of ITC claims under the GST regime by providing a more structured mechanism for matching invoices between recipients and suppliers.

Since mismatches in GST invoices have been a primary source of discrepancies in ITC claims, the new system is a welcome addition.

The GSTN has long sought to introduce this level of control to minimize incorrect or fraudulent ITC claims.

Under this system, only accepted GST invoices will form part of the taxpayer’s GSTR-2B, which is the auto-populated form used to claim ITC under the GST framework.

By ensuring that only verified invoices are included in this form, businesses can significantly reduce errors in their GST returns, thus reducing the risk of disputes or penalties during audits.

Moreover, the IMS integrates seamlessly with the Quarterly Return Monthly Payment (QRMP) scheme, which allows smaller taxpayers to file GST returns quarterly while making monthly GST payments. For those enrolled in the QRMP scheme, the IMS will generate GSTR-2B on a quarterly basis, making it easier to manage GST invoices and ITC claims. This feature is particularly beneficial for small and medium-sized enterprises (SMEs), which often struggle with the administrative burden of GST compliance.

“The IMS is expected to facilitate transparency between GST recipients and suppliers and streamline the reconciliation of ITC, which has been a challenging process since the introduction of GST.”

While the full benefits of the system will become evident after its implementation, the IMS is expected to address several long-standing issues in GST compliance.

Source: Invoice Management System

Advisory on reporting of supplies to un-registered dealers in GSTR-1/GSTR-5

<strong><em>Reporting of inter-state taxable outward supplies to unregistered dealers - Advisory by GST.</em></strong>
Reporting of inter-state taxable outward supplies to unregistered dealers – Advisory by GST.

An advisory has been issued on September 3,2024 by the Government of India for the recent amendment under Notification No. 12/2024 Central Tax, dated 10th July 2024, that lessens the threshold limit for the reporting of inter-state taxable outward supplies to unregistered dealers.

The invoice-wise reporting of information of these supplies was lessened from Rs 2.5 lakh to Rs 1 lakh, impacting how businesses file their GSTR-1 and GSTR-5 returns.

As per the notification, the above reduction in the threshold would need the assesses to furnish the detailed invoice-wise data for all inter-state supplies to unregistered dealers that surpass Rs 1 lakh in value. The same information should be reported in Table 5 of Form GSTR-1, for regular tax payers and Table 6 of GSTR-5, for non-resident taxable persons.

The same advisory states that the said revisions are being executed at present in the Goods and Services Tax (GST) portal and will be available for taxpayers shortly.

In the interim, taxpayers need to continue reporting inter-state taxable outward supplies to unregistered dealers that surpass the previous threshold of ₹2.5 lakh. These must be filed in Table 5 of GSTR-1 for regular taxpayers and Table 6 of GSTR-5 for non-resident taxable persons.

Further, till the time the functionality gets updated and is made available to the GST portal, it is advised to continue reporting the invoice wise details of taxable outward supplies to unregistered dealers which are more than Rs. 2.5 Lakhs in the Table 5 of Form GSTR-1 and Table 6 of GSTR-5, which would facilitate the process of reporting and align it with the amended threshold limits.

The businesses are suggested to stay updated with the additional announcements on the operationalization of the revision and the assesses are advised to track the updates on the GST portal for the additional guidelines.

Source: Advisory on GSTR-1/ GSTR-5

Highlights from the 53rd GST Council Meeting

Several measures were proposed to ease compliance and reduce litigation for taxpayers 53rd GST council meeting.
Several measures were proposed to ease compliance and reduce litigation for taxpayers in the 53rd GST council meeting.

The 53rd meeting of the Goods and Services Tax (GST) Council was held on June 22 in New Delhi. Several recommendations were made at the meet to refine tax rates and service exemptions under the GST regime.

The meeting, chaired by Union Finance Minister Nirmala Sitharaman, deliberated on various proposals to streamline GST applicability across goods and services.

Many items were present on the agenda from this GST Council meeting. Further, before the GST Council meeting, the Union FM had a pre-budget consultation with various states and UTs. Union FM also clarified that as of 31st December 2023, less than 1.96% of GST taxpayers received the notices under GST (1,14,999 taxpayers).

Several measures were proposed to ease compliance and reduce litigation for taxpayers.

Here are the key highlights:

Ease of compliance burden of taxpayers

  • Changes will be allowed in GSTR-1 going forward within same tax period: The GST Council approved implementing a functionality for a new form GSTR-1A that allows taxpayers to add/amend particulars of GSTR-1 of current tax period/IFF for 1st and 2nd month of quarter, that is missed out before filing GSTR-3B.
  • Reporting B2C supplies in GSTR-1: The threshold for reporting Business-to-Consumers (B2C) interstate supplies invoice-wise in Table 5 of GSTR-1 will be reduced from Rs.2.5 lakh to Rs.1 lakh.
  • GSTR-4 Due Date Revised: Extension provided to the due date for filing GSTR-4 by the composition taxable persons from the present 30th of April to 30th of June 2024 from FY 2024-25 onwards.
  • TCS Rate Reduction: Electronic Commerce Operators (ECOs) had to collect Tax Collected at Source (TCS) at 1% (0.5% each under CGST and SGST/ 1% under IGST) on net taxable supplies under Section 52(1) of the CGST Act. It is recommended to reduce this to 0.5 % (0.25% under CGST and 0.25% under SGST/UTGST/0.5% under IGST).
  • Compulsory filing of GSTR-7: GSTR-7 must be filed mandatorily even if no TDS is deducted, reported invoice-wise and no late fee will be charged for nil filing.
  • GSTR-9/9A filing applicability: The filing of annual return in GSTR-9/9A for the FY 2023-24 would be exempted for taxpayers with an aggregate annual turnover upto Rs.2 crore.
  • Modification to Section 16(4): The time limit to avail ITC for invoices or debit notes in any GSTR-3B filed up to 30th November 2021 (applicable for fiscal years 17-18, 18-19, 19-20 and 20-21) may be deemed to be 30th November 2021, which will apply retrospectively from 1st July 2017. Furthermore, Section 16(4) shall be relaxed where returns for the period from the date of cancellation of registration/ effective date of cancellation of registration till the date of revocation of cancellation of the registration, are filed by the registered person within thirty days of the order of revocation.
  • Amendment to CGST Rule 88B: The GST Council has recommended not to charge interest on the amount available in the electronic cash ledger on the due date of filing GSTR-3B and is debited while filing the said return in cases of delayed filing of GSTR-3B.
  • New Section 128A: GST Council has waived interest and penalties for demand notices issued u/s 73 of CGST (applicable for fiscal years 17-18, 18-19 and 19-20) for cases not involving fraud, suppression and misstatement. It is applicable to cases where the taxpayer pays the full amount in the notice by 31st Mar 2025.
  • Changes in Section 73 and 74: A common time limit will be set for issuing demand notices and orders under both these provisions without differentiating cases as fraud/non-fraud. The time limit for the taxpayers to claim the benefit of reduced penalty, by paying the tax demanded along with interest, would be increased from 30 to 60 days.
  • Monetary Limits set for GST Appeals: The recommended monetary limits for filing appeals by the department before these legal fora are Rs.20 lakh for GST Appellate Tribunal, Rs.1 crore for HC and Rs.2 crore for SC. 
  • Amending Sections 107 and 112:  The maximum amount for pre-deposit for filing appeal before appellate authorities shall be reduced from Rs.25 crore under CGST and Rs.25 crore under SGST to Rs.20 crore respectively. Moreover, the amount of pre-deposit for appeal before the GST Appellate Tribunal has been reduced from 20% with a maximum amount of Rs.50 crores under CGST and Rs.50 crores under SGST to 10% with a maximum of Rs.20 crores under CGST and Rs.20 crores under SGST.
  • Sunset Clause to amend Sections 109 & 117: Sunset clause to be added for anti-profiteering cases pending and decision taken to shift the hearing panel from CCI to principal bench of GSTAT. The GST Council has also recommended the sun-set date of 1st April 2025 for receiving any new application regarding anti-profiteering.
  • Time limit to file appeals before the GSTAT: The GST Council recommended modifying Section 112 to provide a 3 months time for filing appeals before the GST Appellate Tribunal. It will start from a date yet to be notified by the Government, most likely to be announced by 5th August 2024 as this is the last date.
  • New Section 11A: The new provision allows regularization of non-levy or short levy of GST, where tax was being underpaid or unpaid due to common trade practices. 
  • IGST Refund due to upward price revisions after exports: A mechanism is being introduced for claiming refund of additional IGST paid due to any upward revision in price of the goods after their export, helping taxpayers claim refunds for paying additional IGST due to such move.
  • No refund of IGST in specific case: Where export duty is payable, IGST will not be refunded by modifying Sections 16 and 54. This applies for both exports and supplies to SEZ unit/developer with or without payment of tax.
  • Biometric-based Aadhaar Authentication: Those applicants who have opted for Biometric based Aadhaar authentication conducted at the GST Suvidha Kendra will be rolled out for GST registration on all-India basis in a phased manner.
  • DRC-03 Circular expected to be notified: A circular will be issued to prescribe a mechanism for adjusting any demand amount paid through DRC-03 against the amount payable as pre-deposit for filing GST appeal.
  • Section 122(1B) to be amended: Amendment will apply retrospectively w.e.f. 1st October 2023, so as to clarify that the said penal provision is applicable only for those e-commerce operators, who are required to collect TCS u/s 52 and not for other e-commerce operators.
 
Rate rationalisation for Goods and Services

The GST Council announced several GST rate revisions and exemptions for goods and services, as listed below-

Particulars

New GST Rates / Exemptions

Extra Neutral Alcohol used for the manufacture of alcoholic liquor for human consumption

Exempt

Imports of parts, components, testing equipment, tools, and tool-kits of aircraft, irrespective of their HS classification, are used to boost the MRO activities subject to specified conditions.

5% IGST

Parts of Poultry keeping Machinery

12%

All milk cans (different materials), irrespective of use

12%

All carton boxes and cases of both corrugated and non-corrugated paper board

12%

All types of sprinklers, including fire water sprinklers

12%

All solar cookers, whether or not single or dual energy source

12%

Services provided by Indian Railways to common man for sale of platform tickets, cloak rooms, and battery operated car services are exempted, including intra railway supplies

Exempt

Service by way of hostel accommodation is currently not exempted if outside educational institution upon satisfying the conditions that the rent limit is up to Rs. 20,000 per person per month, and the service is rendered for a continuous period of 90 days

Exempt

Corporate guarantee if in case it is for services or goods where whole ITC is available

Exempt

Services provided by Special Purpose Vehicles (SPV) to Indian Railway by way of allowing Indian Railway to use infrastructure built & owned by SPV during the concession period and maintenance services supplied by Indian Railways to SPV

Exempt

Imports of specified items for defence forces

IGST is exempt for five years till 30th June 2029

Imports of research equipment/buoys imported under the Research Moored Array for African-Asian-Australian Monsoon Analysis and Prediction (RAMA) programme subject to specified conditions

IGST is exempt

Imports in SEZ by SEZ Unit/developers for authorised operations with effect from 1st July 2017

Compensation Cess is exempt

Supply of aerated beverages and energy drinks to authorised customers by Unit Run Canteens under the Ministry of Defence

Compensation Cess is exempt

Import of technical documentation for AK-203 rifle kits imported for the Indian Defence forces.

Ad hoc IGST exemption provided

These measures aim to streamline the GST compliance process, provide clarity on various issues, and ensure consistency across the GST framework. The recommendations will be implemented through relevant circulars, notifications, and law amendments.

Source:

53rd GST Council Recommendations

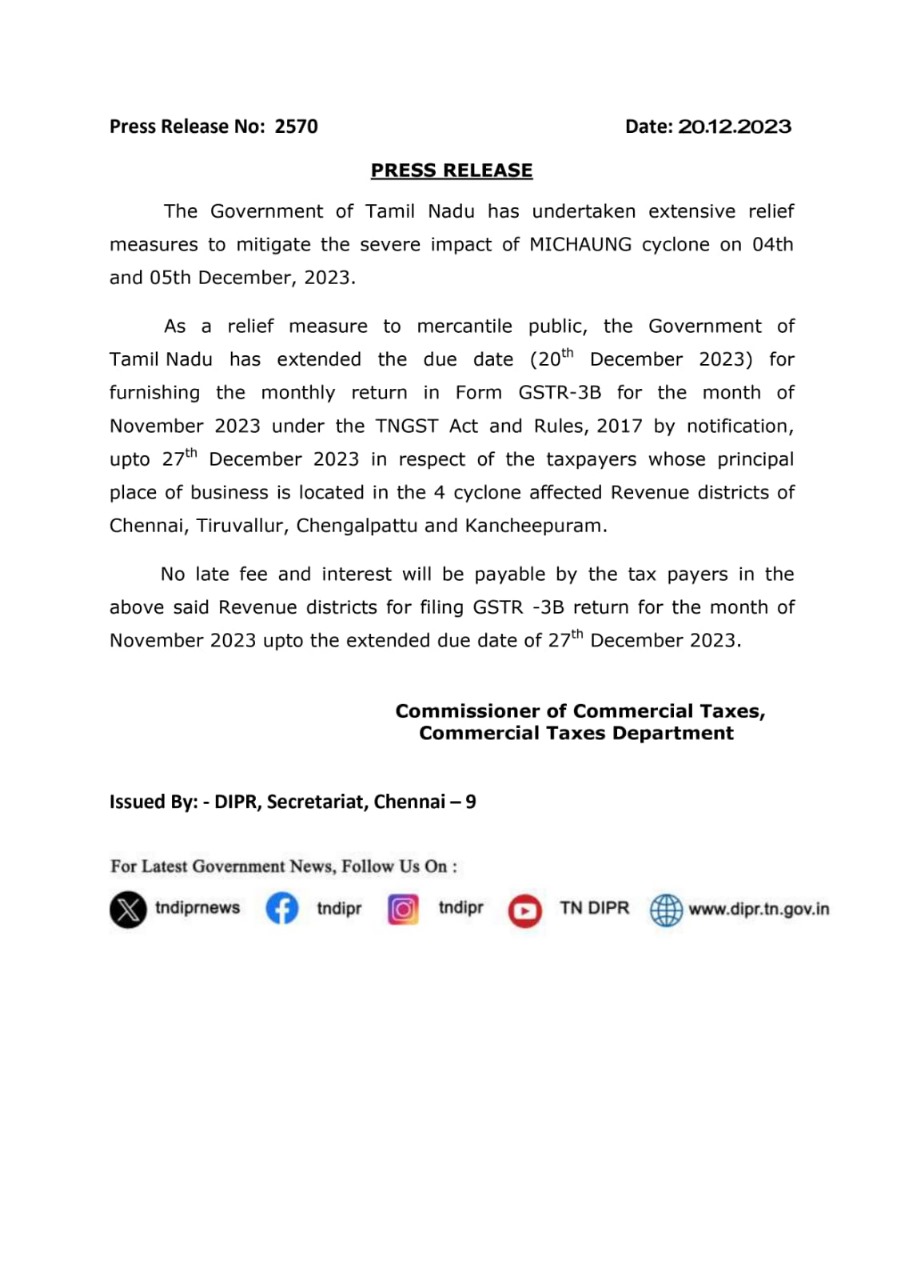
Extension of time for GSTR-3B Filing for November 2023 in specific districts of Tamil Nadu

In response to the devastation caused by the MICHAUNG cyclone in early December 2023, the deadline for monthly GST returns has been extended, in respect of the taxpayers whose principal place of business is located in the four cyclone-affected districts of Chennai, Tiruvallur, Chengalpattu and Kancheepuram, as per release from Commercial Taxes Department.


The CBIC vide Notification No. 55/2023 – Central Tax dated December 20, 2023, extends the deadline for filing FORM GSTR-3B for November 2023 until December 27, 2023.

This extension applies to registered individuals with their principal place of business in specific districts of Tamil Nadu (Chennai, Tiruvallur, Chengalpattu, Kancheepuram), as recommended by the Council under section 39(1) and rule 61(1)(i) of the Central Goods and Services Tax Rules, 2017 (“the CGST Rules”).

GST collection in October crosses ₹1.3 lakh crore, second highest ever

GST collection in October crosses ₹1.3 lakh crore, second highest ever

The gross GST revenue collected in the month of October 2021 exceeded ₹1.3 lakh crore. The GST revenues for October is the second highest ever since introduction of GST, second only to that in April 2021, which related to year-end revenues. The revenues for the month of October 2021 are 24% higher than the GST revenues in the same month last year.

The gross GST revenue collected in the month of October 2021 exceeded ₹1.3 lakh crore. The GST revenues for October is the second highest ever since introduction of GST, second only to that in April 2021, which related to year-end revenues. The revenues for the month of October 2021 are 24% higher than the GST revenues in the same month last year.

“This is very much in line with the trend in economic recovery. This is also evident from the trend in the e-way bills generated every month since the second wave. The revenues would have still been higher if the sales of cars and other products had not been affected on account of disruption in supply of semi-conductors,” the government said in a statement.

The government settled ₹27,310 crore to CGST and ₹22,394 crore to SGST from IGST as regular settlement. The total revenue of Centre and the States after regular settlements in the month of October 2021 is ₹51,171 crore for CGST and ₹52,815 crore for the SGST.

During the month, revenues from import of goods was 39% higher and the revenues from domestic transaction (including import of services) are 19% higher than the revenues from these sources during the same month last year.

Indian stock market benchmark Sensex was up over 600 points in noon trade. A private survey released earlier in the day showed India’s manufacturing sector activities gained further strength in October as companies scaled up production and stepped up input purchasing in anticipation of further improvements in demand.

The seasonally adjusted IHS Markit India Manufacturing Purchasing Managers’ Index (PMI) rose from 53.7 in September to 55.9 in October, pointing to the strongest improvement in overall operating conditions since February.

Robust gains in new work aided production growth in October as output and new orders expanded at fastest rates in seven months, while business optimism hit a six-month high, the survey said.

Source: Mint

MCA gives compliance relief to businesses due to second wave of COVID-19

The Ministry of Corporate Affairs (MCA), considering requests to waive additional fee for late filing of statutory forms which fall due between 1 April and end of May owing to the COVID-19 restrictions and disruption, has granted extra time without additional fee for filing statutory forms till the end of July, 2021


The ministry of corporate affairs (MCA) has offered relaxation in certain compliance requirements for businesses, including a longer interval between two board meetings in view of the hardships during the second wave of the pandemic.

Companies are normally required to hold a minimum of four board meetings in a year with the interval between them not exceeding 120 days. This has now been relaxed by 60 days so that the interval could go up to 180 days, the ministry said in a notification issued on Monday.

The ministry also said in a separate notification that it has received several requests to waive the additional fee for late filing of statutory forms which fall due between 1 April and end of May in view of the covid-19 restrictions and disruption.

The ministry said these requests have been examined and taking into account the difficulties due to resurgence of coronavirus infections, extra time without additional fee has been granted till the end of July for filing statutory forms. In the case of filing forms to report creation or modification of a charge (lien or claim) on the assets of a company under various circumstances, the ministry has issued another notification granting relief. Accordingly, in cases where due date had expired before 1 April, extra time has been granted till end of May.

The finance ministry has already given relief for various compliance requirements related to income tax and goods and services tax (GST), besides exempting basic customs duty and agriculture cess on various medical supplies used in the prevention and treatment of coronavirus disease. The pandemic has taken a heavy toll on lives with over 222,000 deaths.

The central government has not favoured a lockdown of the country during the second wave, but several states had to impose curbs on movement and assembly of people to break the chain of infections. India has so far vaccinated over 15 crore people, or roughly 12% of the population. The second wave is expected to slow India’s economic recovery from an expected 7.7% contraction in FY21.

Source: Ministry of Corporate Affairs