MCA extends due date for filing DIR-3 KYC and DIR-3 KYC-WEB till Oct 31, 2025

The Ministry of Corporate Affairs has issued General Circular No. 06/2025 dated October 17, 2025, allowing companies to file their financial statements and annual returns for FY 2024–25 using the newly revised e-Forms (MGT-7, MGT-7A, AOC-4 series) on the MCA-21 Version 3 portal without additional fees until 31st December 2025.

This relaxation aims to help companies adapt to the new forms but does not extend statutory deadlines for holding AGMs under the Companies Act, 2013. Companies failing to meet statutory timelines remain liable for legal action, and filings made after this period will attract normal and additional fees as per applicable rules.

The Ministry has revised the e-Forms MGT-7, MGT-7A, AOC-4, AOC-4 CFS, AOC-4 NBFC (Ind AS), AOC-4 CFS NBFC (Ind AS), AOC-4 (XBRL) for annual filings, which were deployed on the MCA-21 Version 3 portal recently.

In view of the deployment of the new e-Forms, and considering that companies may require some time to get familiarized with the filing process, and keeping in view the requests received from various stakeholders, it has been decided that companies will be allowed to complete their annual filings pertaining to FY 2024-25 till 31st December, 2025 without payment of additional fees.

However, it is hereby clarified that this General Circular shall not be construed as conferring any extension of statutory time for holding of AGMs by the companies under the Companies Act, 2013 (the Act) and the companies which have not adhered to the relevant statutory timelines shall continue to be liable to legal action under the appropriate provisions of the Act.

Any filings made subsequent to the currency of this General Circular would attract payment of all fees, including additional fees, as provided in the Companies (Registration Offices and Fees) Rules, 2014, from the date when such filings were actually due under the Act.

This is issued with the approval of the Competent Authority.

Source: Gen-circular-5-20251015- Reg DIR 3 KYC

MCA extends due date for filing DIR-3 KYC

MCA extends DIR-3 KYC filing deadline to October 15, 2025: A sigh of relief for directors

The Ministry of Corporate Affairs (MCA) has announced a much-awaited extension for filing the DIR-3 KYC and DIR-3 KYC-WEB forms without additional fees. This provides directors with more time to complete their annual compliance requirements.

Key takeaways from the extension

  • Revised Due Date: The deadline has been extended from the usual September 30, 2025, to October 15, 2025.
  • No Additional Fee: The extension allows DIN holders to file their KYC details without incurring the standard ₹5,000 late filing penalty.
  • Applicability: The extension covers both e-form DIR-3 KYC (for first-time filers or those updating details) and the web-based DIR-3 KYC-WEB (for subsequent annual filings with no changes).
  • Reason for Extension: The MCA granted the extension after receiving requests from stakeholders to provide more time for compliance.

Who needs to file?

The DIR-3 KYC filing is a mandatory annual compliance requirement for every individual who holds a Director Identification Number (DIN). This includes:

  • Every DIN holder, regardless of whether they are currently serving as a director in a company or a designated partner in an LLP.
  • Even individuals whose DIN has been deactivated for non-compliance are required to file the form to reactivate it.

The importance of timely filing

Filing your DIR-3 KYC is a simple yet crucial step to ensure your director status remains active and compliant. Here’s why you should use this extension wisely:

  • Avoid DIN Deactivation: Failure to file the form by the new deadline will result in the deactivation of your DIN.
  • Prevent Penalties: If you miss the extended deadline, you will have to pay a steep penalty of ₹5,000 to get your DIN reactivated.
  • Maintain Corporate Governance: Timely compliance ensures that the MCA maintains accurate and updated records of directors, which is vital for corporate transparency and governance.

What you need to do

  1. Gather Information: Ensure you have your personal mobile number and email ID ready for OTP verification.
  2. Access the Portal: Log in to the MCA V3 portal to initiate the filing process.
  3. Choose the Correct Form: Select the appropriate form based on your filing history: e-form DIR-3 KYC (for first-timers or updates) or web-form DIR-3 KYC-WEB (for subsequent filings with no changes).
  4. Complete the Process: Verify your details and submit the form before October 15, 2025, to avoid any late fees.

Final thoughts

This extension is a welcome move by the MCA, especially for those who faced challenges during the initial filing period. It provides a valuable opportunity to complete the necessary compliance without the burden of additional fees. Directors are advised to take advantage of this extension and file their DIR-3 KYC forms at the earliest to ensure a smooth and penalty-free compliance process.

Source: MCA Circular

CBDT Extends Due Date for Filing Audit Reports: Relief for Taxpayers and Professionals

CBDT extends due date, taking into account the hardships faced by taxpayers and the representations received from professional bodies, by  one-month relief for audit report submissions.

The Central Board of Direct Taxes (CBDT) has announced a significant relief for taxpayers and professionals by extending the due date for filing various audit reports under the Income-tax Act, 1961. The deadline, which was earlier set for 30th September 2025, has now been extended to 31st October 2025 for the Assessment Year (AY) 2025–26.

Why Was the Extension Granted?

The decision came after multiple representations from professional associations, including Chartered Accountant bodies, who highlighted the challenges faced by taxpayers and practitioners in completing audits on time.

Key reasons cited include:

  • Natural calamities such as floods in several regions, which disrupted normal business and professional activities.
  • Court petitions filed before various High Courts seeking relief.
  • Heavy workload on tax professionals, especially after the individual ITR filing deadline in mid-September.

Interestingly, CBDT clarified that the Income-tax e-filing portal has been functioning smoothly, with no major technical glitches. By 24th September 2025, over 4.02 lakh Tax Audit Reports (TARs) had already been uploaded, with more than 60,000 TARs filed in a single day.

Who Needs to File a Tax Audit Report?

Under Section 44AB of the Income-tax Act, tax audit is mandatory for:

  • Businesses with turnover above ₹1 crore (limit increases to ₹10 crore if cash transactions are ≤ 5%).
  • Professionals with gross receipts above ₹50 lakh.
  • Taxpayers under presumptive taxation (Sections 44AD/44ADA/44AE) if they declare lower profits than prescribed and their income exceeds the basic exemption limit.

What Happens If You Miss the Deadline?

Failure to file the audit report within the due date can attract penalties:

  • 0.5% of turnover/gross receipts, subject to a maximum of ₹1.5 lakh.
  • The penalty is discretionary and may be waived if reasonable cause is demonstrated.

Impact on ITR Filing Deadlines

Currently, the due date for filing Income Tax Returns (ITRs) for taxpayers subject to audit remains 31st October 2025. However, experts suggest that CBDT may issue a separate notification to extend the ITR filing deadline to 30th November 2025, in line with past practice.

Key Takeaways

  • New due date for filing audit reports: 31st October 2025.
  • Reason for extension: Natural calamities, workload pressure, and professional representations.
  • E-filing portal status: Stable and fully functional.
  • Relief provided: Extra time for taxpayers and professionals to ensure accuracy and compliance.

Conclusion

The extension of the audit report filing deadline by CBDT is a welcome move, offering much-needed breathing space to taxpayers and professionals alike. While the e-filing system is robust, real-world challenges such as natural disasters and workload bottlenecks cannot be ignored. This proactive step ensures compliance without undue stress, reinforcing CBDT’s commitment to balancing efficiency with empathy.

Choosing the right ITR Form for AY 2025–26: A Simple Guide

The CBDT has released the Income Tax Return forms for Assessment Year 2025–26. One big change this year affects salaried individuals and small business owners who earn long-term capital gains (LTCG) from listed shares or mutual funds. If the gains are up to Rs 1.25 lakh a year, they can now file returns using ITR-1 or ITR-4 forms.

ITR filing is mandatory for individuals who have an annual income exceeding the basic exemption limit.

There are various types of Income Tax return forms that taxpayers have to fill to complete filing Income Tax Return process.

These ITR forms are classified on the basis of the nature of income.

The Central Board of Direct Taxes (CBDT) releases a set of ITR forms tailored for different categories of taxpayers.

Choosing the right form is crucial for filing and for processing without any delays.

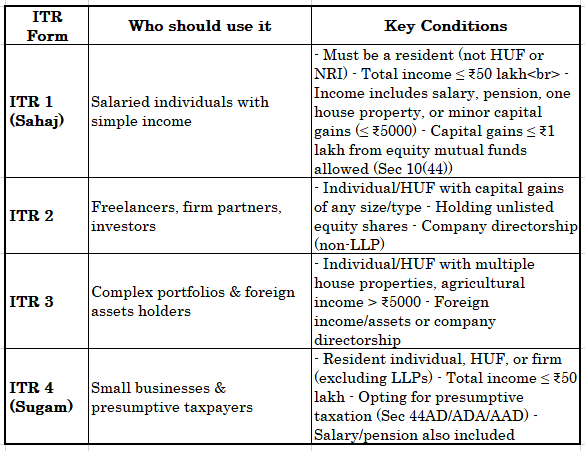
Here is a simplified guidance of the main ITR forms applicable for Assessment Year 2025–26: 


ITR-1 Form: This form is for a resident individual whose total income includes-

  • Income earned from salary or Pension.
  • Income from other sources, excluding income from winning a lottery or income from owning and maintaining race horses, is taxable under section 115BBDA or section 115E.
  • Income from One House Property; however, in this form, the loss brought forward from previous years are not eligible.
  • Income from agriculture activities up to Rs 5000.
  • The total income of the individual should not exceed 50 Lakhs.

ITR-2 Form: This form is for individuals or a HUF (Hindu Undivided Family) whose income includes:

  • Income from salary or Pension
  • Income from House Property(one or more)
  • Income from other sources, including income from winning a lottery, income from owning and maintaining horse races, or income taxable at special rates.
  • Persons who had investments in unlisted equity shares at any time during the entire financial year.
  • An individual who is a director in a company.
  • An individual who is a Resident (ROR/RNOR)or non-resident.
  • Income earned from capital gains
  • Income from foreign assets/ other foreign income.
  • Agricultural income of more than Rs 5,000/-
  • Incomes where clubbing provisions are applicable
  • Individuals having a financial interest in assets located outside India, which includes any signing authority for accounts held outside India.
  • One who desires to carry forward or bring forward loss under income from house property.
  • Any tax has been deducted under Section 194N
  • In cases where payment or deduction of tax has been deferred on ESOP (Total income can exceed 50 lakhs in this ITR Form)

ITR-3 Form: This form is to be used by either an individual or a Hindu Undivided Family who are carrying on a profession or a business. The following persons are eligible to fill this form:

  • The residential status can be either Non-resident or Resident (ROR/RNOR)
  • If a person is the director of the company.
  • Persons who had investments in unlisted equity shares at any time during the entire financial year.
  • Income from other sources
  • Income of a person who is a partner in a firm.
  • Income from salary or Pension
  • Income from House Property(one or more)
  • Total income can exceed 50 lakhs in this case.
  • Income earned from capital gains or foreign assets/foreign income.
  • Who has income under the head profits or gains of business or profession and who is not eligible to file Form ITR-1 (Sahaj), ITR-2, or ITR-4 (Sugam).
  • In short, individuals or HUFs who are not eligible to file ITR-1, ITR-2, and ITR-4 should file ITR-3

ITR-4 Form: This form is applicable to both the resident individuals and HUFs.

  • Other than LLPs, all partnership firms which are residents and have an income that is either professional or from the business.
  • Those persons who have opted for a presumptive income scheme according to Section 44AD, Section 44AE, and Section 44ADA of the Income Tax Act.
  • If the person’s business turnover exceeds Rs. 2 crores, then he is required to file ITR-3 with the Audit report and not ITR 4.
  • The total income for ITR 4 should not exceed Rs. 50 lakhs.
  • Income from One House Property(loss brought forward from previous years or carry forward of losses are not eligible in this ITR Form ).
  • Income from Salary or Pension.
  • Income from other sources. (excluding income from winning a lottery or income from owning and maintaining race horses, income taxable under section 115BBDA or 115BE).

Why it matters

Filing the right form is important, for processing of the ITR and to get refund, if applicable. If right form is not filed, it can lead to:

  • Return being marked as defective
  • Loss of deductions and refunds
  • Extra scrutiny from tax authorities

Each form aligns with specific income types and taxpayer profiles. A salaried individual with no investments doesn’t need the complexity of ITR 3. Similarly, a small business owner can save time with ITR 4 using the presumptive taxation scheme.

Tips for filing

  • Use the latest instructions issued by the Income Tax Department.
  • Double-check PAN and bank details. It speeds up refund processing.
  • Declare all sources of income, even those exempted, like interest from PPF.
  • Use Form 26AS and AIS to cross-check what the department already knows about your earnings.


SEBI opens Special Window for re-lodgement of Physical Share Transfers

Ease of Doing Investment – Special Window for Re-lodgement of Transfer Requests of Physical Shares

The Securities and Exchange Board of India (SEBI) has announced a significant update aimed at helping investors who missed earlier deadlines for transferring physical shares. In a circular dated July 2, 2025 (Ref: SEBI/HO/MIRSD/MIRSD-PoD/P/CIR/2025/97), SEBI is introducing a six-month special window to re-lodge transfer requests that were submitted before April 1, 2019 but rejected or unattended due to documentation issues.

🗓 Key Dates

  • Special window period: July 07, 2025 – January 06, 2026
  • Eligible transfers: Transfer deeds lodged prior to April 01, 2019 and returned/rejected/not processed due to deficiencies

🔍 What’s Changing?

  • Investors now get one final opportunity to re-lodge their transfer deeds.
  • All transfers under this window will be processed exclusively in demat mode.
  • Requests pending with RTAs or listed companies as of now are also covered.

🛠 Implementation Guidelines

  • Public Awareness: Stock Exchanges, RTAs, and listed companies must publicize the window bi-monthly through print and social media.
  • Dedicated Teams: RTAs and listed companies are required to create focused teams to handle these requests.
  • Monthly Reporting: RTAs/companies must submit reports to SEBI on:
  • Number of requests received, processed, approved, and rejected
  • Average processing time
  • Publicity measures taken
    (Format provided in Annexure-A of the circular)

🏛 Regulatory Backing

This move is powered by SEBI’s authority under:

  • Section 11(1) of the SEBI Act, 1992
  • Regulation 102 of the SEBI (LODR) Regulations, 2015
  • SEBI (Registrars to an Issue and Share Transfer Agents) Regulations, 1993

💡 Why It Matters

For investors who were stuck due to missed deadlines or minor procedural lapses, this is a chance to reclaim their investments and bring their holdings into the digital demat ecosystem. It also aligns with SEBI’s ongoing efforts to protect investor rights and streamline the securities market.

SEBI’s Circular: Special Window for Re-lodgement of transfer requests of Physical Shares

CBDT extends ITR filing deadline to September 15, 2025

CBDT Extends Income Tax Return Filing Deadline to September 15, 2025

Taxpayers across India can breathe a sigh of relief, as the Central Board of Direct Taxes (CBDT) has officially extended the Income Tax Return (ITR) filing deadline for Assessment Year (AY) 2025–26 from July 31, 2025, to September 15, 2025. This extension provides additional time for taxpayers to comply with new structural and content changes introduced in the revised ITR forms.

Why the Deadline has been extended?

The decision comes as a response to delays in issuing the new ITR forms and utilities, which have undergone extensive revisions this year. The Ministry of Finance has stated that these updates aim to:

  • Enhance transparency in tax reporting,
  • Simplify compliance for taxpayers, and
  • Enable more accurate reporting of income and deductions.

Since these modifications require system upgrades, the Income Tax Department needed extra time to ensure seamless integration, system readiness, and accurate reflection of TDS credits.

Official Announcement

The Income Tax Department took to social media platform X (formerly Twitter) to share the update, stating:

“This extension will provide more time due to significant revisions in ITR forms, system development needs, and TDS credit reflections. This ensures a smoother and more accurate filing experience for everyone.”

Key Takeaways

  • New Deadline: September 15, 2025
  • Reason for Extension: Delays in updated ITR forms and system readiness
  • Objective: Better compliance, transparency, and reporting accuracy

What This Means for You?

As you are yet to file your Income Tax Return (ITR), this announcement is good news! You now have additional time to:

  • Review the revised ITR forms carefully,
  • Gather necessary documents to ensure accurate filing, and
  • Avoid last-minute errors by leveraging the extended timeline.

With the extra time granted, taxpayers are encouraged to file their returns promptly instead of waiting until the last minute. Stay informed and ensure smooth tax compliance!

Source : CBDT Circular

MCA V3 Portal ushering in a significant digital transformation

The dawn of a New Era: MCA’s V3 Portal phases out V2 for enhanced Corporate Compliance

The Ministry of Corporate Affairs (MCA) has ushered in a significant digital transformation, completing the phased migration of its services from the older V2 portal to the advanced MCA21 V3 portal. This move marks a pivotal moment for businesses, professionals, and stakeholders involved in corporate governance in India, promising a more streamlined, efficient, and user-friendly experience.

A Gradual but Definitive Shift

For quite some time, the MCA has been strategically transitioning its functionalities. While LLP-related filings were among the first to move to V3, the final and most comprehensive set of 38 company e-forms, including crucial annual filing forms like AOC-4 and MGT-7, and various audit/cost audit forms, went live on 30th May, 2025. This launch to be effective (from July 14, 2025 from 12.00 a.m) renders the V2 portal obsolete for company filings, signifying the completion of a major technological overhaul.

Why the Shift? The Promise of V3

The move to V3 is not merely an aesthetic upgrade; it’s a fundamental re-engineering of how corporate compliance is managed. Here’s what makes V3 a game-changer:

Online Form Submission: A major departure from V2, V3 allows for direct online submission of forms, eliminating the need to download, fill, and then upload. This significantly reduces manual effort and potential errors.

Enhanced User Experience: V3 boasts a more intuitive and responsive web design, making navigation and filing more user-friendly. Features like e-Adjudication, e-Consultation, and a Learning Management System are integrated for a holistic experience.

Real-time Processing and Tracking: Stakeholders can now track the status of their filings in real-time, providing greater transparency and allowing for timely corrective actions if needed.

Streamlined E-payments: The payment process has been further refined for greater ease and security. Notably, the “Pay Later” option on V2 has been discontinued, emphasizing online payment modes.

Improved Data Integrity and Compliance Management: V3 incorporates advanced field-level validations and aims to minimize errors during filing. The Compliance Management System (CMS) will assist MCA in identifying non-compliant entities and issuing e-notices, strengthening the regulatory framework.

Single User ID for Multiple Roles: Professionals (CA/CS/CMA) who are also directors can now manage their various roles through a single user ID, simplifying their interactions with the portal.

Increased Accessibility and Transparency: The portal aims to improve the accessibility of public documents and offers better resolution of public grievances.

Key Dates and Important Actions for Stakeholders

To ensure a smooth transition, the MCA had laid out a clear timeline and advised stakeholders on crucial actions:

V2 Filing Disabled: Company e-filings on the V2 portal were disabled from June 18, 2025. It was critical for all Service Request Numbers (SRNs) to be clear of “pending payment” or “re-submission” status before this date.

Offline Payments Discontinued: The “Pay Later” option in V2 was stopped from June 8, 2025, mandating online payments for all filings.

V3 Portal Downtime: A scheduled downtime for the V3 portal occurred from July 9 to July 13, 2025, to facilitate the final rollout of the new forms.

User ID and DSC Updates: Stakeholders were strongly advised to create a new user ID or upgrade/merge their existing V2 ID to a “Business User” category in V3 and associate their Digital Signature Certificate (DSC) without fail.

SRN Updates: SRNs requiring updates regarding investor or subsidiary details needed to be completed by June 17, 2025, to avoid being marked as “NTBR” (Not to Be Registered).

Navigating the new landscape: What to expect

While V3 promises significant improvements, like any large-scale system migration, initial teething troubles are not uncommon. Stakeholders should be prepared for:

Familiarization with New Interface: It will take some time for users to get accustomed to the new layout and functionalities of V3.

Technical Glitches: While the MCA has taken steps to ensure a smooth transition, occasional technical issues related to login, DSC association, or form submission might arise.

Proactive Engagement: Users are encouraged to utilize the FAQs and support resources provided by MCA and professional bodies to resolve any issues promptly.

The phasing out of the V2 portal and the full embrace of V3 signify the MCA’s commitment to digital governance and ease of doing business in India. This advanced platform is set to enhance transparency, streamline compliance processes, and contribute to a more robust corporate ecosystem. Embracing this new era with readiness and adaptability will be key for all stakeholders.

Source: MCA Circular