India’s foreign exchange reserves surged by whopping $2.671 billion to $366.781 billion for the week ended March 2017 on account of increase in foreign currency assets, the Reserve Bank said today.
In the previous week, the reserves had risen by $98.6 million to $364.109 billion.
Foreign currency assets (FCAs), a major component of the overall reserves, rose by $2.645 billion to $343.101 billion in the reporting week, the RBI said.
Expressed in US dollar terms, FCAs include the effects of appreciation/depreciation of non—US currencies, such as the euro, pound and the yen held in the reserves.
Gold reserves remained unchanged at $19.914 billion.
The special drawing rights with the International Monetary Fund was up by $10 million to $1.444 billion; India’s reserve position with the Fund, too, increased by $15.9 million to $2.320 billion, RBI said.
Non-banking finance companies could well outpace commercial banks, struggling to grow amid muted loan expansion and bad loan burden, said global rating company Moody’s.
But, NBFCs too are exposed to certain risks emanating from their fast-faced growth in loan against properties, which they are in a position to mitigate with larger share in mortgaged loans.
Non-bank financial companies (NBFCs) in India (Baa3 positive) will demonstrate broadly stable asset quality, but delinquencies will likely rise over the next 1-2 quarters, as demonetisation adversely affects collections across asset classes, said Moody’s Investors Service in a note.
“While the 90+days delinquency rate in the commercial vehicle (CV) loan segment largely stabilized in the first half of the fiscal year ending 31 March 2017, such delinquencies should build up in the near term due to the adverse impact of demonetisation and tighter recognition norms for non-performing assets (NPAs),” said Alka Anbarasu, a Moody’s Vice President and Senior Analyst.
Moody’s also notes that the growth in loans against property (LAP) has outpaced overall retail credit growth in recent years, but relatively loose underwriting practices–combined with intensifying competition – will translate into higher asset quality risk for this segment.
Furthermore, over the past 3 years, NBFCs have gained some market share in the origination of retail lending, on the back of the faster growth exhibited by such entities when compared to the banks.
This is particularly the case when compared to public sector banks, which face significant challenges on their asset quality and overall solvency profiles.
“Nevertheless, we expect that competitive pressures from the banking sector will remain intense as banks are increasing targeting of the retail segment to offset weakness in their corporate lending. In addition, retail lending, particularly housing loans, is more capital efficient for the banks,” said Anbarasu.
And, while the NBFCs’ capitalization levels are adequate, with average Tier 1 ratios in excess of 14%, capital generation will lag credit growth. Access to external capital will therefore be key in sustaining the NBFCs’ growth momentum.
On funding, Moody’s expects that the NBFCs’ funding profiles will broadly remain stable, and funding costs should moderate gradually, given the reduction in systemic rates.
In addition, the NBFCs’ profitability and capital, as well as funding and liquidity levels, will stay broadly stable.
The NBFCs are growing at a fast pace, and have gained market share in the origination of retail credit. And, their share of LAP pose a potential source of risk, with such loans growing at a rapid compound annual growth rate of about 25% over the last four years compared to 17% for overall retail credit.
Moody’s says that the NBFCs’ exposure to potential risks from LAP is broadly offset by their share of stable mortgage loans, because favorable demographics and economics, tax incentives for home loans and an increasingly affordable housing segment support asset quality.
Moody’s expects that the loss given default for both home loans and LAP will be limited, in light of the underlying collateral.
There are a few aspects that are common to Indian organisations that have a successful analytics strategy in place.
Non-banking finance companies could well outpace commercial banks, struggling to grow amid muted loan expansion and bad loan burden, said global rating company Moody’s.
But, NBFCs too are exposed to certain risks emanating from their fast-faced growth in loan against properties, which they are in a position to mitigate with larger share in mortgaged loans.
Non-bank financial companies (NBFCs) in India (Baa3 positive) will demonstrate broadly stable asset quality, but delinquencies will likely rise over the next 1-2 quarters, as demonetisation adversely affects collections across asset classes, said Moody’s Investors Service in a note.
“While the 90+days delinquency rate in the commercial vehicle (CV) loan segment largely stabilized in the first half of the fiscal year ending 31 March 2017, such delinquencies should build up in the near term due to the adverse impact of demonetisation and tighter recognition norms for non-performing assets (NPAs),” said Alka Anbarasu, a Moody’s Vice President and Senior Analyst.
Moody’s also notes that the growth in loans against property (LAP) has outpaced overall retail credit growth in recent years, but relatively loose underwriting practices–combined with intensifying competition – will translate into higher asset quality risk for this segment.
Furthermore, over the past 3 years, NBFCs have gained some market share in the origination of retail lending, on the back of the faster growth exhibited by such entities when compared to the banks.
This is particularly the case when compared to public sector banks, which face significant challenges on their asset quality and overall solvency profiles.
“Nevertheless, we expect that competitive pressures from the banking sector will remain intense as banks are increasing targeting of the retail segment to offset weakness in their corporate lending. In addition, retail lending, particularly housing loans, is more capital efficient for the banks,” said Anbarasu.
And, while the NBFCs’ capitalization levels are adequate, with average Tier 1 ratios in excess of 14%, capital generation will lag credit growth. Access to external capital will therefore be key in sustaining the NBFCs’ growth momentum.
On funding, Moody’s expects that the NBFCs’ funding profiles will broadly remain stable, and funding costs should moderate gradually, given the reduction in systemic rates.
In addition, the NBFCs’ profitability and capital, as well as funding and liquidity levels, will stay broadly stable.
The NBFCs are growing at a fast pace, and have gained market share in the origination of retail credit. And, their share of LAP pose a potential source of risk, with such loans growing at a rapid compound annual growth rate of about 25% over the last four years compared to 17% for overall retail credit.
Moody’s says that the NBFCs’ exposure to potential risks from LAP is broadly offset by their share of stable mortgage loans, because favorable demographics and economics, tax incentives for home loans and an increasingly affordable housing segment support asset quality.
Moody’s expects that the loss given default for both home loans and LAP will be limited, in light of the underlying collateral.
IMF in its note titled ‘Global Prospects and Policy Challenges’ said, “Further subsidy reduction and tax reforms, including a robust design and full implementation of the Goods and Services Tax (GST), are necessary to attain medium-term fiscal consolidation plans.”
India’s economic growth is expected to pick up once the effects of cash shortages linked to the currency exchange initiative fade, the International Monetary Fund (IMF) has said. Prime Minister Narendra Modi on November 8 had announced scrapping of old Rs 500 and Rs 1000 notes, pulling out 86 per cent of the total currency in circulation.
Noting that India’s fiscal deficit is expected to continue narrowing in the near-term, the IMF in its note titled ‘Global Prospects and Policy Challenges’ said, “Further subsidy reduction and tax reforms, including a robust design and full implementation of the Goods and Services Tax (GST), are necessary to attain medium-term fiscal consolidation plans.”
It further observed that in some emerging economies like China and India reducing excessive corporate leverage and improving bank’s balance sheets or adopting more prudent risk-management practices, including to reduce currency and maturity balance sheet mismatches, will help reduce vulnerabilities to global financial conditions, possible capital outflows, and sharp currency movements.
The government last month pegged GDP growth at 7.1 per cent for 2016-17 despite the note ban. The Central Statistics Office (CSO) had put the figure for October-December at 7 per cent, compared to 7.4 per cent in the second quarter and 7.2 per cent in the first.
India’s growth was higher than China’s 6.8 per cent for October-December of 2016. The growth numbers were better than those projected by RBI (6.9 per cent) and international agencies like IMF (6.6 per cent) and OECD (7 per cent) in view of the cash recall. The Organisation for Economic Cooperation and Development (OECD) in February last year had projected the country’s growth at 7.4 per cent for 2016-17. Buoyed by higher-than-expected growth, Finance Minister Arun Jaitley has also said a 7 per cent expansion in the third quarter belies the exaggerated claims of note ban impact on the rural economy.
– Nifty surpasses March 2015 peak, Sensex gains as much as 2.1%. – Bigger-than-expected victory seen as endorsement of reforms
Indian equities rallied to a record and the rupee climbed the most since 2013 after Prime Minister Narendra Modi’s resounding victory in state elections boosted expectations for a continuation of his reform agenda.
The NSE Nifty 50 Index climbed 1.7 percent to 9,087, crossing its March 2015 record close, as the market reopened after a holiday. The India VIX Index, a gauge of expected stock-price swings, touched an all-time low. The rupee surged 1.2 percent to 65.8175 per dollar, the strongest level since November 2015. The central bank was seen buying dollars in early trade to cap gains but moved away later, Mumbai-based traders said.
“This win will give Modi the confidence to push ahead with more reforms and not pursue populist policies,” Sampath Reddy, chief investment officer at Bajaj Allianz Life Insurance Co., said by phone. The insurer, which oversees 480 billion rupees ($7.3 billion) of assets, is bullish on financial-services companies and metal producers, he said.
Modi’s Bharatiya Janata Party won 312 seats in the 403-member assembly of Uttar Pradesh, according to the Election Commission of India, up from 47 in 2012. The results in India’s largest state were seen as a litmus test of Modi’s popularity and reforms, including opening up the country to more foreign investment and seeking to introduce a goods and services tax, ahead of general elections in 2019.
While exit polls released last week suggested a large BJP victory was possible in Uttar Pradesh, the scale of the win was stark in a state that has long been divided along religious and caste lines. It is also a repudiation of political foes who assumed that Modi’s disruptive Nov. 8 move to junk high-value currency notes would be politically unpopular.
“Uttar Pradesh is a state where mandates have tended to be mostly divisive, so the result is a mandate for development, which has been sorely missing in the state,” Gautam Sinha Roy, a fund manager at Mumbai-based Motilal Oswal Asset Management Co., said by phone. “Markets will now start assigning higher probability to a BJP victory in the 2019 polls.”
India’s economic growth has been 7 percent or more in each of the last four quarters, which has helped lure $3.4 billion of foreign funds into local stocks and bonds this year. Mutual funds bought shares for seven months through February, including a record $2.1 billion in November. The S&P BSE Sensex has risen 11 percent in 2017, and the rupee is up 3.2 percent against the dollar.
“We expect the Reserve Bank of India to more actively cap further rupee gains given the sharp swing higher in the real effective exchange rate in recent months,” Divya Devesh, an Asia FX strategist at Standard Chartered Bank in Singapore, said by e-mail. He forecasts the rupee at 69 rupees to the dollar by year-end.
Pricey Valuations
The Nifty came off an intraday high of 9,122.75 as investor focus turned to a near-certain interest rate hike from the Federal Reserve this week and expected revival in corporate profitability. The Nifty and the Sensex are valued at about 21 times forward earnings, the highest level since April 2010.
“Valuations look stretched and investors are cautious with the Fed meeting round the corner,” said Sushant Kumar, a fund manager at RAAY Global Investments Pvt. in Mumbai. “Stocks have priced in the expected increase in rates. The focus is on Fed’s outlook.” The Nifty may reach 10,000 by March 2018, accompanied by as much as 14 percent expansion in earnings of its 50 members, he said.
Still, the scale of the BJP’s victory paves the way for further reforms and should lead to more inflows, supporting asset prices, according to Vikas Gupta, chief investment strategist at OmniScience Capital Pvt. in Mumbai.
“For international investors, India is one of the few emerging markets that has everything going for it: demographics, economics and politics,” he said. “With elections settled, it is clear that the federal government is now going to be fully in charge of the parliament.”
In the past six months, several venture capital (VCs) funds have raised money or are in the process of raising money. These include funds from IDG Ventures, DSG Consumer Partners, Orios Venture Partners, Kae Capital, Blume Ventures, Saama Capital, Fireside Ventures, Stellaris Venture Partners, Endiya Partners and Pravega Ventures.
What’s common between them is Sidbi, the lending institution managing several start-up funds, including the government’s, which plays an anchor investor to many of these funds with a 15-20 per cent stake. This is helping these funds raise money from other domestic investors — family offices and high networth individuals (HNIs).
‘‘Fundraising is not easy, especially for smaller VC firms. They don’t get large institutional investors; they get family offices and HNIs,” says a VC. Having an institution like Sidbi comforts other local investors.
‘‘Sidbi does extensive amount of due-diligence, reporting, appoints board members. They have a proper investment committee. So, you have comfort that there’s institutional due-diligence on the fund,” says Rehan Yar Khan, managing partner, Orios Venture Partners.
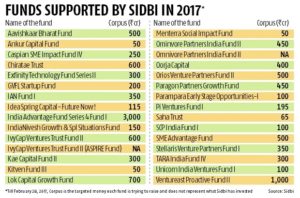
In February, Sidbi said its fund of funds operations has sanctioned Rs 1,112 crore to 30 funds in FY17, double of Rs 607 crore for 16 funds it did in FY16. Sidbi manages many fund of funds, including the government’s Rs 10,000-crore fund of funds for start-ups.
The funds, which have received Sidbi’s commitment under this programme, are Orios Venture Partners Fund II (Rs 50 crore), Kae Capital (Rs 45 crore), and two little known funds, Saha Trust (Rs 10 crore) and Kitven Fund III (Rs 5 crore), Sidbi disclosed in response to an RTI query from Business Standard. There are others like Blume Ventures, IDG Ventures, India Quotient, which have received Sidbi’s funding.
Interestingly, several funds — maiden funds and second funds — have hit the market in the past one year, all targeting domestic investors. Yet, all of them are able to raise money and announced their first or final close, which shows the increasing depth of domestic investors.
These include professionals in large firms, like Infosys founders, who have made money through ESOPs, family offices of traditional business families and others which are starting to get organised.
Many wealth management and advisory firms have come up, who are able to reach these family offices in a more effective way. But are we seeing too many funds raising too much capital?
‘‘There’s a big need for early stage capital. In the US, the size of the VC market is $25-26 billion and the seed capital of $22 billion. As opposed to that, we are at a pittance. The game has not even started here,” says another VC. Besides, bigger VC firms like Accel, Sequoia also do seed-stage deals, but mostly do VC.
Official data released on Tuesday showed that demonetisation hasn’t pushed the economy into a retreat as most feared, with its short-term adverse impact. (Source: Reuters)
Official data released on Tuesday showed that demonetisation hasn’t pushed the economy into a retreat as most feared, with its short-term adverse impact to a large extent restricted to construction and financial services. Real GDP growth in the December quarter, in the midst of which the note ban came into effect, came in at a respectable 7% (though lower than 7.4% in the previous quarter) and the gross value added (GVA) was 6.6%, with the difference explained by robust indirect taxes and reining in of subsidies.
Upward revision of GVA estimates for 2015-16 led to downward corrections in GVA for Q1 and Q2 of the current fiscal but despite this, there were marginal upward revisions in the rates of GDP expansion in these quarters, thanks to a surge in indirect taxes.
Solid performance by the “agriculture and allied sectors”, pump-priming by the government on the consumption side, better-than-expected performance by mining and manufacturing sectors and a seasonal — though larger-than-usual — pick-up in private consumption masked whatever negative effect the note swap exercise had on the economy, going by the Central Statistics Office’s data.
However, as the GDP was slowing even before demonetisation and the note swap has indeed had an incremental adverse effect on it, both GDP and GVA growth for 2016-17 have been projected to be much lower than in the previous year. In the second advance estimate, the CSO has kept the GDP growth estimate for the current financial year at 7.1%, the same as in the first advance estimate released in early January, and GVA growth at 6.7%. But given that 2015-16 GDP growth, which was seen at 7.6% at the time of the first advance estimate, was subsequently revised to 7.9%, the CSO’s latest take on 2016-17 growth is virtually more sanguine than its previous estimate.
While the CSO’s GDP estimate for 2016-17 is evidently higher than that of most others, many analysts said the growth assumed by it for the second half (6.8%) was optimistic. “Given the fact that the fall from H1 to Q3 is not much, I don’t think that we should then necessarily assume that the rebound in Q4 is going to be very sharp,” said Aditi Nayar, economist at Icra. Stating that the GDP number is better than expected, Saugata Bhattacharya, chief economist at Axis Bank, said, “Since growth slowdown (due to demonetisation) has been shallower than expected, and in line with the RBI’s projections, the probability of rate cuts going ahead has come down.”
The minutes of the monetary policy committee’s meeting released last week indicated that it changed its stance from “accommodative” to “neutral” because the growth drag from demonetisation is expected to fade soon. India Ratings reiterated its view that “much of the impact of demonetisation will be visible in Q4FY17 leading to an overall GDP growth of 6.8% in 2016-17”.
Economic affairs secretary Shaktikanta Das said: “This year’s GDP (growth) is around 7%, based on available numbers. Nothing can be deciphered on anecdotal evidence. Demonetisation only impacted consumption in some cities, since most purchases happened on credit or debit cards. The so-called negative impact, if relevant, was only temporary.”
The 7% GDP growth forecast for the third quarter helped India maintain the coveted tag of the world’s fastest-growing major economy despite demonetisation, better than China’s 6.8% in the December quarter.
While analysts pointed out the lack of congruity between the CSO’s estimate and other high-frequency data and corporate results, chief statistician TCA Anant said all available data have been made use of in the second advance estimate, including corporate performance up to the December quarter, sales of commercial vehicles, railway freight, etc, for the first “9/10 months of the financial year”.
According to the CSO, with production growth of foodgrains during 2016-17 kharif and rabi seasons being 9.9% and 6.3%, respectively, the farm sector grew a robust 6% in Q3 from 3.8% in the previous quarter and compared with a 2.2% contraction in the year-ago quarter. Despite the anecdotes of industrial clusters hit by the note ban during the period, manufacturing grew a healthy 8.3% in Q3 on a robust base of 12.8% in the year-ago quarter and compared with 6.9% in Q2 this fiscal. Mining also posted a smart recovery from a fall of 1.3% in Q2 to a robust expansion of 7.5% in Q3. The bad performers on the output side was “financial services, etc”, which posted a modest 3.1% growth in Q3 compared with 7.6% in the previous month, and construction which grew just 2.7% in the December quarter.
Government final consumption expenditure (GFCE) posted a 19.9% growth in Q3 against 15.2% in the previous quarter, the CSO said. Given that 17% growth in GFCE is estimated for the whole of 2016-17, it needs to grow at 17.4% in Q4. Considering that the Centre, as is seen from the April-January fiscal data separately released by the Controller General of Accounts, has slowed down spending in the later months of the year, the spending boost must come from PSUs.
Although both Dussehra and Diwali fell in the December quarter, the 10.1% growth reported by CSO in the private consumption expenditure looked puzzling to most analysts (but some said use of old notes for consumption might have contributed to the rise). So was the 3.5% growth in gross fixed capital formation, which was declining for the previous three quarters.
Given that nominal GDP growth has been projected at 11.5% for 2016-17, compared with 10% in the last fiscal, it may offer more leeway to the government to improve spending in the next fiscal and yet contain fiscal deficit, which is expressed as a ratio of the nominal GDP, at the targeted 3.2%.
Discrepancies — the difference between the supply and demand side of GDP — turned negative after a gap of four quarters (-Rs 6,767 crore) in the December quarter, compared with Rs 45,378 crore in the second quarter and Rs 30,645 crore in the first quarter. In the last quarter of 2015-16, discrepancies touched a massive Rs 1,43,210 crore, causing a flutter then and raising doubts about the credibility of the country’s data collection mechanism. When private final consumption expenditure, gross fixed capital formation, government final consumption expenditure, change in stocks, valuables, and net exports exceed the overall GDP (based on the supply side data), discrepancies turn negative.
Analysts expect the exports sector to contribute more to GDP growth in the coming quarters, despite the demonetisation blues, thanks primarily to a favourable base. In real terms, the export growth for 2016-17 has been projected at 2.3%, compared with -5.4% in the last fiscal. Despite demonetisation, merchandise exports rose 2.3% in November, 5.7% in December and 4.3% in January.

 India’s foreign exchange reserves surged by whopping $2.671 billion to $366.781 billion for the week ended March 2017 on account of increase in foreign currency assets, the Reserve Bank said today.