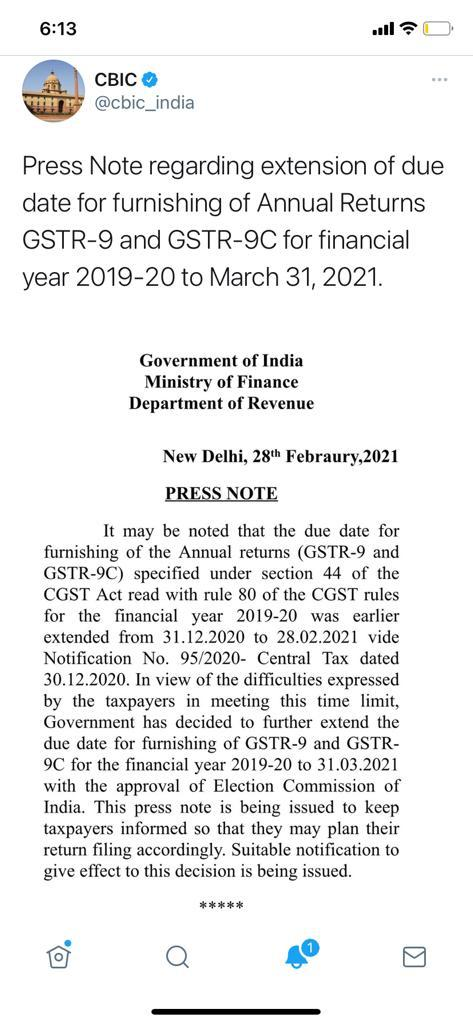
CBIC had extended, vide Press Note regarding extension of due date for furnishing of Annual Returns GSTR-9 and GSTR-9C for financial year 2019-20 to March 31, 2021.
This is the second extension given by the government. The deadline was earlier extended from December 31,2020 to February 28.
Taxpayers can make GST payments through challan every month either by self-assessment of monthly liability or 35 per cent of net cash liability of previous filed GSTR-3B of the quarter. Quarterly GSTR-1 and GSTR-3B can also be filed through an SMS.
The government has launched the Quarterly Return Filing and Monthly Payment of Taxes (QRMP) scheme in a bid to ease the return filing experience of the Goods and Services Tax (GST) taxpayers. The scheme will come into effect from January 1, 2021, it will impact 9.4 million taxpayers, who constitute 92% of the total tax base of GST and have an annual aggregate turnover (AATO) of up to Rs 5 crore.
With the introduction of the QRMP scheme, sources say, small taxpayers would need to file only eight returns – four each GSTR-3B and GSTR-1 – instead of the existing requirement of 16 returns in a financial year, of which 12 are GSTR-3B. The new scheme would also significantly reduce taxpayers’ professional expenses on return filing as they would have to file just half the number of returns as against the current requirement of 16. Also, the QRMP scheme would be available on the common GST portal with the facility to opt-in and opt-out, and opt-in again, as per a taxpayer’s wishes.
The scheme would bring in the concept of providing input tax credit (ITC) only on the reported invoices, thus putting a curb on the menace of fake invoice frauds. Additionally, the QRMP scheme is also likely to have the optional feature of Invoice Filing Facility (IFF) to mitigate the business-related hardships of the small and medium taxpayers. Under the IFF, taxpayers who opt to file their returns quarterly would be able to upload and file such invoices even in the first and second month of the quarter for which there is a demand from the recipients.
The taxpayers won’t need to upload and file all the invoices of the month. Only those invoices, which are required to be filed in IFF as per the recipients’ demands, are to be uploaded. The remaining invoices of the first and second months can be uploaded in the quarterly GSTR-1 return.
The QRMP scheme is based on the existing return system with suitable modifications in a bid to give much-needed flexibility to the small and medium enterprises with regards to GST compliance. It was approved in principle by the GST Council in its 42nd meeting on October 5, 2020.
In a statement, the Department of Revenue (DoR) reiterated that there will be no extra compliance burden on the taxpayers for GST turnover displayed in the Form 26AS, which is an annual consolidated tax statement that can be accessed from the income-tax website by taxpayers using their Permanent Account Number (PAN).
Prime Minister Narendra Modi launched GST into operation on the 1 st of July, 2017. GST was publicised as ‘one nation, one tax’ by the government, aimed to provide a simplified, single tax regime. GST is a dual levy where the Central Government levies and collects Central GST (CGST) and the State levies and collects State GST (SGST) on intra-state supply of goods or services. Centre also levies and collects Integrated GST (IGST) on inter-state supply of goods or services. The GST Portal is a website where all the compliance activities of GST can be done before and after GST login. Activities such as the GST registration return filing, payment of taxes, application for refund, etc. can be done on the GST Portal.
GSTN, recently launched many new features on GSTN portal. One of its features is that GSTN portal is now showing aggregate annual turnover for previous financial year after logging in to the portal.
The GST turnover is being shown in 26AS just for the information of the taxpayer. DoR acknowledged that there may be some differences in GSTR-3Bs filed and the GST shown in the Form 26AS but it can’t happen that a person shows turnover of crores of rupees in GST and doesn’t pay a single rupee of income tax.
The DoR said that the notified Income Tax Return for the current AY 2020-21 already requires reporting of GST outward supplies in the Schedule GST.
Therefore, the information displayed in Form 26AS would provide ease of compliance to the taxpayers in filling Schedule GST.
The revenue department has noticed that many unscrupulous persons are trying to avail or pass on input tax credit fraudulently by generating fake invoices and has already formulated a strategy for identifying these fake invoice generators which inter alia takes into account the income tax profiles of the suspected fake invoice generators.
These persons in most of the cases never file their income tax returns or disclose very meagre taxable income in the income tax return.
The suspected fake invoice generators are being identified for serious action under GST and other laws including suspension of their GST registration based on the fact that whether their income tax payment commensurate with the expected profit margin on turnover reported by them in the GST returns, the DoR said.
What “aggregate turnover” means?
“Aggregate turnover” is the aggregate value of all taxable supplies, exports of goods or/and services or both, exempt supplies and interstate supplies of persons having the same PAN, to be computed on all India basis. However, such taxable supplies do not include the value of inward supplies on which GST is being paid under reverse charge basis. The aggregate turnover also excludes Central tax, State tax, Union territory tax, Integrated tax and cess.
Basically, sum of the following shall be considered as an aggregate turnover:
Value of all taxable supplies of goods and services
Value of all Inter-state supplies
Value of all exempt supplies of goods and services
Value of all export of goods or services or both
However, the following items would be excluded from Turnover:
Inward supplies on which taxes are paid under reverse charge
Taxes and cesses under GST
Interstate supply of services
Transactions which are neither supply of goods or service.
Supplies provided outside India or received outside India
Extrapolation of Turnover at GSTIN level (for those who have not filed all the returns as per their eligibility or liability)
GSTIN-wise GSTR-3B turnover for FY 2019-2020 has been extrapolated by the formula: >> Total turnover declared as per all GSTR-3B filed / No. of GSTR-3B filed) X No. of GSTR-3B eligible or liable to be filed
GSTIN-wise CMP-08 outward supply has been extrapolated by the formula: >> Total outward supply declared as per all CMP-08 filed / No. of CMP-08 filed) X No. of CMP- 08 eligible or liable to be filed
Added both the values of S. No. (a) and S. No. (b).
For those taxpayers who have filed all the returns as per their respective eligibilities, value of S. No. (c) will be the actual turnover)
Aggregation of extrapolated turnover at PAN level or Annual Aggregate Turnover Resultant values as per S.No. (c) above are aggregated or rolled up at PAN level to arrive at the Annual Aggregate Turnover.
What is the relevance of knowing aggregate turnover?
The aggregate turnover is a crucial parameter for determining the following aspects:
Determining whether registration is required or not-
Aggregate Turnover is relevant for a person to determine threshold limit to obtain registration under GST.
Threshold turnover limit for exclusively supply of goods = Rs 40 lakh (Rs 20 lakh in case of supplies effected from special category states)
Threshold turnover limit for supply of Services or (goods and services both): Rs 20 lakh (Rs 10 lakh in case of supplies effected from special category states)
Determine the limit of composition levy – Threshold limit to opt for composition scheme: Rs 1.5 crore in a financial year (Rs 75 lakh in case of supplies effected from special category states).
To determine a “Taxable person” – Section 2 of CGST Act defines the “taxable person” as a person who has obtained registration or is liable to register as per section 22 and 24 of CGST Act. Here the Section 22 provides a liability to register when the tax payer’s turnover exceeds the limit as determined in certain cases. This is again based on aggregate turnover.
Calculation of Late fee –
Under section 33 any registered taxable person person who fails to file the return u/s 30 i.e Annual return shall be liable to pay late fees of Rs. 100 for every day when such failure continues subject to a maximum of an amount of 0.25% of his aggregate turnover.
This can escalate the amount of late fee because aggregate turnover will include all supplies except reverse charge.
To determine whether Audit is required –
Registered persons with an aggregate turnover exceeding the prescribed GST audit limit of Rs 2 Crore during a financial year are liable for GST Audit. The turnover limit of Rs 2 Crore is same for the registered tax persons across all States and UTs. Thus, no separate turnover limit is defined for Special Category States for GST Audit.
Therefore, it is advised to carry on the computation of aggregate turnover accurately as the same will be used at a number of places which will in turn determine the tax liability of a person.
The govt has given a suitable extension for annual compliance under GST laws as well as income tax laws due to disruptions caused by coronavirus.
The government on Saturday said due dates for filing income tax returns and tax audit reports for FY20 for various classes of tax payers have been extended to give more time for tax payers to comply.
The government also, on advice from the federal tax body, the Goods and Services Tax (GST) Council, extended the due date for filing annual return for FY19 from 31 October to 31 December, finance ministry said.
For filing income tax returns for FY20, individuals who are not required to conduct a tax audit report will now get time till 31 December. The original due date of 31 July was earlier extended to 30 November.
Tax payers who are required to file their tax audit reports—professionals with gross receipts more than ₹50 lakh and those running businesses with sales up to ₹1 crore—have also got extra time. They can now file their tax returns by 31 January. The earlier deadline, after one extension, was 30 November.
Assessees who enter into international transactions or specified domestic transactions and are required to file tax audit reports, have also been given extra time to file their FY20 tax returns. As per Saturday’s announcement, they can file their tax returns for FY20 by end of January.
“Consequently, the date for furnishing of various audit reports under the Income Tax Act including tax audit report and report in respect of international or specified domestic transaction has also been extended to 31 December, 2020,” said the finance ministry statement.
The ministry also gave extra time for small tax payers to pay their self- assessment tax. This facility is available only to those with self-assessment tax liability up to ₹1 lakh. Accordingly, those who are liable to get tax audit done, can pay self assessment tax by end of January and others can pay by end of December. Finance ministry said it will notify these changes.
The government also said it has been receiving requests for more time to file GST annual return and the reconciliation statement for FY19. Accordingly the due date for the same has been extended from 31 October to 31 December, said the ministry.
Filing annual return (form GSTR-9/GSTR-9A) for FY19 is optional for taxpayers who had sales below ₹2 crore. Filing of reconciliation statement in form 9C is optional for the taxpayers with sales up to ₹5 crore, said the ministry.
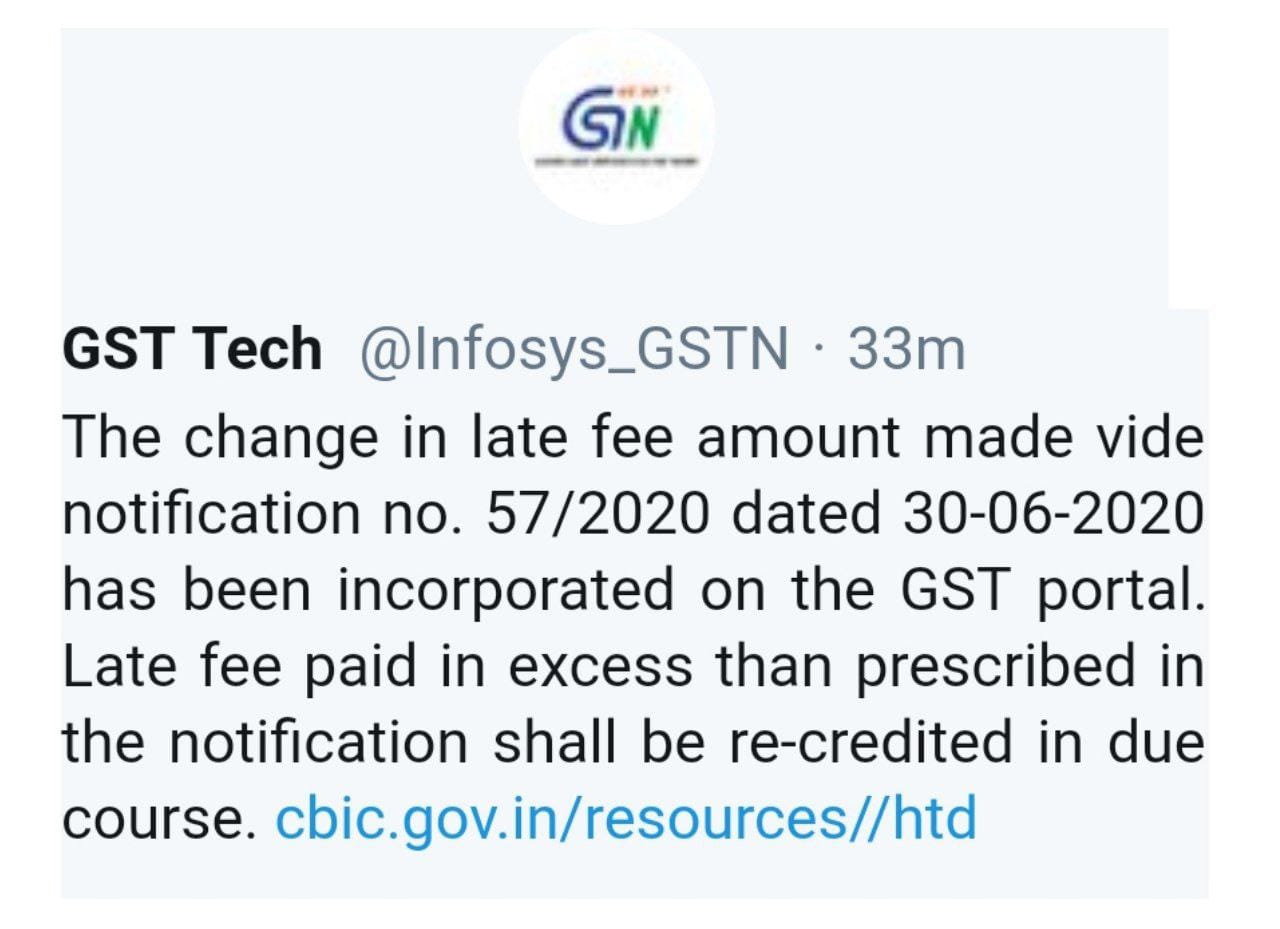
The change in late fee amount made vide notification no. 57/2020 dated 30-06-2020 has been incorporated on the portal. Late fee paid in excess than prescribed in the notification shall be re-credited in due course.
CBIC had vide Noti 57/2020 has stated that that maximum Late Fee for Form GSTR 3B has been capped at Rs. 500 for tax period July 2017 to July 2020 subject to returns being filed before 30th September 2020.
But portal was not updated and it has levied late fees as per old calculation. Hence, GSTN Tech twitter posted that “The change in late fee amount made vide notification no. 57/2020 dated 30-06-2020 has been incorporated on the GST portal.
Late fee paid in excess than prescribed in the notification shall be re-credited in due course.”
[To be published in the Gazette of India, Extraordinary, Part II, Section 3, Sub-section (i)] Government of India Ministry of Finance (Department of Revenue) Central Board of Indirect Taxes and Customs Notification No. 57/2020 – Central Tax
New Delhi, the 30th June, 2020
G.S.R…..(E).— In exercise of the powers conferred by section 128 of the Central Goods and Services Tax Act, 2017 (12 of 2017) (hereafter in this notification referred to as the said Act), read with section 148 of the said Act, the Government, on the recommendations of the Council, hereby makes the following further amendments in the notification of the Government of India in the Ministry of Finance (Department of Revenue), No. 76/2018– Central Tax, dated the 31st December, 2018, published in the Gazette of India, Extraordinary, Part II, Section 3, Sub- section (i) vide number G.S.R. 1253(E), dated the 31st December, 2018, namely :–
In the said notification, after the third proviso, the following provisos shall be inserted, namely: –
“Provided also that for the class of registered persons mentioned in column (2) of the Table of the above proviso, who fail to furnish the returns for the tax period as specified in column (3) of the said Table, according to the condition mentioned in the corresponding entry in column (4) of the said Table, but furnishes the said return till the 30th day of September, 2020, the total amount of late fee payable under section 47 of the said Act, shall stand waived which is in excess of two hundred and fifty rupees and shall stand fully waived for those taxpayers where the total amount of central tax payable in the said return is nil:
Provided also that for the taxpayers having an aggregate turnover of more than rupees 5 crores in the preceding financial year, who fail to furnish the return in FORM GSTR-3B for the months of May, 2020 to July, 2020, by the due date but furnish the said return till the 30th day of September, 2020, the total amount of late fee under section 47 of the said Act, shall stand waived which is in excess of two hundred and fifty rupees and shall stand fully waived for those taxpayers where the total amount of central tax payable in the said return is nil.”.
2. This notification shall be deemed to have come into effect from the 25th day of June, 2020.
[F. No. CBEC-20/06/08/2020-GST]
(Pramod Kumar)
Director, Government of India
Note: The principal notification No. 76/2018-Central Tax, dated 31st December, 2018 was published in the Gazette of India, Extraordinary, vide number G.S.R. 1253(E), dated the 31st December, 2018 and was last amended vide notification number 52/2020 – Central Tax, dated the 24th June, 2020, published in the Gazette of India, Extraordinary, Part II, Section 3, Sub-section (i) vide number G.S.R.405 (E), dated the 24th June, 2020.
The ministry further said it has also taken a note of difficulties and concerns expressed by the taxpayers regarding filing of GSTR-3B and other returns.
The 40th GST Council met under the Chairmanship of Union Finance & Corporate Affairs Minister Smt Nirmala Sitharaman through video conferencing here today- 12th June 2020. The meeting was also attended by Union Minister of State for Finance & Corporate Affairs Shri Anurag Thakur besides Finance Ministers of States & UTs and senior officers of the Ministry of Finance& States/ UTs.
GST Council, has recommended to reduce / waive the interest/ late fee for delayed filing of GSTR 3B by small taxpayers (having turnover upto Rs. 5 crores) for the tax period from July 2017 to July 2020, as under:
Reduction in Late Fee for Past Returns (July 2017 to January 2020)
As a measure for trade facilitation and to clean-up the pendency in filing of GSTR 3B for the period from July 2017 to January 2020, the GST Council has recommended to reduce/ waive the late fee for past returns, as under:
a) ‘NIL’ late fee if there is no tax liability;
b) Maximum late fee capped at Rs. 500/- per return if there is any tax liability.
The reduced rate of late fee would apply for all the GSTR-3B returns furnished between 01.07.2020 to 30.09.2020.
Relief for filing of returns for February – April 2020
Further GST Council has recommended to provide relief for small taxpayers (having turnover upto Rs. 5 Crores) by way of reduced interest of 9% in lieu of 18% upto 30 Sept. 2020, for late filing of returns for the tax periods February, March and April 2020. This interest shall be charged beyond specified last date (staggered upto 6th July 2020) for filing of GSTR 3B return for the said tax periods.
Relief for filing of returns for May – July 2020
Also, GST Council has recommended to provide relief for small taxpayers (having turnover upto Rs. 5 Crores) by way of waiver of interest and late fee upto 30 Sept. 2020, for late filing of GSTR 3B return for the tax periods May, June and July 2020.
Recommendations of GST council related to Law & Procedure
The GST Council has made the following recommendations on Law & Procedures changes.
Measures for Trade facilitation:
Reduction in Late Fee for past Returns:
As a measure to clean up pendency in return filing, late fee for non-furnishing FORM GSTR-3B for the tax period from July, 2017 to January, 2020 has been reduced / waived as under: –
i) ‘NIL’ late fee if there is no tax liability;
ii) Maximum late fee capped at 500/- per return if there is any tax liability.
The reduced rate of late fee would apply for all the GSTR-3B returns furnished between 01.07.2020 to 30.09.2020
b) Further relief for small taxpayers for late filing of returns for February, March & April 2020 Tax periods:
For small taxpayers (aggregate turnover upto Rs. 5 crore), for the supplies effected in the month of February, March and April, 2020, the rate of interest for late furnishing of return for the said months beyond specified dates (staggered upto 6th July 2020) is reduced from 18% per annum to 9% per annum till 30.09.2020. In other words, for these months, small taxpayers will not be charged any interest till the notified dates for relief (staggered upto 6th July 2020)and thereafter 9% interest will be charged till 30.09.2020.
c) Relief for small taxpayers for subsequent tax periods (May, June & July 2020):
In wake of COVID-19 pandemic, for taxpayers having aggregate turnover upto Rs. 5 crore, further relief provided by waiver of late fees and interest if the returns in FORM GSTR-3B for the supplies effected in the months of May, June and July, 2020 are furnished by September, 2020 (staggered dates to be notified).
d) One time extension in period for seeking revocation of cancellation of registration:
To facilitate taxpayers who could not get their cancelled GST registrations restored in time, an opportunity is being provided for filing of application for revocation of cancellation of registration up to 30.09.2020, in all cases where registrations have been cancelled till 12.06.2020.
Certain clauses of the Finance Act, 2020 amending CGST Act 2017 and IGST Act, 2017 to be brought into force from 30.06.2020.
Note: The recommendations of the GST Council have been presented in this release in simple language for information of all stakeholders. The same would be given effect through relevant Circulars/ Notifications which alone shall have the force of law.
Council to meet again in July to specially discuss how the government can pay off states for the compensation cess dues, since the funds are falling short.
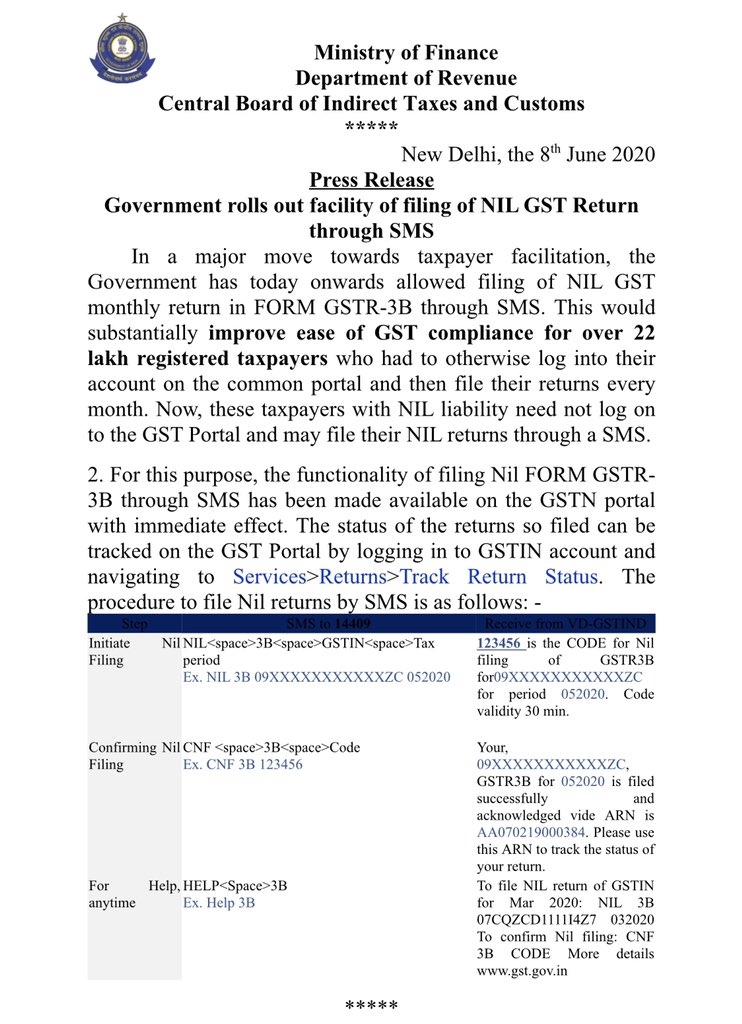
This would substantially improve ease of GST compliance for over 22 lakh registered taxpayers who had to otherwise log into their account on the common portal and then file their returns every month.
In a significant move towards taxpayer facilitation, the Government has today onwards allowed filing of NIL GST monthly return in FORM GSTR-3B through SMS.
This would substantially improve ease of GST compliance for over 22 lakh registered taxpayers who had to otherwise log into their account on the common portal and then file their returns every month.
Now, these taxpayers with NIL liability need not log on to the GST Portal and may file their NIL returns through an SMS.
For this purpose, the functionality of filing Nil FORM GSTR-3B through SMS has been made available on the GSTN portal with immediate effect.
The status of the returns so filed can be tracked on the GST Portal by logging in to GSTIN account and navigating to Services>Returns>Track Return Status.

 CBIC had extended, vide Press Note regarding extension of due date for furnishing of Annual Returns GSTR-9 and GSTR-9C for financial year 2019-20 to March 31, 2021.