Government sends tax notices to cryptocurrency investors as trading hits $3.5 billion


– The government has issued repeated warnings against digital currency investments
– Tech-savvy young investors, real estate players and jewellers are among those invested in bitcoin and other virtual currencies

The government has sent tax notices to tens of thousands of people dealing in cryptocurrency after a nationwide survey showed more than $3.5 billion worth of transactions have been conducted over a 17-month period, the income tax department said.

Tech-savvy young investors, real estate players and jewellers are among those invested in bitcoin and other virtual currencies, tax officials told Reuters after gathering data from nine exchanges in Mumbai, Delhi, Bengaluru and Pune.

Governments around the world are grappling with how to regulate cryptocurrency trading, and policymakers are expected to discuss the matter at a G20 summit in Argentina in March.

The government has issued repeated warnings against digital currency investments, saying these were like “Ponzi schemes” that offer unusually high returns to early investors.

But it has not so far imposed curbs on an industry estimated to be adding 200,000 users in India every month.

B.R. Balakrishnan, a director general of investigations at the income tax department in the southern state of Karnataka, said notices were sent following the survey to assess the penetration and patterns of virtual currency trade.

“We cannot turn a blind eye. It would have been disastrous to wait until the final verdict was out on its legality,” he told Reuters.

The tax department has asked people dealing in bitcoin and other virtual currencies such as ethereum and ripple to pay tax on capital gains. They have also asked for details about their total holdings and the source of funds in the tax notice seen by Reuters.

“We found that investors were not reflecting it on their tax returns and in many cases, the investment was not accounted for,” Balakrishnan said.

Bitcoin, the world’s biggest cryptocurrency, soared more than 1,700 percent last year, hitting a record high just shy of $20,000 as institutional and retail investors around the world snapped up the virtual currency.

Its huge gains have attracted the attention of global regulators tasked with protecting investors from fraud.

In recent weeks, Japan and China have made noises about a regulatory crackdown, while South Korean policymakers said they were considering shutting down domestic virtual currency exchanges.

REGULATION

An Indian finance ministry official said a federal committee was looking into the possibility of imposing restrictions on virtual currencies and that eventually parliament would have to legislate a regulatory regime.

Officials at Zebpay, India’s leading bitcoin exchange, said the industry was adding near 200,000 users every month with an estimated trade volume of about 20 billion Indian rupees ($315 million).

“Many of our customers are treating digital currency like gold,” said Zebpay co-founder Saurabh Agarwal.

Aman Kalra, marketing head of Coinsecure, a bitcoin exchange in New Delhi, said more than 150 bitcoins were changing hands every week through its platform. The company has 100,000 registered users and is now launching a platform to sell ethereum and other digital currencies.

“I don’t think anyone in the government should label our business as a ‘Ponzi scheme’, we are not doing anything illegal,” said Kalra.

Tax inspectors said they sought help from experts in blockchain, the technology that underpins bitcoin, to conduct the survey.

In some cases, tax officials themselves participated in the trade to identify loopholes after they found investors had poured in billions of dollars through unregulated exchanges.

Source: Times of India
PE investments jump 55% to all-time high of $24 bn across 591 deals in 2017

Flipkart received India’s largest ever PE investment of $2.5 billion in a single round from Softbank

Private equity firms invested $23.8 billion across 591 deals in 2017, making it the biggest year for PE investments in India, says a report.

According to deal tracker Venture Intelligence, the investment value is 39 per cent higher than the previous high of $17.1 billion (recorded in 2015) and 55 per cent higher than $15.4 billion invested during 2016. In terms of number of deals the year 2017 saw 21 per cent less activity as compared to 2016 (731 deals), indicating large number of big-ticket transactions.

“The year witnessed 31 investment deals with size greater than USD 200 million, aggregating to $15.4 billion or 65 per cent of the total investments,” the report said. These figures include venture capital investments, but exclude PE investments in real estate.

In terms of industries, IT/ ITeS companies accounted for 45 per cent of the value pie attracting $10.7 billion worth investments across 325 transactions.

Flipkart received India’s largest ever PE investment of $2.5 billion in a single round from Softbank and another $1.4 billion from strategic investors Tencent, eBay and Microsoft. Softbank also invested $1.4 billion in mobile wallet and payments firm One97 Communications, which owns the Paytm brand. BFSI (Banking, Financial Services and Insurance) companies continued to enjoy the second spot attracting $4.40 billion across 61 transactions.

The sector was led by Bain Capital’s $1.04 billion investment in Axis Bank — the largest ever single investment in the sector — and Warburg Pincus’ $384 million pre-IPO investment in ICICI Lombard General Insurance.

On the back of its two mega bets (Flipkart and Paytm), Softbank emerged as the largest investor during the year with investments totaling over $4 billion (including a $250 million investment in Oyo Rooms).

Other top investors include Canadian pension fund CPPIB with $2 billion investments across five companies; while Warburg Pincus invested $1.6 billion across nine companies, and KKR invested about $680 million.

China’s Tencent emerged as a significant strategic investor in the Indian Internet and mobile sector with investment of $1.1 billion across home grown leaders like Flipkart, Ola, Byjus Classes and Practo.


Source: Business Standard

M&M opens $230-m manufacturing facility in Detroit

Will roll out in early 2018 off-highway vehicle Roxor

Automotive major Mahindra & Mahindra broke fresh ground as an Indian multinational when it inaugurated its factory in the original Land of Automobile Manufacture, Detroit.

As Executive Chairman, Anand Mahindra, and the Lt. Governor of Michigan, Brian Calley, cut the ribbon to declare open the plant of Mahindra Automotive North America (MANA), they heralded the first investment in 25 years in a new OEM operation in Detroit.

That this is a major breakthrough for the city, which was badly hit by the financial and housing crisis, was evident from the official turnout at the inauguration. Two members of Congress, the Michigan Lt. Governor and a State Department official were all not only in attendance but also spoke evocatively about the investment.

M&M has invested $230 million and created 250 jobs in the plant, which will have a capacity to produce 10,000 units of Roxor, an off-highway vehicle.

MANA will invest another $600 million in the facility by 2020, adding a further 400 jobs.

The Roxor, designed and developed by MANA, was not unveiled but Richard P Haas, President and CEO, MANA, said that it would be launched in the market early 2018.

Speaking at the inauguration, Anand Mahindra struck a personal note on how he first came to the US in 1973 as a freshman student and how this was his way of giving back to the country for all that he had learnt as a student, which he said he had applied in his business.

Answering a question at a media interaction on whether the next step is to enter the US utility vehicles market Mahindra said that it is “not imminent, though it remains an aspiration”.

“Americans are familiar with Korean brands and the logical step is for Korean group company Ssangyong to come in with its models. But it is for the Ssangyong board to take the call,” he said.

Richard Haas added: “We’re watching how people react to the brand and are preparing for different scenarios. Over the next year or two we’ll learn, understand and move forward.”

Mahindra emphasised that MANA was not playing the volumes game saying that sometimes scarcity works better and that the days of requiring enormous scale to succeed are over.

He explained the rationale for the business as bringing together the engineering expertise of Detroit and a start-up culture.

“We’ve created an incubator here — Richard (Haas) has come with rich start-up experience from Tesla and the operation is based in Detroit to leverage conventional manufacturing skills. MANA will be an asset-light operation with a start-up mentality.”

Source: The Hindu Business Line

India jumps 30 places on World Bank’s ease of doing business index, breaks into top 100

The World Bank’s ease of doing business report showed that eight reforms were key in helping businesses in 2016/17. India is also among the 10 economies to have improved the most, alongside El Salvador, Malawi, Nigeria and Thailand.

Doing business in India became much easier over the past one year because of a raft of policy reforms, an annual World Bank index showed on Tuesday, in what is possibly a shot in the arm for Prime Minister Narendra Modi’s efforts to win big-ticket investments.

For the first time, India jumped 30 places to break into the top 100 in the ease of doing business rankings for the year to June 2017. The 190-country index is an influential barometer of competitiveness among countries that likely also helps businesses make investment decisions.

India’s impressive performance was largely due to reforms in taxation, insolvency laws and access to credit, part of measures Prime Minister Modi’s government has pushed to boost investment and jobs that would help absorb a million people who join the workforce every month.

“India’s performance is not based on efforts of just one year but consistent efforts made over the last three years to continuously improve the regulatory environment of doing business,” Annette Dixon, vice president South Asia, told a press conference.

“It is the result of a number of reforms that the government has undertaken that India is becoming a preferred destination to do business.”

India saw improvements in six of 10 indicators, including on winning construction permits, enforcing contracts, paying taxes and resolving insolvency. It, however, slipped when it came to starting a business, getting an electricity connection, cross-border trade and registering property.

Underlining how reforms had helped India improve its overall ranking, the World Bank said the establishment of debt recovery tribunals reduced non-performing loans by 28% and lowered interest rates on larger loans, suggesting that faster processing of debt recovery cases cut the cost of credit.

India was also among the 10 economies to have improved the most, alongside El Salvador, Malawi, Nigeria and Thailand.

– Hindustan Times

India is world’s 40th most competitive economy: WEF

The Global Competitiveness Index (GCI) is prepared on the basis of country-level data covering 12 categories or pillars of competitiveness.

India has been ranked as the 40th most competitive economy — slipping one place from last year’s ranking — on the World Economic Forum’s global competitiveness index, which is topped by Switzerland.

On the list of 137 economies, Switzerland is followed by the US and Singapore in second and third places, respectively.

In the latest Global Competitiveness Report released today, India has slipped from the 39th position to 40th while neighbouring China is ranked at 27th.

“India stabilises this year after its big leap forward of the previous two years,” the report said, adding that the score has improved across most pillars of competitiveness. These include infrastructure (66th rank), higher education and training (75) and technological readiness (107), reflecting recent public investments in these areas, it added.

According to the report, India’s performance also improved in ICT (information and communications technologies) indicators, particularly Internet bandwidth per user, mobile phone and broadband subscriptions, and Internet access in schools.

However, the WEF said the private sector still considers corruption to be the most problematic factor for doing business in India.

“A big concern for India is the disconnect between its innovative strength (29) and its technological readiness (up 3 to 107): as long as this gap remains large, India will not be able to fully leverage its technological strengths across the wider economy,” it noted.

Among the BRICS, China and Russia (38) are placed above India.South Africa and Brazil are placed at 61st and 80th spots, respectively.

In South Asia, India has garnered the highest ranking, followed by Bhutan (85th rank), Sri Lanka (85), Nepal (88), Bangladesh (99) and Pakistan (115).

“Improving ICT infrastructure and use remain among the biggest challenges for the region: in the past decade, technological readiness stagnated the most in South Asia,” WEF said.

Other countries in the top 10 are the Netherlands (4th rank), Germany (5), Hong Kong SAR (6), Sweden (7), United Kingdom (8), Japan (9) and Finland (10).

The Global Competitiveness Index (GCI) is prepared on the basis of country-level data covering 12 categories or pillars of competitiveness.

Institutions, infrastructure, macroeconomic environment, health and primary education, higher education and training, goods market efficiency, labour market efficiency, financial market development, technological readiness, market size, business sophistication and innovation are the 12 pillars.

According to WEF’s Executive Opinion Survey 2017, corruption is the most problematic factor for doing business in India.

The second biggest bottleneck is ‘access to financing’, followed by ‘tax rates’, ‘inadequate supply of infrastructure’, ‘poor work ethics in national labour force’ and ‘inadequately educated work force’, among others.

The survey findings are mentioned in the report.

“Countries preparing for the Fourth Industrial Revolution and simultaneously strengthening their political, economic and social systems will be the winners in the competitive race of the future,” WEF founder and Executive Chairman Klaus Schwab said.

India growing pretty robustly: World Bank President Jim Kim

Jim Kim said Japan, Europe and the US along with India were growing and there was a levelling-out in developing countries.

India has been growing “pretty robustly”, World Bank President Jim Yong Kim has said as he predicted a strong global growth this year.

Speaking at the Bloomberg Global Business Forum meeting here on Wednesday, Kim also called for more cooperation among the multilateral system, private sector and the governments to take advantage of the current win-win situation.

“That dormant capital will earn a higher return, where developing countries will have access to much more capital for the infrastructure needs, even for investing in health and education, investing in resilience to climate change and other factors,” Kim said.

He said Japan, Europe and the US along with India were growing and there was a levelling-out in developing countries.

“A country like India is growing, has been growing pretty robustly. We think, Japan is growing. Europe is growing in a much more healthy way. The United States continues to grow. There is a levelling-out in developing countries,” he said, adding that the growth will be more robust this year.

In June, the World Bank predicted a 7.2 per cent growth rate for India this year against 6.8 per cent growth in 2016. India remains the fastest growing major economy in the world, the World Bank officials had said.

“It used to be that commodity importers were doing much better than commodity exporters. But that’s levelling out. So the growth is relatively more evenly distributed,” Kim said.

He said in terms of indebtedness, the bank was watching very carefully the debt-to-GDP ratios of every single country.

“In Africa, the debt-to-GDP ratios are still very manageable…We would not be moving toward providing more financing for countries if we thought there was a real problem with over indebtedness in the countries. Because we follow this very closely, along with the IMF,” he said.

“We think that there are tremendous opportunities for investment. But sometimes, purely based on perception, investors in sovereign wealth funds – I’ve heard them say, Africa is risky. Right, as if Africa was a single country.

Africa’s not a single country and the risk profiles from country to country have enormous differences,” he said.

Source: Economic Times


India, Japan Ink 15 Agreements Including Aviation, Trade and Science

The pact in the area of disaster risk management, entered into between the Ministry of Home Affairs and the Cabinet Office of the Government of Japan, aims to cooperate and collaborate in the field of disaster risk reduction, an official statement said

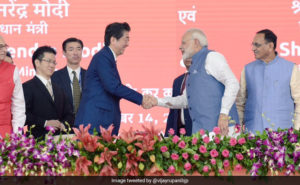
India and Japan on Wednesday signed 15 deals in key areas, including civil aviation, trade, science and technology, and skill development.

The pact in the area of disaster risk management, entered into between the Ministry of Home Affairs and the Cabinet Office of the Government of Japan, aims to cooperate and collaborate in the field of disaster risk reduction, an official statement said.

It said the understanding in the field of skill development looks to further strengthen bilateral relations and cooperation in the field of Japanese language education in India.

The one titled ‘India-Japan Investment Promotion Road Map’ envisages enhanced Japanese investments in India while the ‘Japan-India special programme for Make In India’ is on bilateral cooperation towards infrastructure development in the Mandal Bechraj-Khoraj region in Gujarat.

There was exchange of RoD (Record of Discussions) on civil aviation under which Indian and Japanese carriers can now mount unlimited number of flights to selected cities in both countries.

There was an agreement to establish a joint exchange programme to identify and foster talented young scientists from both countries to collaborate in the field of theoretical biology.

The MoU (Memorandum of Understanding) between the Department of Biotechnology and Japan’s National Institute of Advanced Science & Technology (AIST) seeks to promote research collaboration between these institutions in the field of life sciences and biotech, the statement said.

The India Japan Act East Forum, among the agreements signed, seeks to enhance connectivity and promote developmental projects in India’s North Eastern region in an efficient and effective manner, it said.

There were four agreements in the field of sports, including one to facilitate and deepen international education cooperation and exchanges between both Sports Authority of India and Nippon Sport Science University, Japan.

Source: NDTV