India ranks 130th in ease of doing business index

India continues to rank low at 130th position in terms of ease of doing business, with the country seeing little or no improvement in dealing with construction permits, getting credit and other parameters.

In the World Bank’s latest ‘Doing Business’ report, India’s place remained unchanged from last year’s original ranking of 130 among the 190 economies that were assessed on various parameters. However, the last year’s ranking has been now revised to 131 from which the country has improved its place by one spot.

The government has been making efforts to further improve the ease of doing business and aims to bring the country in the top 50.

Expressing disappointment over no change in India’s ranking in the World Bank’s index on ease of doing business, Indian government regretted that the report did not take into consideration 12 key reforms undertaken by the government.

When it comes to ‘distance to frontier’ — a measurement of the gap between an economy’s performance and the best practice score of 100 — India’s score has improved to 55.27 this year from 53.93 last year.

India is the only country for which the report has a box dedicated to its ongoing economic reforms.

The list of countries in the Doing Business 2017 is topped by New Zealand while Singapore is ranked second. It is followed by Denmark, Hong Kong, South Korea, Norway, the UK, the US, Sweden and former Yugoslav Republic of Macedonia.

Neighbouring Pakistan is ranked 144th in the list.

On the basis of reforms undertaken, the top 10 improvers are Brunei Darussalam, Kazakhstan, Kenya, Belarus, Indonesia, Serbia, Georgia, Pakistan, United Arab Emirates and Bahrain.

A record 137 economies around the world have adopted key reforms that make it easier to start and operate small and medium-sized businesses, the report said.

Developing countries carried out more than 75 per cent of the 283 reforms in the past year, with Sub-Saharan Africa accounting for over one-quarter of all reforms, it added.

“What we have seen is a remarkable effort on the part of the government to implement business reforms. It looks like we are going to have to wait for another year or so. But the direction of change is fundamentally a very significant one,” Global Indicators Group Director Augusto Lopez-Claros told PTI in an interview.

The rankings are based on ten parameters — starting a business, dealing with construction permits, getting electricity, registering property, getting credit, protecting minority investors, paying taxes, trading across borders, enforcing contracts and resolving insolvency.
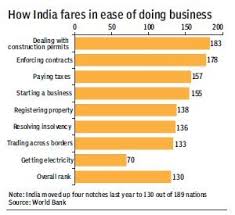
India has improved its ranking with respect to various areas. In terms of getting electricity, the country’s position has jumped to 26th spot from 51st place last year.

When it comes to trading across borders, the ranking has moved up one place to 143, and in enforcing contracts the rise is of six spots to 172nd position.

However, with respect to starting a business, the ranking has slipped four places to 155th spot and in the case of dealing with construction permits by one rank to 185th.

As per the report, India’s ranking in terms of protecting minority investors dropped to 13th place from 10th position last year.

With regard to getting credit, the ranking has fallen by two places to 44.

Explaining as to why India’s reform efforts is not being reflected in the ease of doing business report, Lopez-Claros said it very often takes some time for the reforms implemented by governments about the regulatory environment to be felt on the ground by the business community.

Rita Ramalho, Manager of the Doing Business project said that there were in fact improvements this year.

“There are four areas of improvement this year in India getting electricity, trading across border, enforcing contracts and paying taxes,” Ramalho told PTI.

India’s ranking is based on the study of the system in the two cities of Mumbai and New Delhi.

“The reason why there is no real movement in the ranking is more to do with the fact that other countries are also moving. In absolute terms India, does improve significantly.

There aren’t many countries that improved more than India in terms of absolute number,” Ramalho said.

The ‘Doing Business’ project provides objective measures of business regulations for local firms in economies and selected cities at the sub-national level.

The World Bank is emphasising that countries pay attention to what it calls “distance to frontier” which is an absolute metric, Lopez-Claros said.

“There has been actually substantial increase in the last 12 months in India by couple of percentage points, which is quite large,” he noted.
Source: http://www.businesstoday.in/current/economy-politics/india-ranks-130th-in-ease-of-doing-business-index/story/238944.html

Forex reserves hit fresh all-time high, cross $371 billion

The country’s forex reserves continued to scale new highs, with the week to September 9 adding $3.513 billion to the kitty, which hit a new life-time peak of $371.279 billion, RBI data showed today.

The reserves had increased by $989.5 million to $367.76 billion in the previous reporting week.

The reserves are more than sufficient to cover nearly 13 months of exports.

The surge indicates that new RBI Governor Urjit Patel is continuing with his predecessor Raghuram Rajan’s policy of building up the forex reserves. The three-year tenure of Rajan saw the RBI adding a net of $92 billion to the kitty.

Foreign currency assets (FCAs), a major component of the overall reserves, swelled by $3.509 billion to $345.747 billion for the week ended September 9, the Reserve Bank said.

FCAs, expressed in dollar terms, include the effect of appreciation/depreciation of non-US currencies such as the euro, pound and the yen held in the reserves.

Gold reserves, however, were unchanged at $21.64 billion at the end of the reporting week, the apex bank said.

The country’s special drawing rights with the International Monetary Fund increased by $5.3 million to $1.493 billion, while the reserve position with the fund was down by $1.3 million to $2.395 billion, it added.

Source: http://www.financialexpress.com/economy/forex-reserves-hit-fresh-all-time-high-cross-371-billion/379908/

FPIs infuses $1 billion in capital markets in September

Foreign investors have pumped in nearly Rs 6,800 crore (USD 1 billion) into the country’s capital markets so far this month, driven by global and domestic factors.

The latest infusion comes on top of a whopping inflow of Rs 25,904 in the preceding two months (July-August). Prior to that, foreign portfolio investors (FPIs) had pulled out a total of Rs 4,373 crore from the capital markets (equity and debt) in June and July.

Experts attributed the latest flurry in inflow to factors including good and widespread monsoon, better corporate earnings, sound progress on rollout progress of the Goods and Services Tax (GST) and positive data coming from the US economy.

Sentiments also rode high after domestic passenger vehicle sales grew for the 14th straight month in August, they added.

According to depositors’ data, net investment by FPIs stood at Rs 3,178 crore in equities during September 1-9, while the same for debt markets was at Rs 3,617 crore, taking the total inflow to Rs 6,795 crore (USD 1.02 billion).

So far this year, FPIs have invested Rs 44,028 crore in equities while withdrawing Rs 3,730 crore from the debt market. This resulted in a net flow of Rs 40,297 crore.

Source: http://www.financialexpress.com/economy/fpis-infuses-1-billion-in-capital-markets-in-september/373416/

Young entrepreneurs to get more funding from govt

To support young entrepreneurs, the central government will launch ‘special funds’ for those in the 16-21 years and 21-26 years age groups.

“It’s on the drawing board. We have accumulated funds worth Rs 9,000 crore under the technology cess category, and we want to use this. We might launch incubation centres, innovation hubs and even funds. This country requires investments of Rs 10,000 crore annually if we want to give boost to entrepreneurship,” said Y S Chowdary, ministry of state for science & technology and earth sciences.

He was speaking on the sidelines of the 11th edition of Indian Science and Technology Entrepreneurs Park & Business Incubators Association (Isba) here on Saturday.

The fund will be over and above the Rs 10,000 crore fund-of-funds for start-ups announced by the government early this year.

Over the past two years, the funding to several government departments supporting incubation in India has seen a spurt. H K Mittal, advisor, Department of Science and Technology (DST), said that the support for incubators has gone up 10 times.

“DST’s finance has gone up by at least 4.5x to Rs 180 crore for FY17. Several of our programmes like ‘Power of Idea’, Eureka and Entrepreneur-in-residence have seen their fund corpus going up. Our seed support programme has gone up five times. We can now fund start-ups starting from Rs 50 lakh to Rs 1 crore,” he added.

According to Kshatrapati Shivaji, chairman and managing director of Sidbi, the idea behind creating the fund-of-funds was to give a push to domestic venture capitalists (VCs). “We have already committed Rs 800 crore across 19 VCs, which, in turn, will mobilise the investments.”

The event also saw the signing of the first Indo-US Joint Early Stage Fund with a corpus of $40 million. About 50 per cent contribution for the fund comes from incubators that come under Isba and India Electronics & Semiconductor Association and the rest of the funds will have contribution from high net worth individuals based out of the US and serial entrepreneurs such as Sanjay Sharma, CEO of Roambee Corporation. At present, Isba supports around 100 incubators across India.

NURTURING YOUNG MINDS

  • The Centre to launch ‘special funds’ for those in the 16-21 years and 21-26 years age groups
  • The govt has accumulated funds worth Rs 9,000 crore under the technology cess category, said Y S Chowdary, ministry of state for science & technology and earth sciences
  • Over the past two years, the funding to several government departments supporting incubation in India has seen a spurt
  • Government’s seed support programme has gone up five times. The Centre plans to fund start-ups starting from Rs 50 lakh to Rs 1 crore
  • The 11th edition of Isba (Indian Science and Technology Entrepreneurs Park & Business Incubators Association) also saw signing of first Indo-US Joint Early Stage Fund with a corpus of $40 million

Source: http://www.business-standard.com/article/companies/young-entrepreneurs-to-get-more-funding-from-govt-116091200303_1.html

Kaya acquires “beneficial interest” in 2 UAE skincare firms

Skincare firm Kaya Ltd today said it has acquired majority “beneficial interest” in UAE’s Minal Medical Centre and Minal Specialized Clinic Dermatology for an undisclosed sum.

“Kaya Middle East, DMCC, a foreign subsidiary of Kaya Ltd has entered into an agreement dated September 8, 2016 for acquiring 75 per cent beneficial interest in Minal Medical Centre, Dubai and Minal Specialized Clinic Dermatology, Sharjah.

“However, the agreement will become effective on fulfilling of certain conditions precedent and obtaining the requisite statutory approval/s, which will take approximately 4 months,” the company said in a BSE filing.

It further said: “The above said entities carry out business of skincare, body and hair services and reported revenue of Arab Emirate Dirham (AED) 11.17 million (around Rs 20.26 crore), as per the audited financial statements for the year ended December 31, 2015.”

Kaya Ltd said: “This acquisition will further strengthen company’s network of clinics in the UAE region and add new set of customers to our existing base in the region. With its special expertise in body contouring, it would help Kaya in leveraging across the region.”

With this acquisition, the total network of Kaya’s clinics in the Middle East region would increase to 23.

Source: http://www.financialexpress.com/companies/kaya-acquires-beneficial-interest-in-2-uae-skincare-firms/372083/

GST bringing realty shake-up

Retailers, both of physical stores and e-commerce entities, fast moving consumer goods (FMCG) companies and those in consumer durables have started rejigging their warehouse strategy.

This is in preparation for the national goods and services tax (GST), with the government working to an April 2017 deadline. All this could mean a shake-up in real estate, say analysts. A rough calculation suggests these businesses could look at reducing their warehouse count to half, while stepping up the total space acquisition in select destinations, once GST comes into play. In the next two to three years, businesses could see significant cost reduction due to the revised strategy.

Hindustan Unilever, Nestle, Johnson & Johnson and Shoppers Stop are among those to have begun work on consolidating their warehouses, according to a source. These companies will take up mega space, in millions of square feet, to set up ‘mother warehouses’, he said. In the online space, top companies such as Flipkart and Amazon have been on an expansion spree for warehouses and fulfillment centres in the past two years, primarily to suit the complex tax structure through the country. Now, however, they won’t feel the need to have warehouses in every state and can strategise accordingly, Vijaya Ganesh Thangavel, managing director, Land & Industrial (India), Cushman & Wakefield, told this newspaper.

For instance, Max Fashion, a prominent retailer, has eight warehouses totaling 400,000 sq ft. The number is likely to come down to four after GST, says chief executive Vasanth Kumar. “The number will get firmed up once we know the full GST details and the implications such as the reverse logistics needs,’’ he said. Post GST, their warehouse count will be down but the total space covered could go up to around 600,000 sq ft by 2018 “to meet future business needs, as well our rate of growth at a 30-plus per cent CAGR (compounded annual rate)”.

If a typical e-commerce company was taking 300,000 to 400,000 sq ft in metros and tier-1 cities for warehouses, 100,000 sq ft in tier-2 and 40,000 to 50,000 sq ft in tier-3, the plan now will be to go for million sq ft space and more, away from big cities and in fewer locations, primarily where real estate cost won’t be prohibitive, says Thangavel of Cushman. Distribution centres, smaller in size in the range of 40,000 to 50,000 sq ft, could be set up closer to cities.

The biggest trend now is that prominent developers are getting into the warehouse space, which has mostly been a domain of local land owners till recently, according to Thangavel. Along with realtors, a new breed of advisors are coming up, only for warehouse planning. Also, warehouse parks are being set up for large structures. While the exercise of restructuring the warehouses will take a couple of years, he projects a cost reduction of at least 10 to 15 per cent by 2019-2020. Estimates are that big companies which have on an average one warehouse in every state, totaling to anything from 20 to 25, might look at eight to 10, pan-India post-GST.

“We understand that a few of the larger companies have started consolidating their warehousing requirements in strategic locations, in anticipation of GST, with a view to bringing efficiency into their supply chain,’’ said Rami Kaushal, managing director, Consulting and Valuations, CBRE South Asia.

Besides retailers and FMCG companies, even pharmaceutical companies would look at rationalising the number of operational warehouses and swap these for better quality and larger format ones, he said.

“Implementation of GST is expected to lead to rationalisation of warehousing demand, leading to lower logistics cost and reduced delivery time of manufactured goods,’’ Kaushal explained. The current complicated tax structure meant that choice in setting up inventory and distribution centres were based on the tax regime, rather than on operational efficiency, he said.

GST, when implemented, will free the decisions on warehousing and distribution from these tax considerations, according to Kaushal. ”This would enable occupiers to create larger hubs, servicing two or more states from a single location, which would help optimise inventory costs and increase efficiency.’’ This shift in operational planning would ultimately result in a hub and spoke model being adopted by many of the occupiers, he added.

Industrial warehousing space is estimated at approximately 800 million sq ft across the country and is expected to grow by nine to 10 per cent annually. A few sectors such as e-commerce, modern retailing and FMCG are expected to grow at about 20 per cent annually in the short term, according to CBRE.

A recent JLL report listed the National Capital Region, Mumbai, Pune, Bengaluru, Chennai, Hyderabad, Kolkata and Ahmedabad as top warehouse hubs. These eight city hubs together had a cumulative supply of organised Grade-A and Grade-B warehousing space of around 97 mn sq ft in 2015; this is expected to grow to around 116 mn sq ft by the end of 2016. It added that GST will result in emergence of new hubs such as Belgaum, Bhubaneswar, Coimbatore, Goa, Guwahati, Indore, Jaipur, Kolhapur, Lucknow/ Kanpur, Ludhiana, Nagpur, Patna, Raipur, Ranchi, Vapi and Vijayawada.


Source: http://www.business-standard.com/article/companies/gst-bringing-realty-shake-up-116090801173_1.html

British Columbia first foreign govt to issue masala bond

Canada’s Province of British Columbia has become the first foreign government entity to issue a masala bond by floating Rs 500 crore rupee denominated overseas bonds on the London Stock Exchange.

The bond raised $75 million (about Rs 500 crore) with 6.62 per cent semi-annual yield, securing high-quality investor support from across Europe, Asia and America. It is a AAA rated bond by the three major rating agencies and will mature on January 9, 2020, The Province of British Columbia said in a statement on Friday.

Masala Bonds are rupee-denominated bonds issued to overseas buyers, aimed at investments into India’s infra needs.

The proceeds of the bond were immediately reinvested in HDFC’s second masala bond listing on the exchange.

India’s mortgage lender Housing Development Finance Corporation (HDFC) had on Friday said The Province of British Columbia has subscribed the entire of its second tranche of Rs 500 crore rupee denominated overseas bonds.

“This transaction is a landmark deal as it opens up a new market for sovereign issuers and investors,” HDFC Ltd Chairman Deepak Parekh said in a statement on Friday.

“The pioneering simultaneous transactions on the LSE confirm RBI Governor Rajan’s recent statement that Masala bond issuances reflect ‘a coming of age of Indian debt’,” said Nikhil Rathi, CEO of London Stock Exchange.

The latest issuances bring the total number of masala bonds listed on the LSE to 33, raising the equivalent to about $3.86 billion for Indian infrastructure.

British Columbia Minister of Finance Michael de Jong said: “The international reputation and platform provided by the LSE sets the stage for more Masala bond issuances from around the world and will be most welcome for sustaining the Masala bond market’s success.”

HDFC Ltd, one of India’s leading banking and financial services companies, had listed the world’s first masala bond by an Indian corporate in July.

Source: http://www.business-standard.com/article/markets/british-columbia-first-foreign-govt-to-issue-masala-bond-116090200652_1.html