High margins and volumes are two reasons why banks are exploring the market in thrift credit
From being passive lenders to microfinance institutions (MFIs) till about five years earlier, banks have turned out to be active players in the business of small loans.
As on end-December 2016, banks accounted for 37 per cent (Rs 36,683 crore) of microfinance portfolio of Rs 98,625 crore; five years earlier, a handful of MFIs accounted for more than half.
High margins and volumes are two reasons why banks are exploring the market in thrift credit.
Most of them in MFI lending are private sector ones. A majority of this portfolio is with 11 banks — Axis, Bandhan, DCB, Equitas, HDFC, ICICI, IDFC, Kotak Mahindra, RBL and YES.
This apart, several public sector banks have increased their MFI exposure, through business correspondents (BCs).
“We see a lot of synergies with the microfinance sector. More, it is quite well-regulated and growing at a fast rate, providing a lot of business opportunities,” said an official in charge of a bank’s microfinance operations.
Also, over the past 18 months, banks have also been aggressive in taking equity stakes in MFIs. Last year, Kotak Mahindra Bank acquired Bengaluru-based BSS Microfinance.
RBL acquired 10 per cent in Utkarsh Micro Finance, which recently graduated into a small finance bank (SFB).
In July last year, IDFC Bank acquired Trichy-based Grama Vidiyal Microfinance, its second deal in the MFI space. Earlier, IDFC had taken 10 per cent in east-based ASA International India Microfinance.
In March last year, DCB Bank had acquired a 5.81 per cent stake in Odisha-based Annapurna Microfinance. Earlier, RBL had acquired 30 per cent in Swadhaar FinServe, a company acting as a BC.
Non-banking financial companies (NBFCs) have also shown interest. In 2015, Manappuram Finance had acquired Asirvad Micro Finance, a Chennai-based NBFC-MFI.
With a number of MFIs graduating to SFBs, the number in the MFI space is likely to further increase. And, even after graduating into a bank, they are likely to keep much of their lending to microfinance. Bandhan Bank, earlier an MFI, has even after close to two years into operation as a bank still got over 80 per cent of its lending portfolio concentrated in microfinance.
“Over the past three years, banks have shown a high level of interest in microfinance, part of a diversification strategy. Also, at least for two to three years, the new SFBs are likely to focus on microfinance as they build their deposit base,” says Ratna Vishwanathan, chief executive officer, Microfinance Institutions Network.
Seven of the proposed SFBs, some of which have transformed to a bank, together account for 46 per cent of the MFI portfolio, amounting to Rs 26,228 crore.
After years of subdued growth, the Indian microfinance (MFI) industry expanded more than 60% to Rs54,329 crore in 2015-16 compared to the previous year, according to a report prepared by Sa-Dhan, the self regulatory organisation of MFIs.
The MFI client base expanded by 2.8 million in the year, taking the total number of clients to 39.9 million, said the report. This growth was despite the fact that Bandhan, which was the largest MFI, moved out of the space to become a full fledged bank.
The top 10 MFIs classified as non-banking financial companies (NBFCs) accounted for about 80% of the total gross loan value, the report said. They include Janalakshmi Financial Services Ltd, Ujjivan Financial Services Ltd and SKS Microfinance Ltd.
“Attaining over 28 lakh clients is no mean feat. This goes on to show that the microfinance industry, having reached its inflection point, is growing steadfastly,” P. Sathish, executive director of Sa-Dhan, said.
The MFI sector experienced a crisis after Andhra Pradesh, the biggest market for small loans made to the unbanked poor and self-employed, in 2010 clamped down on micro lenders.
The state government tightened regulations governing MFIs after reports surfaced that coercive loan recovery practices by the lenders had driven some overextended borrowers to commit suicide. That led to a shrinking of the asset base of the microfinance industry and a surge in bad loans.
Of the total client base of 39.9 million, the southern region alone contributed to 39% of the total client base. Kerala and Karnataka now have the maximum number of MFI branches.
The growth in this sector is also due to Reserve Bank of India allowing many NBFC-MFIs to act as banking correspondents (BCS) connecting commercial banks with customers in small towns and rural areas.
“The MFIs are finding the BC model rather attractive on the credit side,” Sathish added.
The report also claims that 94% of the total loans taken from MFIs are for income generating activities, dominated by agriculture and animal husbandry.
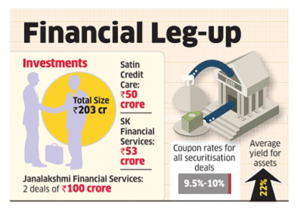
Micro Units Development & Refinance Agency (MUDRA) has recently closed its fourth deal with a total book of over Rs 203 crore, five months after it stepped into the securitisation market.
It has invested Rs 100 crore in two securitisation deals with Janalakshmi Financial Services and another Rs 50 crore in Satin Credit Care. It has also invested Rs 53 crore in SK Financial Services, a Jaipur-headquartered NBFC through a securitisation deal.
“We are directly investing in pass through certificates either as junior or senior investor,” Jiji Mammen, CEO, MUDRA, said.”All our investments are in healthy loan portfolios that will fetch us good yields.”
The coupon rates for all the securitisation deals are between 9.5 per cent and 10 per cent and the average yield for all assets was around 22 per cent, according to Mammen. Securitisation allows companies to provide part of their loan books and its receivables as guarantee to financial institutions. MUDRA was established as a subsidiary of Small Industries Development Bank of India (Sidbi) by PM Narendra Modi in April this year. The agency was set up with an initial corpus of Rs 5,000 crore to provide capital to all banks seeking refinancing of small business loans under Pradhan Mantri Mudra Yojna.
MUDRA’s latest attempt is to provide support to NBFCs and MFIs so that they in turn finance micro enterprises by participating in securitisation of their loan assets. It provides second loss default guarantee for credit enhancement and participates in investment of Pass through Certificate as senior or junior investor.
In the past five months, MUDRA has disbursed Rs 42,000 crore, one fourth of its total annual target of Rs 1,80,000 crore. The lending agency’s disbursals nearly doubled in the past two months to about Rs 27,000 crore from the Rs 15,000 crore it disbursed in the first quarter of the current fiscal year.
MUDRA has given loans of over Rs 1.3 lakh crore to 35 million borrowers. About 35 per cent of the total loans sanctioned last year were disbursed by MFIs. Among 45 per cent of the total loans disbursed by PSUs, 20 per cent was disbursed by SBI alone while 23 per cent was disbursed by private banks.
Of the planned disbursement of Rs 1.8 lakh crore this fiscal year, public sector banks would disburse Rs 77,700 crore, followed by Rs 21,000 crore by private and foreign banks, Rs 15,000 crore by regional rural banks, and Rs 64,240 crore by MFIs.
New EPF Act may oblige small firms with 10 or more staff to deduct PF from workers’ salary
Government plans to amend the Employees Provident Fund Act to bring more workers under the ambit of retirement fund body EPFO by reducing the threshold for coverage of firms to 10 workers, Lok Sabha was informed today.
Labour and Employment Minister Bandaru Dattatreya said the plan is to amend the law so that firms with ten employees can also be brought under the ambit of EPFO to ensure more workers come under the umbrella of social security.
At present, it is mandatory under the Employees’ Provident Fund and Miscellaneous Provisions Act for firms having 20 or more workers to subscribe to social security schemes run by the Employees’ Provident Fund Organisation.
In his written reply, he said no proposal is under the consideration of the government to allow EPFO subscribers to contribute voluntarily towards pension scheme in addition to their employers’ mandatory contribution.
He said effort is on to bring more unorganised workers under the ambit of various social security schemes for which more projects are being unveiled. “There is more focus on these workers,” he said.
Responding to the ‘plight’ of beedi workers following the introduction of 85 per cent pictorial norm on tobacco products, Dattatreya said the Labour Ministry is working to impart vocational skills to beedi workers.
He said several representations were received regarding “adverse consequences” of the Health Ministry’s notification prescribing 85 per cent pictorial warning on tobacco products.
He said at a meeting chaired by him in April, concerns were raised by stakeholders. The report of the meeting was conveyed to the Health Ministry.
He said beedi workers are covered under group insurance scheme and provided assistance of Rs 10,000 in case of natural death and Rs 25,000 in case of accidental death. Rs 1500 is also provided for the funeral of deceased workers.
Financial assistance of Rs 5000 is given to widows or widowers of beedi workers under social security schemes for wedding of their first two daughters.
Government has disbursed Rs 1,433 crore up to March under the interest subsidy scheme to exporters, the Commerce Ministry today said.
The Centre’s interest equalisation scheme, announced last December, reduces cost of capital by allowing 3 per cent interest subsidy on pre and post-shipment rupee export credit to eligible exporters.
“Indian exporters pay high rate of interest on the capital borrowed… all products manufactured and exported by SMEs (are) eligible. Up to March 2016, benefit to the tune of Rs 1,432.90 crore has been passed on to eligible borrowers,” the ministry said in a statement.
Enlisting steps to improve ease of doing business and boost exports, it said the ministry has taken several steps.
Number of mandatory documents required for exports and imports have been reduced to three for each segment. Earlier 7 documents were required for exports and 10 for imports.
“Exporter can now file online applications for IEC (import export code), Advance License, MEIS (merchandise exports from India scheme), SEIS (services exports from India scheme), pay application fee online and check status of their applications,” it said.
To spread awareness about benefits of free trade agreements, it said an ambitious outreach programme has been launched to reach out to exporters located in the 34 major export clusters/cities.
“The programmes focus on training exporters to utilise the FTAs, taking inputs from exporters on FTAs under negotiations for example Regional comprehensive economic policy (RCEP),” it added.
It said the efficacy of these initiatives is reflected in the fact the annual trade data indicates the share of manufacturing sector in India’s total exports has increased from 64 per cent in 2014-15 to more than 69 per cent in 2015-16.
In terms of trading across borders, India is ranked at 133rd out of 189 economies, according to the World Bank’s report on ease of doing business.
Small businesses with a total turnover of up to Rs 2 crore will not be required to get their accounts audited if they opt for presumptive taxation scheme, the finance ministry said on Monday.
“The higher threshold (up to Rs 2 crore) for non-audit of accounts has been given only to assessees opting for presumptive taxation scheme under section 44AD,” the ministry stated.
Section 44AB of the Income Tax Act makes it obligatory for every person carrying on business to get his accounts of any previous year audited if his total sales, turnover or gross receipts exceed Rs 1 crore.
“However, if an eligible person opts for presumptive taxation scheme as per section 44AD(1) of the Act, he shall not be required to get his accounts audited if the total turnover or gross receipts of the relevant previous year does not exceed Rs 2 crore,” the statement said.
Finance Minister Arun Jaitley in the 2016-17 Budget had proposed to increase the turnover limit under the presumptive taxation scheme under section 44AD of the Income Tax Act to Rs 2 crore “which will bring big relief to a large number of assesses in the MSME category”.
Jaitley had said if the taxpayer opts for the presumptive taxation scheme, he has to remain in that scheme for 5 years.
The entrepreneurship streak appears to be stronger in the small retail business space, going by the pattern of loans disbursed by the Micro Units Development and Refinance (MUDRA) Bank.
Small retailers, shopkeepers and those running micro units have utilised almost half of the loans disbursed under the MUDRA scheme launched by the Centre in April 2015.
As of May 20, the total loan disbursement was about Rs. 1.43 lakh crore and new entrepreneurs accounted for much of it.
MUDRA offers three categories of loans, Shishu (covering loans up to Rs. 50,000), Kishor (loans above Rs. 50,000 and up to Rs. 5 lakh) and Tarun (above Rs. 5 lakh and up to Rs. 10 lakh).
The objective of the scheme is to encourage new small businesses and ensure that at least 60 per cent of the credit flows to Shishu category units and the balance to the Kishor and Tarun categories. This has been realised as loans sanctioned/disbursed under the first category have so far have been higher than those under the other two categories.
According to a senior official at the State Bank of India, the demand for loans has been more from those taking up , among others, transport and community/personal service businesses.
In terms of States’ performance, Karnataka topped last year with Rs. 16,469 crore disbursements, followed by Tamil Nadu ( Rs. 15,496 crore) and Maharashtra ( Rs. 13,372 crore).
In disbursals, State Bank of India and its associate banks accounted for the biggest share of Rs. 16,999 crore. The disbursals by the 39 NBFC-Microfinance Institutions were also significant at Rs. 44,026 crore.
MUDRA loans are cheaper than those offered by other agencies, such as banks and MFIs. The cost of MUDRA funds, on an average, is 150-200 basis points lower than the benchmark repo rate.