Skip to Main Content
SunKrish Global Consulting & Corporate Services
  • About Us
  • Services
  • Our Team
  • Resources
  • Posts
    • Company Incorporations, MCA Returns
    • Accounting, Compliance, Auditing
    • ITRs – Individuals, Firms, Companies
    • Goods & Services Tax (GST)
    • Corporate & Business Advisory
  • Contact Us
  • About Us
  • Services
  • Our Team
  • Resources
  • Posts
    • Company Incorporations, MCA Returns
    • Accounting, Compliance, Auditing
    • ITRs – Individuals, Firms, Companies
    • Goods & Services Tax (GST)
    • Corporate & Business Advisory
  • Contact Us

Permanent Account Number (PAN)

1 Jul 2020

New TDS rates on high-value cash withdrawals apply from today.

by K.Sundar | posted in: Corporate & Business Advisory Services, Corporate Updates, Economy, Business Updates, Corporate Affairs, Income Tax,e-Filing- Individuals, Firms, Companies | 0
The levy is applicable only for large cash withdrawals. The intent is to minimize cash transactions and expand digital payments to enlarge the ambit of organized transactions over time.

In order to tighten the noose on those who don’t file income tax returns (ITR) despite earning taxable income and discourage cash transactions, the Finance Act 2020 introduced higher TDS (Tax Deducted at Source) rates on cash withdrawals for those who do not file ITR. The rates are applicable from 1 July.

Those who haven’t filed ITR for the past three financial years will have to pay TDS at the rate of 2%, if the amount withdrawn from the bank is above ₹20 lakh but doesn’t exceed ₹1 crore in a financial year. If the amount withdrawn exceeds ₹1 crore, TDS will be deducted at the rate of 5% under Section 194N of the Income-tax Act, 1961, for those who do not file ITR.

However, if you withdraw cash above ₹1 crore in a FY, you will still have to pay TDS whether you file ITR or not. In July 2019, the government, through Section 194N, had first introduced TDS at the rate of 2% on cash withdrawals above ₹1 crore in a financial year. This continues to be applicable.

“It is important to note that TDS shall be required to be deducted only when the aggregate amount of cash withdrawal during the FY by an individual from one or more of his bank accounts exceeds ₹20 lakh or ₹1 crore, as the case may be,” said Parizad Sirwalla, partner and head, global mobility services, tax, KPMG in India.

Further, tax will be deducted only on the amount exceeding the said thresholds. “If the individual withdraws a sum of money on regular intervals, the bank or financial institution will have to deduct TDS from the amount once the total sum withdrawn exceeds the threshold in a FY,” said Sirwalla.

For example, if person A has filed his ITR and if he withdraws cash up to ₹1 crore, then no TDS will be applicable. In case person A withdraws cash, which is more than ₹1 crore, then only 2% TDS will be applicable. If person A has withdrawn ₹1.25 crore in two transaction of ₹75 lakh in and ₹50 lakh, the TDS liability will only be on the excess amount that is ₹25 lakh.

On the other hand, if person B has not filed his ITR for the last three financial years and if he withdraws cash between ₹20 lakh and ₹1 crore, then 2% TDS will be applicable. In case person B withdraws cash which is more than ₹1 crore, then 5% TDS will be applicable.

“In case, the individual does not furnish the PAN to the bank or financial institution, then a TDS at a higher rate of 20% will become applicable,” said Sirwalla.

TDS will be applicable on withdrawals from banks, co-operative banks and post offices. The limit will apply on all accounts in the same bank. So, if you have multiple accounts with the same bank, then TDS will be applicable once you breach the mandatory limit across all the accounts or in any one of the account with the same bank. But for accounts with different banks, the limit will apply separately.

Banks will need to keep track of cash withdrawals and once the limit is breached, they will need to deduct TDS.

“Banks are asking declaration from people to ensure they have filed a return in the past three years or in any one of the last three years. This is done by banks for easier tracking as they wouldn’t know if the person has filed ITR or not,” said Sandeep Sehgal, director, taxes and regulatory, AKM Global.

The purpose of slapping this TDS is to minimize cash transactions and push digital payments.

“The levy is applicable only for large cash withdrawals in excess of ₹20 lakh/100 lakh per annum, as the case may be. The intent is to minimize cash transactions and expand digital payments to enlarge the ambit of organized transactions over time. So if individuals need to avoid this TDS levy, they should ensure that their cash withdrawals are restricted to the bare minimum and that the bulk of their payments happen through banking or digital means,” said Divakar Vijayasarathy, founder and managing partner, DVS Advisors LLP.
Digital India, Economy, Income Tax (IT), Income Tax Return (ITR), Permanent Account Number (PAN), Tax Deducted at Source (TDS), Taxation
25 Jun 2020

Government has further extended time limits for Income Tax return,TDS, Vivad Se vishwas Scheme etc

by K.Sundar | posted in: Corporate & Business Advisory Services, Corporate Updates, Economy, Business Updates, Corporate Affairs, Income Tax,e-Filing- Individuals, Firms, Companies | 0

The Government has also extended PAN-Aadhaar linking deadline.

In view of the challenges faced by taxpayers in meeting the statutory and regulatory compliance requirements across sectors due to the outbreak of Novel Corona Virus (COVID-19), the Government brought the Taxation and Other Laws (Relaxation of Certain Provisions) Ordinance, 2020 [the Ordinance] on 31st March, 2020 which, inter alia, extended various time limits.

In order to provide further relief to the taxpayers for making various compliances, the Government has issued a Notification on 24th June, 2020, the salient features of which are as under:

I. The time for filing of original as well as revised income-tax returns for the FY 2018-19 (AY 2019- 20) has been extended to 31st July, 2020.

II. Due date for income tax return for the FY 2019-20 (AY 2020-21) has been extended to 30th November, 2020. Hence, the returns of income which are required to be filed by 31st July, 2020 and 31st October, 2020 can be filed upto 30th November, 2020. Consequently, the date for furnishing tax audit report has also been extended to 31st October, 2020.

III. In order to provide relief to small and middle-class taxpayers, the date for payment of self-assessment tax in the case of a taxpayer whose self-assessment tax liability is upto Rs. 1 lakh has also been extended to 30th November, 2020. However, it is clarified that there will be no extension of date for the payment of self-assessment tax for the taxpayers having self-assessment tax liability exceeding Rs. 1 lakh. In this case, the whole of the self-assessment tax shall be payable by the due dates specified in the Income-tax Act, 1961 (IT Act) and delayed payment would attract interest under section 234A of the IT Act.

IV. The date for making various investment / payment for claiming deduction under Chapter-VIA-B of the IT Act which includes section 80C (LIC, PPF, NSC etc.), 80D (Mediclaim), 80G (Donations) etc. has also been further extended to 31st July, 2020. Hence the investment / payment can be made upto 31st July, 2020 for claiming the deduction under these sections for FY 2019-20.

V. The date for making investment / construction/ purchase for claiming roll over benefit / deduction in respect of capital gains under sections 54 to 54GB of the IT Act has also been further extended to 30th September, 2020. Therefore, the investment / construction/ purchase made up to 30th September, 2020 shall be eligible for claiming deduction from capital gains.

VI. The date for commencement of operation for the SEZ units for claiming deduction under section 10AA of the IT Act has also been further extended to 30th September, 2020 for the units which received necessary approval by 31st March, 2020. VII.

VII. The furnishing of the TDS/ TCS statements and issuance of TDS/ TCS certificates being the prerequisite for enabling the taxpayers to prepare their return of income for FY 2019-20, the date for furnishing of TDS/ TCS statements and issuance of TDS/ TCS certificates pertaining to the FY 2019-20 has been extended to 31st July, 2020 and 15th August, 2020 respectively.

VIII. The date for passing of order or issuance of notice by the authorities and various compliances under various Direct Taxes & Benami Law which are required to be passed/ issued/ made by 31st December, 2020 has been extended to 31st March, 2021. Consequently, the date for linking of Aadhaar with PAN would also be extended to 31st March, 2021.

IX. The reduced rate of interest of 9% for delayed payments of taxes, levies etc. specified in the Ordinance shall not be applicable for the payments made after 30th June, 2020. The Finance Minister has already announced extension of date for making payment without additional amount under the “Vivad Se Vishwas” Scheme to 31st December 2020, necessary legislative amendments for which shall be moved in due course of time. The said Notification has extended the date for the completion or compliance of the actions which are required to be completed under the Scheme by 30th December, 2020 to 31st December, 2020. Therefore, the date of furnishing of declaration, passing of order etc under the Scheme stand extended to 31st December, 2020

Deferment of the implementation of new procedure for approval/ registration/ notification of certain entities u/s 10(23C), 12AA, 35 and 80G of the IT Act has already been announced vide Press Release dated 8th May, 2020 from 1st June, 2020 to 1st October, 2020. It is clarified that the old procedure i.e. pre-amended procedure shall continue to apply during the period from 1st June, 2020 to 30th September, 2020. Necessary legislative amendments in this regard shall be moved in due course of time.

The Finance Minister has already announced reduced rate of TDS for specified non-salaried payments to residents and specified TCS rates by 25% for the period from 14th May, 2020 to 31st March, 2021. The announcement was also followed by the Press Release dated 13th May, 2020. The necessary legislative amendments in this regard shall be moved in due course of time

Press release on Extension and Ordinance

Aadhaar, Central Board of Direct Taxes (CBDT), COVID-19, Income Tax (IT), Income Tax Return (ITR), Permanent Account Number (PAN), Tax Deducted at Source (TDS)
10 May 2020

CBDT orders tax officials to not issue scrutiny notices to taxpayers

by K.Sundar | posted in: Corporate & Business Advisory Services, Corporate Updates, Economy, Business Updates, Corporate Affairs, Income Tax,e-Filing- Individuals, Firms, Companies | 0

Move comes after a group of IRS created panic and tax policy uncertainty.

After rejecting “ill-conceived” suggestions by a group of Indian Revenue Services (IRS) officers, the Central Board of Direct Taxes (CBDT) directed officials not to keep any communication with assessees or issue scrutiny notices to them without the board’s approval.

According to it, any such notice would have an “adverse effect” on the assessees amid the coronavirus (Covid-19) pandemic.

These directives are part of the interim action plan for the first quarter (April-June) prepared by the direct tax board. It highlights certain areas which need immediate attention and preparedness until normalcy returns.

The move comes at a time when the tax department faced widespread criticism on a report prepared by a group of IRS officers. It had created panic and tax policy uncertainty at a time when India is already going through a difficult economic situation.

“Identification and preparedness regarding the issuance of notice under Section 148, which deals with income escaping and return filing in all eligible cases, should be done by June 30. However, these notices are to be issued only after getting fresh communication from the board in this regard,” said the CBDT note.

It added that due to the unprecedented situation arising out of Covid-19-induced social distancing and lockdown this year, a relatively short interim action plan has been issued.

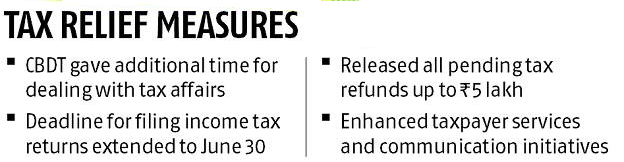
Considering the current situation, we have been putting a slew of tax relief measures to mitigate the impact on business and even on household.

Any such communication may put pressure on the taxpayers and create unnecessary panic. A new system had already been put in place to make officials accountable for their communication with assessees.

However, during the lockdown, even such communication would not go without the board consent, said a CBDT official. Other than keeping no communication with assessees, the tax officials have been asked to centralise cases where searches took place in the financial year 2019-202.

This is because once lockdown is lifted, the officials would work on disposing them on merit.

Moreover, the CBDT asked officials to be prepared for tax demands in cases of international taxation, tax deduction at source and exemption-related charges.

The board wants the department to examine all pending demands, according to permanent account number (PAN) and assessment years.

It also removed demands which are creating duplication and are lying in the system. Besides, officials were asked to reconcile brought-forward cases, especially on TDS, based on the information available on the Traces portal for TDS units. The interim action plan also instructed officials to dispose of all applications concerning granting registration to charitable trusts received upto March 31.

Meanwhile, the direct tax board told its officials to upload manual orders on the systems, especially those under Section 263. It deals with appeals where the principal commissioner or commissioner may call for and examine the record of any proceeding. He or she may consider an order passed by the assessing officer to be erroneous, if it is prejudicial to the interests of the revenue.

Central Board of Direct Taxes (CBDT), Corporate, COVID-19, Economy, Income Tax (IT), Income Tax Return (ITR), Permanent Account Number (PAN), Tax Deducted at Source (TDS), Taxation
24 Mar 2020

Nirmala Sitharaman: ITR / GST Return filing dates extended, relief from late fee, penalties

by K.Sundar | posted in: Company Incorporations, e-filing of MCA Returns, Corporate & Business Advisory Services, Corporate Updates, Economy, Business Updates, Corporate Affairs, Income Tax,e-Filing- Individuals, Firms, Companies | 0

The finance minister heads the Economic Task Force that was set up by the Prime Minister.

Finance minister Nirmala Sitharaman announced a slew of measures for extension of statutory and regulatory compliances in view of the corona virus pandemic spreading its wings and impacting the economy.

Allaying fears that there is no economic emergency in the country, FM said that the Economic Task Force will soon announce an economic relief package to deal with the impact of the corona virus pandemic on the economy.

These are largely in the area of ease of doing business, by providing reliefs in extension of due dates for compliances and reliefs from late fee and penalties, in view of the lock downs announced in several states and districts.

Income Tax

  1. The last date for filing income tax returns for Financial Year 2018-19, extended from 31st March, 2020 to 30th June, 2020.
  2. Aadhaar-PAN linking date extended from 31st March, 2020 to 30th June, 2020.
  3. Vivad se Vishwas scheme – no additional 10% amount, if payment made by June 30, 2020.
  4. Due dates for issue of notice, intimation, notification, approval order, sanction order, filing of appeal, furnishing of return, statements, applications, reports, any other documents and time limit for completion of proceedings by the authority and any compliance by the taxpayer including investment in saving instruments or investments for roll over benefit of capital gains under Income Tax Act, Wealth Tax Act, Prohibition of Benami Property Transaction Act, Black Money Act, STT law, CTT Law, Equalization Levy law, Vivad Se Vishwas law where the time limit is expiring between 20th March 2020 to 29th June 2020 extended to 30th June 2020.
  5. For delayed payments of advanced tax, self-assessment tax, regular tax, TDS, TCS, equalization levy, STT, CTT made between 20th March 2020 and 30th June 2020, reduced interest rate at 9% instead of 12 %/18 % per annum ( i.e. 0.75% per month instead of 1/1.5 percent per month) will be charged for this period. No late fee/penalty shall be charged for delay relating to this period.
  1. Necessary legal circulars and legislative amendments for giving effect to the aforesaid relief shall be issued in due course.

GST/Indirect Tax

  1. Last date for filing GSTR-3B in March, April and May 2020 extended till the last week of 30th June, 2020 for those having aggregate annual turnover less than Rs. 5 Crore. No interest, late fee, and penalty to be charged.
  2. For any delayed payment made between 20th March 2020 and 30th June 2020 reduced rate of interest @9 % per annum ( current interest rate is 18 % per annum) will be charged. No late fee and penalty to be charged, if complied before till 30th June 2020.
  3. Date for opting for composition scheme is extended till the last week of June, 2020. Further, the last date for making payments for the quarter ending 31st March, 2020 and filing of return for 2019-20 by the composition dealers will be extended till the last week of June, 2020.
  4. Date for filing GST annual returns of FY 18-19, which is due on 31st March, 2020 is extended till the last week of June 2020.
  5. Due date for issue of notice, notification, approval order, sanction order, filing of appeal, furnishing of return, statements, applications, reports, any other documents, time limit for any compliance under the GST laws where the time limit is expiring between 20th March 2020 to 29th June 2020 extended to 30th June 2020.
  1. Necessary legal circulars and legislative amendments to give effect to the aforesaid GST relief shall follow with the approval of GST Council.
  2. Payment date under Sabka Vishwas Scheme extended to 30th June, 2020. No interest for this period shall be charged if paid by 30th June, 2020.

Customs

  1. Custom clearance will operate 24X7 till June 30, 2020.
  2. Due date for issue of notice, notification, approval order, sanction order, filing of appeal, furnishing applications, reports, any other documents etc., time limit for any compliance under the Customs Act and other allied Laws where the time limit is expiring between 20th March 2020 to 29th June 2020 shall be extended to 30th June 2020.

Financial Services

Relaxations for 3 months

  • Debit cardholders to withdraw cash for free from any other banks’ ATM for 3 months
  • Waiver of minimum balance fee
  • Reduced bank charges for digital trade transactions for all trade finance consumers

Corporate Affairs

  1. No additional fees shall be charged for late filing during a moratorium period from 01st April to 30th September 2020, in respect of any document, return, statement etc., required to be filed in the MCA-21 Registry, irrespective of its due date, which will not only reduce the compliance burden, including financial burden of companies/ LLPs at large, but also enable long-standing non-compliant companies/ LLPs to make a ‘fresh start’;
  2. The mandatory requirement of holding meetings of the Board of the companies within prescribed interval provided in the Companies Act (120 days), 2013, shall be extended by a period of 60 days till next two quarters i.e., till 30th September;
  3. Applicability of Companies (Auditor’s Report) Order, 2020 shall be made applicable from the financial year 2020-2021 instead of from 2019-2020 notified earlier. This will significantly ease the burden on companies & their auditors for the year 2019-20.
  4. As per Schedule 4 to the Companies Act, 2013, Independent Directors are required to hold at least one meeting without the attendance of Non-independent directors and members of management. For the year 2019-20, if the IDs of a company have not been able to hold even one meeting, the same shall not be viewed as a violation.
  1. Requirement to create a Deposit reserve of 20% of deposits maturing during the financial year 2020-21 before 30th April 2020 shall be allowed to be complied with till 30th June 2020.
  2. Requirement to invest 15% of debentures maturing during a particular year in specified instruments before 30th April 2020, may be done so before 30th June 2020.
  3. Newly incorporated companies are required to submit commencement of Business certificate within 6 months of incorporation. This is now extended to 12 months.
  4. Non-compliance of minimum residency in India for a period of at least 182 days by at least one director of every company, under Section 149 of the Companies Act, shall not be treated as a violation.
  5. Due to the emerging financial distress faced by most companies on account of the large-scale economic distress caused by COVID 19, it has been decided to raise the threshold of default under section 4 of the IBC 2016 to Rs 1 crore (from the existing threshold of Rs 1 lakh). This will by and large prevent triggering of insolvency proceedings against MSMEs. If the current situation continues beyond 30th of April 2020, we may consider suspending section 7, 9 and 10 of the IBC 2016 for a period of 6 months so as to stop companies at large from being forced into insolvency proceedings in such force majeure causes of default.
  6. Detailed notifications/circulars in this regard shall be issued by the Ministry of Corporate Affairs separately.

Department of Commerce

  1. Extension of timelines for various compliance and procedures will be given. Detailed notifications will be issued by Ministry of Commerce.

Press Release – COVID 19

Aadhaar, Benami Property Transactions Act, Black Money, Central Board of Excise and Customs (CBEC), Companies Act 2013, Company Law, COVID-19, Ease of doing business, Economy, Goods and Services Tax (GST), Income Tax (IT), Income Tax Return (ITR), Insolvency and Bankruptcy Code (IBC), Ministry of Corporate Affairs (MCA), Nirmala Sitharaman, Permanent Account Number (PAN), Tax Deducted at Source (TDS)
18 Feb 2020

Key features of SPICe+ for Incorporation of New Companies in India

by K.Sundar | posted in: Company Incorporations, e-filing of MCA Returns, Corporate & Business Advisory Services, Corporate Updates, Economy, Business Updates, Corporate Affairs | 0
  • As part of Government of India’s Ease of Doing Business (EODB) initiatives, the Ministry of Corporate Affairs would be shortly notifying & deploying a new Web Form christened ‘SPICe+’ (pronounced ‘SPICe Plus’) replacing the existing SPICe form.
SPICe+ would save as many procedures, time and cost for Starting a Business in India and would be applicable for all new company incorporation w.e.f 15th February 2020

Key Features of Spice+

  1. SPICe+ would be an integrated Web Form i.e. fill form online like GST registration forms. The new web form would Facilitate on-screen filing and real time data validation for seamless incorporation of companies.
  1. Information once entered can be saved and modified. All Check form and Pre-scrutiny validations  will happen on web form itself.
  1. DSC validation and other validations will happen at Upload Level
  1. Once the SPICe+ is filled completely with all relevant details, the same would then have to be converted into pdf format, with just a click of the mouse button, for affixing DSCs.
  1. Digitally signed applications can then be uploaded along with the linked forms as per the existing process.
  1. Changes/modifications to SPICe+ (even after generating pdf and affixing DSCs), can also be done by editing the same web form
  1. Spice+ would have 2 parts:
  1. a)     Part A : for name reservation for new incorporation
  2. b)     Part B : Part B offering a bouquet of services i.e.
  • Incorporation
  • DIN allotment
  • Mandatory issue of PAN / TAN
  • Mandatory issue of EPFO / ESIC registration
  • Mandatory issue of Profession Tax registration (Maharashtra)
  • Mandatory Opening of Bank Account for the Company
  • Allotment of GSTIN (if so applied for)
  1. Part A can be filed first for reserving name or Part A & B can be filed together at one go.
  1. Re submission would be easy, if required.
  1. Registration for EPFO and ESIC shall be mandatory for all new companies incorporated w.e.f 15 February 2020 and no EPFO & ESIC registration nos. shall be separately issued by the respective agencies.
  1. Registration for Profession Tax shall also be mandatory for all new companies incorporated in the State of Maharashtra w.e.f 15th February 2020.
  1. All new companies incorporated through SPICe+ (w.e.f 15th February 2020) would also be mandatorily required to apply for opening the company’s Bank account through the AGILE-PRO linked web form.
  1. Declaration by all Subscribers and first Directors in INC-9 shall be auto-generated in pdf format and would have to be submitted only in Electronic form in all cases, except where:
  • Total number of subscribers and/or directors is greater than 20 and/or
  • Any such subscribers and/or directors has neither DIN nor PAN

Notification SPICE+ Form

Companies Act 2013, Company Incorporation, Company Law, Corporate, Ease of doing business, EPFO, Goods and Services Tax (GST), Ministry of Corporate Affairs (MCA), Permanent Account Number (PAN), SPICe
25 Oct 2019

Not received your tax refund? Here is what you should do

by K.Sundar | posted in: Corporate & Business Advisory Services, Corporate Updates, Income Tax,e-Filing- Individuals, Firms, Companies | 0

The bank accounts need to be pre-validated and linked to the taxpayers’ permanent account number (PAN) from this assessment year 2019-20.

Direct credit to bank accounts of taxpayers is the only way the income tax department credits tax refunds.

Filed your income tax return (ITR) for the assessment year (AY) 2019-20 on time but yet not receive your refund? Don’t worry. You may just have furnished incorrect bank details. Of course, there may be other reasons for the delay, though this is the most prominent.

Earlier, tax refund was issued either in the form of a cheque or directly credited to bank accounts. However, direct credit to bank accounts of taxpayers is the only one mode through which the income tax department credits tax refunds. These accounts need to be pre-validated and linked to the taxpayers’ permanent account number (PAN) from this assessment year.

Taxpayers are entitled to claim a tax refund if, during the year, excess tax has been deducted from your income. This may happen if there are multiple incomes. But, you have to apply for a refund while filing your ITR for a particular financial year.

Track the status

You can check the status of your refund. A few years ago, to find the status of a tax refund one had to approach the assessing officer. But now, you can do so in minutes. After filing returns, a taxpayer will need to wait utmost for a few months to receive the refund.

You can visit these websites to check their tax refund status: www.incometaxindia.gov.in or www.tin-nsdl.com. Go to the “Status of Tax Refunds” tab, give your PAN number and the assessment year for which you wish to track the status of refund. A message will pop up, stating the mode of payment, a reference number, status and the date of refund. Of course, these will happen only if the refund has been processed.

However, if there is any problem due to which tax refund not received, there would be a suitable message. For e.g., if the message is “refund unpaid,” it could be due to the incorrect bank account details (account number or IFS Code) you may have submitted to the income tax department. Verify the bank account details submitted earlier.

You need to provide information on all the savings and current accounts held at any time in India during the previous year, according to income tax rules. Details of accounts that have been inoperative for at least three years or more are not required.

The taxpayer is supposed to provide one bank account in which she/he wants the tax refund credited. You have to provide this detail even if there is no refund. Bank details include the name of the bank, account number, and the 11-digit IFS Code or details of the international bank account number (IBAN) in case you have a foreign bank account. Not providing any bank account details will result in refunds not getting credited.

E-Filing, Income Tax (IT), Income Tax Return (ITR), Permanent Account Number (PAN), Taxation
21 Oct 2019

What to do if you haven’t got tax refund yet

by K.Sundar | posted in: Corporate & Business Advisory Services, Corporate Updates, Economy, Business Updates, Corporate Affairs, Income Tax,e-Filing- Individuals, Firms, Companies | 0

Are you wondering why you have not received your income tax refund yet despite having filed your income tax return (ITR) within the due date for assessment year (AY) 2019-20? There could be various reasons for the same. However, a common reason could be furnishing incorrect bank account details in the ITR form.

While tax refund was earlier issued either in the form of cheque or direct credit to bank accounts, the income tax department now credits tax refunds only in the form of direct credit in the bank accounts of taxpayers. Moreover, from this AY, these accounts need to be pre-validated and linked to the taxpayers’ permanent account number (PAN).

You are eligible to claim a refund if excess income tax has been deducted from your income during the year. This could happen in cases of multiple incomes or where tax is deducted at source (TDS). The income tax department does refund this excess tax paid, but you have to apply for it when filing your ITR for the relevant financial year.

Track the status

In case you have not received your refund yet, you first need to check the status of your refund. “About five to six years ago, one had to approach the assessing officer to find out the status of refunds. Now one can check it online within minutes,” said Amit Maheshwari, partner, Ashok Maheshwary and Associates LLP, a chartered accountancy firm. Except in few cases, now most people get their refunds in a few months of filing returns, added Maheshwari.

You can track the status of your refund on www.incometaxindia.gov.in or www.tin-nsdl.com. Click on “Status of Tax Refunds” tab, enter your PAN and the AY for which you want to track the refund. If the refund has been processed, a message will pop up, stating the mode of payment, a reference number, status and date of refund.

However, if there is an issue because of which refund has not been issued or declined, the message will say so. For instance, if the message states “refund unpaid”, it could be because the bank account details (account number or IFS Code) that you have submitted to the income tax department are wrong. In that case, check your bank account details you have mentioned in your ITR.

Bank account information

According to income tax rules, you are supposed to provide details of all the savings and current accounts held by you at any time in India during the previous year, while filing your returns. It is not mandatory to provide details of dormant accounts which have not been operational for more than three years. However, “if the income from all the bank accounts has been duly included though the details of the account itself may have been omitted, no penalty may be leviable in such cases,” said Maheshwari.

If you have more than one bank account, you are required to indicate the account in which you would like to get your refund credited, irrespective of whether you have a refund or not. Bank details include the name of the bank, account number, and the 11-digit IFS Code of the bank or details of international bank account number (IBAN) in case you have a foreign bank account.

Taxpayers who filed returns for AY2019-20 were also required to ensure that the bank account chosen for the refund is pre-validated with the e-filing account and linked with their PAN.

Failure to provide any of the above mentioned details may result in the refund not getting credited.

Making correction

If you find you have made a mistake in providing your bank account details, you have the option to update it, before placing a request for re-issue of refunds.

Remember that you can update your bank account details only in case where your return has been processed and your refund was failed or not credited in your bank account because of an issue with your bank account details.

In such a case, you need to modify your account details and place a request for reissue of refund. It can be done online by logging into the e-filing portal, www.incometaxindiaefiling.gov.in, with your user ID and password. Next, go to “My Account” and then click on “Refund re-issue request”. Follow the steps and enter the new bank account number or make a correction in the already mentioned bank details and submit the request.

Before doing so, make sure this account is linked with your PAN and is pre-validated. In order to link your bank account with PAN, you need to visit your bank’s branch with a copy of PAN. It is a simple process and does not take much time. Once you link your bank account with PAN, pre-validate the bank account through the income tax e-filing account. Log on to e-filing accounts, go to “profile setting” and choose which bank you want to pre-validate. You will need to provide information like bank name, bank account number, IFS Code, mobile and email ID to validate your bank account.

Once you update the bank account and place a request for reissue of refunds, it will most likely get credited to your account in a few days.

E-Filing, Income Tax (IT), Income Tax Return (ITR), Permanent Account Number (PAN), Tax Deducted at Source (TDS), Taxation

Posts pagination

« 1 2 3 4 5 … 8 »

Recent Posts

  • MCA Extends Due Date for Filing AOC-4 and MGT-7 till 31 December 2026: Major Relief for Companies

    MCA Extends Due Date for Filing AOC-4 and MGT-7 till 31 December 2026: Major Relief for Companies

  • CBDT extends I-T return filing deadline for audit cases to November 21

    CBDT extends I-T return filing deadline for audit cases to November 21

  • Fixed Late Fee for Tax Audit Report (AY 2026-27): What is applicable

    Fixed Late Fee for Tax Audit Report (AY 2026-27): What is applicable

  • The Micro, Small and Medium Enterprises Development (Amendment) Bill, 2026 Passed by Parliament: A New Era for India’s MSME Sector

    The Micro, Small and Medium Enterprises Development (Amendment) Bill, 2026 Passed by Parliament: A New Era for India’s MSME Sector

  • CBDT to show foreign financial information in AIS &Form 26 AS

    CBDT to show foreign financial information in AIS &Form 26 AS

  • MCA introduces CCFC-2026 to ease compliance by Corporates

    MCA introduces CCFC-2026 to ease compliance by Corporates

  • The new Income Tax Act, 2025 replaces old Act of 1961

    The new Income Tax Act, 2025 replaces old Act of 1961

© 2026 SunKrish Globecons Private Limited