GST Council slashes Rate on Certain Services

GST Council in the 31-meeting held on 22 December, 2018 at New Delhi took following decisions relating to changes in GST rates on goods and services. The decisions of the GST Council have been presented in this note for easy understanding. The same would be given effect to through Gazette notifications/ circulars which shall have force of law.

GST rate reduction on goods which were attracting GST rate of 28%:

28% to 18%

Pulleys, transmission shafts and cranks, gear boxes etc., falling under HS Code 8483

Monitors and TVs of upto screen size of 32 inches

Re-treaded or used pneumatic tyres of rubber;

Power banks of lithium ion batteries. Lithium ion batteries are already at 18%. This will bring parity in

GST rate of power bank and lithium ion battery.

Digital cameras and video camera recorders

Video game consoles and other games and sports requisites falling under HS code 9504.

 28% to 5%

Parts and accessories for the carriages for disabled persons

GST rate reduction on other goods –

18% to 12%

Cork roughly squared or debagged

Articles of natural cork

Agglomerated cork

18% to 5%

Marble rubble

12% to 5%

Natural cork

Walking Stick

Fly ash Blocks

12% to Nil

Music Books

5% to Nil

Vegetables, (uncooked or cooked by steaming or boiling in water), frozen, branded and put in a unit container

Vegetable provisionally preserved (for example by sulphur dioxide gas, in brine, in sulphur water or in other preservative solutions), but unsuitable in that state for immediate consumption.

III. GST on solar power generating plant and other renewable energy plants

GST rate of 5% rate has been prescribed on renewable energy devices & parts for their manufacture (bio gas plant/solar power based devices, solar power generating system (SGPS) etc) [falling under chapter 84, 85 or 94 of the Tariff]. Other goods or services used in these plants attract applicable GST.

Certain disputes have arisen regarding GST rates where specified goods attracting 5% GST are supplied along with services of construction etc and other goods for solar power plant.

To resolve the dispute the Council has recommended that in all such cases, the 70% of the gross value shall be deemed as the value of supply of said goods attracting 5% rate and the remaining portion (30%) of the aggregate value of such EPC contract shall be deemed as the value of supply of taxable service attracting standard GST rate.

 Reduction in GST rates/exemptions on services:

GST rate on cinema tickets above Rs. 100 shall be reduced from 28% to 18% and on cinema tickets upto Rs. 100 from 18% to 12%.

GST rate on third party insurance premium of goods carrying vehicles shall be reduced from 18% to 12%

Services supplied by banks to Basic Saving Bank Deposit (BSBD) account holders under Pradhan Mantri Jan Dhan Yojana (PMJDY) shall be exempted.

Air travel of pilgrims by non-scheduled/charter operations, for religious pilgrimage facilitated by the Government of India under bilateral arrangements shall attract the same rate of GST as applicable to similar flights in Economy class (i.e. 5% with ITC of input services).

Source: GST Rate reductions made during 31st Meeting of the GST Council
GST Council extends Due Dates for Annual Returns and other GST Returns

GST Council grants mega relief to taxpayers – ITC for last FY invoices allowed upto March 31, 2019 + New GST Return to be launched on trial basis from April 1, 2019 + amendment in Sec 50 to allow payment of interest on net cash liability

The 31st GST Council meeting concluded today under the guidance of Union Minister Arun Jaitley has taken some important decisions including the due date extension for GST Annual Returns and some other Returns.

As per the recommendation of the Council, the due date for furnishing the annual returns in FORM GSTR-9, FORM GSTR-9A and reconciliation statement in FORM GSTR-9C for the Financial Year 2017 – 2018 shall be further extended till 30.06.2019.

Further, the due date for furnishing FORM GSTR-8 by e-commerce operators for the months of October, November and December 2018 shall be extended till 31.01.2019.

The due date for submitting FORM GST ITC-04 for the period July 2017 to December 2018 shall be extended till 31.03.2019. ITC in relation to invoices issued by the supplier during FY 2017-18 may be availed by the recipient till the due date for furnishing of FORM GSTR-3B for the month of March 2019, subject to specified conditions.

All the supporting documents/invoices in relation to a claim for refund in FORM GST RFD-01A shall be uploaded electronically on the common portal at the time of filing of the refund application itself, thereby obviating the need for a taxpayer to physically visit a tax office for submission of a refund application.

GSTN will enable this functionality on the common portal shortly. The due date for the taxpayers who did not file the complete FORM GST REG-26 but received only a Provisional ID (PID) till 31.12.2017 for furnishing the requisite details to the jurisdictional nodal officer shall be extended till 31.01.2019.

Also, the due date for furnishing FORM GSTR-3B and FORM GSTR-1 for the period July 2017 to February, 2019/quarters July 2017 to December 2018 by such taxpayers shall be extended till 31.03.2019

Late fee shall be completely waived for all taxpayers in case FORM GSTR-1, FORM GSTR-3B &FORM GSTR-4 for the months/quarters July, 2017 to September, 2018, are furnished after 22.12.2018 but on or before 31.03.2019.


Source: Recommendations-made-during-31st-Meeting-of-the-GST Council


Source:

GSTN enables facility to claim Refund of Tax due to any Other Reason

The facility to claim Refund on account of any other reason has now enabled in the Goods and Services Tax Network ( GSTN ).

In statement released today, the official twitter account of the GSTN tweeted that “Facility to claim Refund on account of any other reason has been enabled on GST Portal for the taxpayers.”

Last day, the GST portal had updated a new functionality enabling the taxpayers to claim refund on account of excess payment of tax.

“Facility to claim refund on account of excess payment of tax has been enabled on GST Portal for the taxpayers,” GSTN said in a statement. On Tuesday, the GSTN had updated two new features such as, the facility to upload statement 4 for Refund and the facility for amendment in Registration of Core fields.


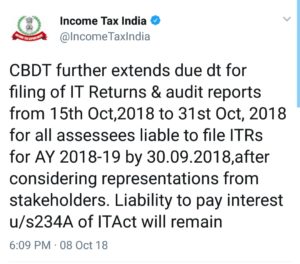
CBDT further extends due date for filing IT Returns & Tax Audit Reports up to 31 October.

The Central Board of Direct Taxes (CBDT) has further extended due date for filing Income Tax Returns and Audit Reports to October 31st.

The due date for filing of Income Tax Returns and Audit Reports for Assessment Year 2018-19 is 30th September, 2018 for certain categories of taxpayers.

The CBDT had earlier extended the date for filing of Income Tax Returns and various reports of Audit to 15th October 2018.

Upon consideration of representations from various stakeholders, CBDT further extends the ‘due date’ for filing of Income Tax Returns as well as reports of Audit (which were required to be filed by the said specified date) from 15th October, 2018 to 31st October, 2018 in respect of the said categories of taxpayers.

However, as specified in earlier order dated 24.09.2018, assessees filing their return of income within the extended due date shall be liable for levy of interest as per provisions of section 234A of the Income-tax Act, 1961.

As SEBI reforms startup listing, SMEs must ensure funds are not misused

SME ExchangeAmid SEBI banning as many as 239 entities for alleged money laundering, taxation consultancy PwC has called for a three-year locking-in for the entire pre-listing capital held by promoters to curb tax evasion and other illegal activities through market platforms.

The agency has called for imposing a similar lock-in even for preferential allotments, as prescribed under the capital and disclosure requirement (ICDR) norms so that only serious investors access the market. The PwC report is part of a BSE-mandated review of SME listing process.

The premier bourse last week said that 100 entities were trading on its SME platform. The regulator Securities and Exchange Board (SEBI) on June 29 banned four publicly traded SMEs and 235 other related entities for alledgely misusing the exchange’s platform for money laundering and tax evasion.

The SEBI, in an interim order alleged that these entities made Rs 614 crore in illegal gains through suspected money laundering and tax evasion activities. The four companies banned are EcoFriendly Food Processing Park, Esteem Bio Organic Food Processing, Channel Nine Entertainment and HPC Biosciences. These are traded on the BSE SME Platform.

“The institutional trading platform (ITP) could be utilised as a tool for tax planning by staying invested in an SME for a period more than 12 months and exiting at a very high stock price thereby making huge gains with no tax liability,” PwC said in the report.

Accordingly, the report has suggested that the entire pre-listing capital held by promoters should be locked in for three years as “such restrictive conditions would discourage people from accessing the platform only for tax planning”. The BSE had launched ITP for its SME platform to facilitate start-ups and other SMEs to list without the mandatory IPO process which is time-consuming and capital intensive that small companies can hardly afford.

According to PTI, in addition to allowing SMEs and start-up companies to raise capital, the BSE SME platrfom also provides easier entry and exit options for informed investors like angel investors, venture capitalists and private equity players, apart from offering better visibility and wider investor base and tax benefits to long-term investors.

Meanwhile, the report also called for a reduction in trading lot size and shorter interval for review of lot size after many SMEs, merchant bankers and market-makers cited this as a disincentive for entering the market. The report said market participants want the timeframe to review the lot size to be reduced from the current six months and lower the trading lot requirement of Rs 1 lakh to attract retail investors to the segment.

As SEBI continues to make business easier, it is important SMEs do not eye illegal gains through suspected money laundering and tax evasion activities.


CBDT extends deadline for filing ITRs with audit reports to Oct 15, 2018


The government has extended last date for filing of income tax returns (ITRs) for those taxpayers who are required to file their returns along with audit reports from Sept 30 to Oct 15, 2018.


The text of the notification by CBDT is as below:

CBDT has extended the due date for filing Income Tax Returns and audit reports from 30th September 2018 to 15th October 2018. However, there shall be no extension of the due date for purpose of Explanation 1 to section 234A (Interest for defaults in furnishing return) of the Act and the assessee shall remain liable for payment of interest as per provisions of section 234A of the Act.

                                  In its tweet, the income tax department has posted – “CBDT extends due date for filing of Income Tax Returns & audit reports from 30th Sept,2018 to 15th Oct, 2018 for all assessees liable to file ITRs for AY 2018-19 by 30.09.2018,after considering representations from stakeholders.”


However, it adds that “Liability to pay interest under section 234A of Income Tax Act will remain.” It is important to note that if one has any unpaid tax liability then penal interest on the same may be leviable.

Typically, tax practitioner bodies ask for an extension from the government, saying they needed more time to file returns for entities where tax audit report or transfer pricing report or other audit reports are required to be filed as per the law.

Even last year, on consideration of representations from various stakeholders and to facilitate ease of compliance by the taxpayers, CBDT had extended the ‘due-date’ for filing Income Tax Returns with audit reports as prescribed under the Income-tax Act,1961 from 31st October, 2017 to 7th November, 2017 for AY 2017-18.

Tax audit is a review of accounts of taxpayers with business or profession from an income tax point of view such as incomes, deduction, compliance with tax laws, etc. Taxpayers with turnover exceeding Rs 1 crore in business (not opted for presumptive taxation scheme) or whose gross professional income is over Rs 50 lakh need to get a tax audit done. Tax audit report needs to be filed on or before the 30 September of the subsequent financial year in case of taxpayers who have not entered into an international transaction.

Some chartered accountants have argued that they have been busy filing returns of individual tax payers like the salaried class till August 30. Consequently they have had little time to devote to preparing the audit reports for those tax payers whose accounts are required to be compulsorily subjected to tax audit. The number of clauses in the audit reports have also increased thereby increasing the time required, they have pointed out. For these reasons they had requested an extension of the deadline for filing tax returns with audit reports.

Highlights:

  • An audit is a review of accounts of taxpayers with business or profession from an income tax point of view such as incomes, deduction, compliance with tax laws, etc.
  • Those with turnover exceeding Rs 1 cr in business or whose gross professional income is over Rs 50 lakh need to get a tax audit done.
  • It is important to note that if one has any unpaid tax liability then penal interest on the same may be leviable.

CBDT Notification

CBIC to weed out a million assessees from GST tax net

Move to weed out the assessees from GST net will ensure effective tax base

The Central Board of Indirect Taxes and Customs (CBIC) has initiated a process to weed out approximately 12 lakh Goods and Services Tax (GST) assessees who have fallen off the tax map.

“The CBIC has communicated to field officers to take the process further. Now, field officers will issue show-cause notices, which is just a formality but a requirement under the law, and then complete the process for deregistration,” a Finance Ministry official told BusinessLine.

Currently, there are over 1 crore registered assessees on the GST Nework (GSTN), but the number of those who file returns is much less.

Under GST rules, any entity registered under the previous Sales Tax–VAT (Value-Added Tax), Central Excise Duty of Service Tax regulations was required to be enrolled under the GST and get provisional certificates.

However, if the turnover of the entity is less than the GST threshold and he/she is not willing to go for voluntary registrations, such assessees had the option to get the provisional registration cancelled and move out of the GST net. However, many assessees fail to complete the process, and so they continued to be a part of the GST-assessee base.

GST was implemented from July 1 last year. In the very first year, the number of registered assessees increased by 72.5 per cent to 1.14 crore. Of these, 66.17 lakh were existing taxpayers, that is, those registered under previous VAT/Sales Tax, Central Excise or Service Tax regime; the remaining were new ones. The Government believes that the new assessees came into the net as a result of demonetisation, which resulted in the formalisation of the economy, prompting more and more people to get registered.

During the pre-GST regime, States had different slabs for registration under VAT/ST, which was as low as ₹1 lakh and could go up to ₹10 lakh: the thresholds for Service Tax and Central Excise were ₹10 lakh and ₹1.5 crore, respectively. Now the universal threshold is ₹20 lakh (or ₹10 lakh in some States), which means there will be fewer people paying tax and filing returns.

Another Finance Ministry official said that while a wider tax base is good, there is also a need to ensure an ‘effective’ tax base; the latest initiative will help achieve that. This kind of a tax base will serve two purposes: it will lighten the burden on the GSTN, and it will give a real picture of the indirect tax regime.

Source: Business Line