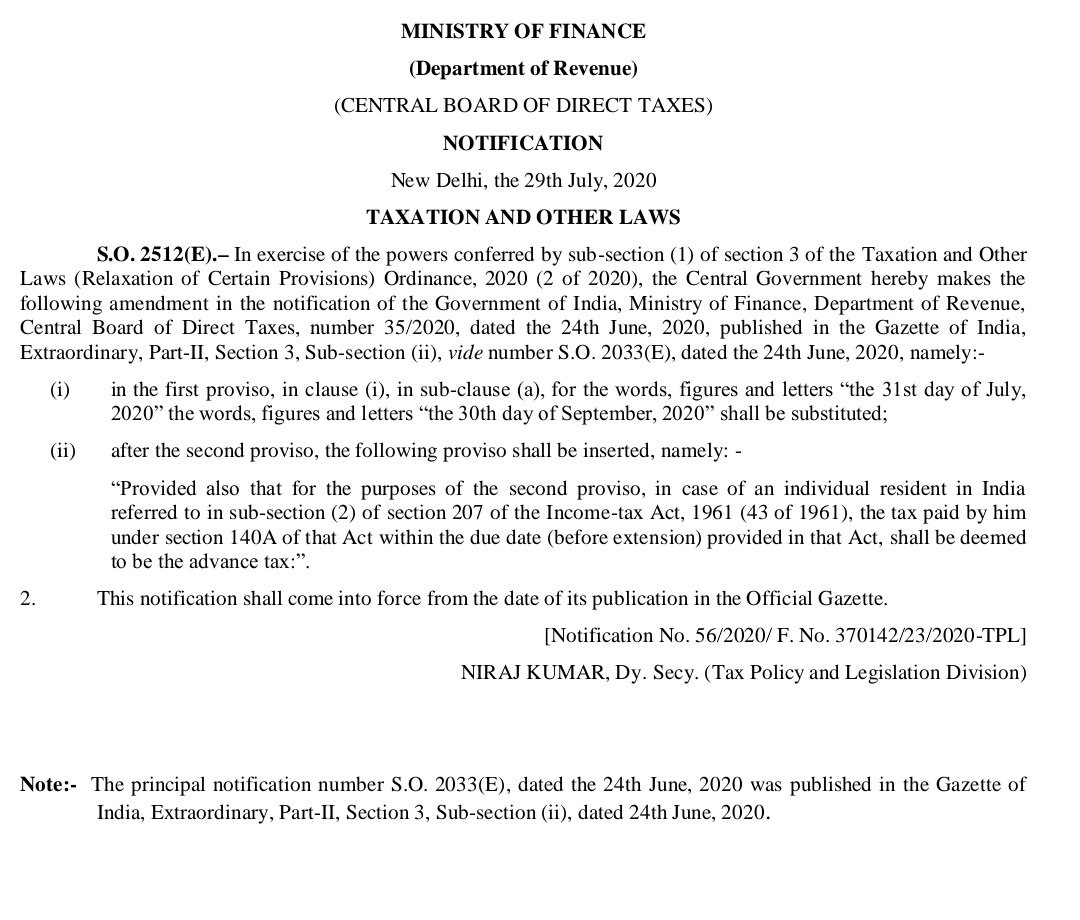
The Central Board of Direct Taxes (CBDT) on Wednesday (July 29) extended the deadline for filing income tax returns for 2018-19 fiscal till September 30 due to corona virus COVID-19 pandemic.
The Central Board of Direct Taxes (CBDT) on Wednesday (July 29) extended the deadline for filing income tax returns for 2018-19 fiscal till September 30 due to coronavirus COVID-19 pandemic.
“In view of the constraints due to the Covid pandemic & to further ease compliances for taxpayers, CBDT extends the due date for filing of Income Tax Returns for FY 2018-19 (AY 2019-20) from 31st July, 2020 to 30th September, 2020,” the Income Tax Department said in a tweet.
It is to be noted that this is the third extension given by the Centre to taxpayers to file both original and revised tax returns for 2018-19 fiscal.
In March, the Centre had extended the due date from March 31 to June 30 due to corona virus COVID-19 pandemic. Later in June, the date was again extended by a month till July 31.
If an individual fails to file the belated ITR, if due, by the deadline (i.e., September 30, 2020), then he/she will not be able to file the income tax return for the financial year 2018-19.
The CBDT has said that an individual can also file a revised ITR for FY2018-19 within this deadline.
The Income Tax department’s data analysis has identified certain taxpayers with high value transactions who have not filed ITR for AY 2019-20 (i.e. FY 2018-19). In addition to the non-filers, another set of return filers have also been identified wherein the high-value transactions do not appear to be in line with their Income Tax Return.
The Board said that the objective of the e-campaign is to facilitate taxpayers to validate their financial transaction information against information available with the IT department and promote voluntary compliance, especially for the assesses for the FY 2018-19 so that they do not need to get into notice and scrutiny process.
Under this e-campaign the Income Tax Department will send email/sms to identified taxpayers to verify their financial transactions related information received by the I-T department from various sources such as Statement of Financial Transactions (SFT), Tax Deduction at Source (TDS), Tax Collection at Source TCS), Foreign Remittances (Form 15CC) etc,” CBDT said.
It added that the department has collected information related to GST, exports, imports and transactions in securities, derivatives, commodities and mutual funds under information triangulation set up.
The campaign is scheduled for 11 days starting from July 20, 2020 and ending on July 31, 2020.
With the new e-campaign, the taxpayers will be able to access details of their high value transactions on the designated portal. They will also be able to submit online response by selecting among any of these options:
(i) Information is correct,
(ii) Information is not fully correct,
(iii) Information related to other person/year,
(iv) Information is duplicate/included in other displayed information, and
(v) Information is denied.
Also, department has clarified that there would be no need to visit any Income Tax office, as the response has to be submitted online.
This is a dual way move of the department, on one hand this will get more assessees under scrutiny and thus help in identifying defaulters. While on the other hand this will increase the speed of process and avoid unnecessary mental harassment of the assessees.
It may be noted that the last date for filing as well as revising the Income Tax Return for Assessment Year 2019-20 (relevant to FY 2018-19) is 31st July 2020.
The Central Board of Direct Taxes (CBDT) has issued refunds worth Rs 71,229 crore in more than 21.24 lakh cases upto 11th July, 2020, to help taxpayers with liquidity during COVID-19 pandemic, since the Government’s decision of 8th April, 2020 to issue pending income tax refunds at the earliest.
Income tax refunds amounting to Rs. 24,603 crore have been issued in 19.79 lakh cases to taxpayers and corporate tax refunds amounting to Rs. 46,626 crore in 1.45 lakh cases have been issued to taxpayers during COVID-19.
It is stated that the government has laid great emphasis on providing tax related services to the taxpayers without any hassles and is aware that during these difficult times of COVID-19 pandemic, many of the taxpayers are waiting to see that their tax demands and refunds reach finality as quickly as possible.
It is further emphasized that all the refund related cleaning up of the tax demands are being taken up on priority and is likely to be completed by 31st August, 2020.
Also, all applications for rectifications and for giving effect to appeal orders are to be uploaded on the ITBA.
It has been decided to do all the work of rectification and appeal effect on ITBA only.
It is reiterated that taxpayers, for quick processing of their refunds, should provide immediate response to the emails of I-T Department.
A quick response from the taxpayer in this regard would facilitate the I-T Department to process their refunds expeditiously.
Many taxpayers have submitted their responses electronically for rectification, appeal effects or tax credits. These are being attended to in a time bound manner.
All refunds have been issued online and directly into the bank accounts of the taxpayers.
-Through this one time relaxation scheme, ITR for FY 2014-15 to FY 2018-19 can be verified, on or before 30th September 2020. – All such verified ITRs shall be processed on or before 31st December 2020. – ITRs can be verified digitally through EVC or by sending duly signed a copy to CPC Bangalore.
The Central Board of Direct Taxes (CBDT) on Monday notified the one-time relaxation for verification of tax return for the Assessment Year 2015-16, 2016-17, 2017-18, 2018-19 and 2019-20, which are pending due to non-filing of ITR- V form and processing of such returns.
It has been brought to the notice of CBDT that a large number of electronically filed ITR still remains pending with the Income-Tax Department for want of receipt of a valid ITR-V Form at CPC, Bengaluru from the taxpayers concerned.
In law, consequences of non-filing the ITR-V within the time allowed is significant as such a return is/can be declared Non-est in law. Thereafter, all the consequences for non-filing a tax return, as specified in the Income-tax Act,1961 follow.
“The CBDT, in the exercise of powers under section 119 of the Act, in case of returns for Assessment Years 2015-16, 2016-17, 2017-18, 2018-19 and 2019-20 which were uploaded electronically by the taxpayer within the time allowed under section 139 of the Act and which have remained incomplete due to non-submission of ITR-V Form for verification, hereby permits verification of such returns either by sending a duly signed physical copy of ITR-V to CPC, Bengaluru through speed post or through EVC/OTP modes as listed in para 1 above.
Such verification process must be completed by 30.09.2020,” the circular said.
However, the circular clarified that this relaxation shall not apply in those cases, where during the intervening period, the Income Tax Department has already taken recourse to any other measure as specified in the Act for ensuring filing of a tax return by the taxpayer concerned after declaring the return as Non-est.
“CBDT also relaxes the time-frame for issuing the intimation as provided in the second proviso to sub-section (1) of Section 143 of the Act and directs that such returns shall be processed by 31.12.2020 and intimation of processing of such returns shall be sent to the taxpayer concerned as per the laid down procedure.
In refund cases, while determining the interest, provision of section 244A (2) of the Act would apply,” the circular said.
The levy is applicable only for large cash withdrawals. The intent is to minimize cash transactions and expand digital payments to enlarge the ambit of organized transactions over time.
In order to tighten the noose on those who don’t file income tax returns (ITR) despite earning taxable income and discourage cash transactions, the Finance Act 2020 introduced higher TDS (Tax Deducted at Source) rates on cash withdrawals for those who do not file ITR. The rates are applicable from 1 July.
Those who haven’t filed ITR for the past three financial years will have to pay TDS at the rate of 2%, if the amount withdrawn from the bank is above ₹20 lakh but doesn’t exceed ₹1 crore in a financial year. If the amount withdrawn exceeds ₹1 crore, TDS will be deducted at the rate of 5% under Section 194N of the Income-tax Act, 1961, for those who do not file ITR.
However, if you withdraw cash above ₹1 crore in a FY, you will still have to pay TDS whether you file ITR or not. In July 2019, the government, through Section 194N, had first introduced TDS at the rate of 2% on cash withdrawals above ₹1 crore in a financial year. This continues to be applicable.
“It is important to note that TDS shall be required to be deducted only when the aggregate amount of cash withdrawal during the FY by an individual from one or more of his bank accounts exceeds ₹20 lakh or ₹1 crore, as the case may be,” said Parizad Sirwalla, partner and head, global mobility services, tax, KPMG in India.
Further, tax will be deducted only on the amount exceeding the said thresholds. “If the individual withdraws a sum of money on regular intervals, the bank or financial institution will have to deduct TDS from the amount once the total sum withdrawn exceeds the threshold in a FY,” said Sirwalla.
For example, if person A has filed his ITR and if he withdraws cash up to ₹1 crore, then no TDS will be applicable. In case person A withdraws cash, which is more than ₹1 crore, then only 2% TDS will be applicable. If person A has withdrawn ₹1.25 crore in two transaction of ₹75 lakh in and ₹50 lakh, the TDS liability will only be on the excess amount that is ₹25 lakh.
On the other hand, if person B has not filed his ITR for the last three financial years and if he withdraws cash between ₹20 lakh and ₹1 crore, then 2% TDS will be applicable. In case person B withdraws cash which is more than ₹1 crore, then 5% TDS will be applicable.
“In case, the individual does not furnish the PAN to the bank or financial institution, then a TDS at a higher rate of 20% will become applicable,” said Sirwalla.
TDS will be applicable on withdrawals from banks, co-operative banks and post offices. The limit will apply on all accounts in the same bank. So, if you have multiple accounts with the same bank, then TDS will be applicable once you breach the mandatory limit across all the accounts or in any one of the account with the same bank. But for accounts with different banks, the limit will apply separately.
Banks will need to keep track of cash withdrawals and once the limit is breached, they will need to deduct TDS.
“Banks are asking declaration from people to ensure they have filed a return in the past three years or in any one of the last three years. This is done by banks for easier tracking as they wouldn’t know if the person has filed ITR or not,” said Sandeep Sehgal, director, taxes and regulatory, AKM Global.
The purpose of slapping this TDS is to minimize cash transactions and push digital payments.
“The levy is applicable only for large cash withdrawals in excess of ₹20 lakh/100 lakh per annum, as the case may be. The intent is to minimize cash transactions and expand digital payments to enlarge the ambit of organized transactions over time. So if individuals need to avoid this TDS levy, they should ensure that their cash withdrawals are restricted to the bare minimum and that the bulk of their payments happen through banking or digital means,” said Divakar Vijayasarathy, founder and managing partner, DVS Advisors LLP.
The ministry further said it has also taken a note of difficulties and concerns expressed by the taxpayers regarding filing of GSTR-3B and other returns.
The 40th GST Council met under the Chairmanship of Union Finance & Corporate Affairs Minister Smt Nirmala Sitharaman through video conferencing here today- 12th June 2020. The meeting was also attended by Union Minister of State for Finance & Corporate Affairs Shri Anurag Thakur besides Finance Ministers of States & UTs and senior officers of the Ministry of Finance& States/ UTs.
GST Council, has recommended to reduce / waive the interest/ late fee for delayed filing of GSTR 3B by small taxpayers (having turnover upto Rs. 5 crores) for the tax period from July 2017 to July 2020, as under:
Reduction in Late Fee for Past Returns (July 2017 to January 2020)
As a measure for trade facilitation and to clean-up the pendency in filing of GSTR 3B for the period from July 2017 to January 2020, the GST Council has recommended to reduce/ waive the late fee for past returns, as under:
a) ‘NIL’ late fee if there is no tax liability;
b) Maximum late fee capped at Rs. 500/- per return if there is any tax liability.
The reduced rate of late fee would apply for all the GSTR-3B returns furnished between 01.07.2020 to 30.09.2020.
Relief for filing of returns for February – April 2020
Further GST Council has recommended to provide relief for small taxpayers (having turnover upto Rs. 5 Crores) by way of reduced interest of 9% in lieu of 18% upto 30 Sept. 2020, for late filing of returns for the tax periods February, March and April 2020. This interest shall be charged beyond specified last date (staggered upto 6th July 2020) for filing of GSTR 3B return for the said tax periods.
Relief for filing of returns for May – July 2020
Also, GST Council has recommended to provide relief for small taxpayers (having turnover upto Rs. 5 Crores) by way of waiver of interest and late fee upto 30 Sept. 2020, for late filing of GSTR 3B return for the tax periods May, June and July 2020.
Recommendations of GST council related to Law & Procedure
The GST Council has made the following recommendations on Law & Procedures changes.
Measures for Trade facilitation:
Reduction in Late Fee for past Returns:
As a measure to clean up pendency in return filing, late fee for non-furnishing FORM GSTR-3B for the tax period from July, 2017 to January, 2020 has been reduced / waived as under: –
i) ‘NIL’ late fee if there is no tax liability;
ii) Maximum late fee capped at 500/- per return if there is any tax liability.
The reduced rate of late fee would apply for all the GSTR-3B returns furnished between 01.07.2020 to 30.09.2020
b) Further relief for small taxpayers for late filing of returns for February, March & April 2020 Tax periods:
For small taxpayers (aggregate turnover upto Rs. 5 crore), for the supplies effected in the month of February, March and April, 2020, the rate of interest for late furnishing of return for the said months beyond specified dates (staggered upto 6th July 2020) is reduced from 18% per annum to 9% per annum till 30.09.2020. In other words, for these months, small taxpayers will not be charged any interest till the notified dates for relief (staggered upto 6th July 2020)and thereafter 9% interest will be charged till 30.09.2020.
c) Relief for small taxpayers for subsequent tax periods (May, June & July 2020):
In wake of COVID-19 pandemic, for taxpayers having aggregate turnover upto Rs. 5 crore, further relief provided by waiver of late fees and interest if the returns in FORM GSTR-3B for the supplies effected in the months of May, June and July, 2020 are furnished by September, 2020 (staggered dates to be notified).
d) One time extension in period for seeking revocation of cancellation of registration:
To facilitate taxpayers who could not get their cancelled GST registrations restored in time, an opportunity is being provided for filing of application for revocation of cancellation of registration up to 30.09.2020, in all cases where registrations have been cancelled till 12.06.2020.
Certain clauses of the Finance Act, 2020 amending CGST Act 2017 and IGST Act, 2017 to be brought into force from 30.06.2020.
Note: The recommendations of the GST Council have been presented in this release in simple language for information of all stakeholders. The same would be given effect through relevant Circulars/ Notifications which alone shall have the force of law.
Council to meet again in July to specially discuss how the government can pay off states for the compensation cess dues, since the funds are falling short.
The amendment, aims at controlling tax evasion, and bring glassiness Form 26AS, which is now being replaced with a new Annual Information Statement (AIS) i.e Form 26AIS.
The Central Board of Direct Taxes (CBDT) on Thursday notified Income Tax (11th Amendment) Rules, 2020.
In exercise of the powers conferred by section 285BB read with section 295 of the Income-tax Act, 1961 (43 of 1961), the Central Board of Direct Taxes hereby makes the following rules further to amend the Income-tax Rules, 1962, namely:-
In Income Tax Rules, 1962 Rule 114-I relating to Annual Information shall be inserted which is, “the Principal Director General of Income Tax (System) or the Director-General of Income Tax (Systems) or any person authorized by him shall, under Section 285BB of the Income-Tax Act, 1961, upload in the registered account of the assessee an annual information statement in Form No. 26AS containing the information specified in the column (2) of the table below, which is in his possession within three months from the end of the month in which the information is received by him.”
The notification consists of a table that contains the nature of information which includes information relating to a tax deduction or collected at source; specified financial transaction; payment of taxes; demand and refund; pending proceedings; and completed proceedings:
Sl. No.
Nature of information
(i)
Information relating to tax deducted or collected at source
(ii)
Information relating to specified financial transaction
(iii)
Information relating to payment of taxes
(iv)
Information relating to demand and refund
(v)
Information relating to pending proceedings
(vi)
Information relating to completed proceedings
(vii)
Any other information in relation to sub-rule (2) of rule 114-I
The amendment, aims at controlling tax evasion, and bring glassiness Form 26AS, which is now being replaced with a new Annual Information Statement (AIS) i.e Form 26AIS.
Further sub-clause (2) of Rule 114-I says, “the Board may also authorize the Principal Director General of Income-tax (System) or the Director-General of Income Tax (Systems) or any person authorized by him to upload the information received from any officer, authority or body performing any function under any law or the information received under an agreement referred to in Section 90 or Section 90A of the Income Tax Act, 1961 or the information received from any other person to the extent as it may deem fit in the interest of the revenue in the annual information statement referred to in sub-clause (1).”
Lastly, sub-clause (3) of Rule 114-I says, “the Principal Director General of Income-tax (System) or the Director-General of Income Tax (Systems) shall specify the procedures, formats, and standards for the purpose of uploading of annual information statement referred to in sub-clause (1).”