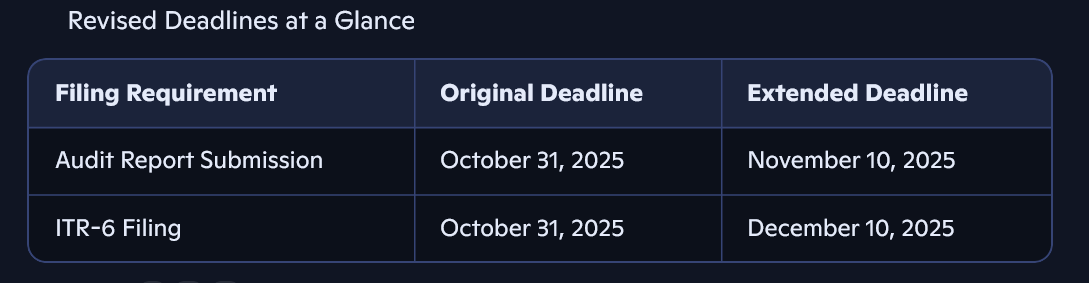
The Central Board of Direct Taxes (CBDT) has extended the due date for filing ITR-6 for AY 2025–26 by 10 days, moving the deadline from October 31 to December 10, 2025. This extension applies to companies and entities requiring audited financials.
In a welcome move for corporate taxpayers and professionals, the Central Board of Direct Taxes (CBDT) has announced a 10-day extension for filing Income Tax Return (ITR-6) for the Assessment Year (AY) 2025–26. The revised deadline is now December 10, 2025, replacing the earlier cutoff of October 31, 2025.
Who does this apply to?
This extension specifically benefits:
Companies and entities whose accounts are subject to audit under the Income-tax Act, 1961.
Assessees covered under clause (a) of Explanation 2 to sub-section (1) of Section 139, which includes firms and individuals with mandatory audit requirements.
Why the Extension?
The decision follows industry representations and logistical challenges faced by tax professionals in meeting the original deadlines. It also aligns with a recent Gujarat High Court directive that extended the audit report deadline to November 30, 2025.
Implications for Taxpayers
More time for compliance: Companies now have additional breathing room to finalize audited accounts and file returns accurately.
Avoid penalties: Timely filing by the new deadline helps avoid late fees and interest under Section 234F.
Better quality submissions: The extension allows for thorough review and error-free filings, especially for complex corporate structures.
What should you know?
Update your compliance calendar to reflect the new deadlines.
Coordinate with auditors to ensure timely submission of audit reports by November 10.
Prepare ITR-6 filings with all required disclosures, including tax audit details, transfer pricing reports (if applicable), and financial statements.
This extension is a strategic relief for stakeholders navigating the complexities of corporate taxation. As deadlines shift, staying proactive and organized remains key to smooth compliance. If you’re a tax professional or company executive, now’s the time to realign your filing strategy and ensure timely submission under the revised schedule.
In a significant move to ease compliance pressure, the Ministry of Corporate Affairs (MCA) has extended the deadline for companies to file their financial statements and annual returns for the financial year (FY) 2024–25 without additional fees until December 31, 2025, according to General Circular No. 06/2025 issued on October 17, 2025.
The extension was granted due to the deployment of revised e-forms on the MCA-21 Version 3 portal and requests from stakeholders.
The new deadline for filing financial statements and annual returns is December 31, 2025, with only normal fees applicable during this period.
This extension does not alter the statutory deadline for holding Annual General Meetings (AGMs). Companies should hold their AGM within the statutory deadline and file forms before December 31, 2025, to avoid extra fees. For more details, refer to the General Circular No. 06/2025.
The circular provides relaxation for the filing of following forms:
Form AOC-4 – Filing of financial statements
Form AOC-4 (CFS) – Consolidated financial statements
Form AOC-4 XBRL / Non-XBRL – For companies required to file in structured formats
Form MGT-7 / MGT-7A – Annual return for companies and small companies/OPCs respectively
Companies must take care that the ROC forms/returns are filed correctly and within the given date. Not adhering to the instructions can lead them to deal with various penalty charges and legal consequences.
Therefore, it is recommended that companies reach out to professionals to assist them in ensuring compliance with the filing needs.
The Ministry of Corporate Affairs has issued General Circular No. 06/2025 dated October 17, 2025, allowing companies to file their financial statements and annual returns for FY 2024–25 using the newly revised e-Forms (MGT-7, MGT-7A, AOC-4 series) on the MCA-21 Version 3 portal without additional fees until 31st December 2025.
This relaxation aims to help companies adapt to the new forms but does not extend statutory deadlines for holding AGMs under the Companies Act, 2013. Companies failing to meet statutory timelines remain liable for legal action, and filings made after this period will attract normal and additional fees as per applicable rules.
The Ministry has revised the e-Forms MGT-7, MGT-7A, AOC-4, AOC-4 CFS, AOC-4 NBFC (Ind AS), AOC-4 CFS NBFC (Ind AS), AOC-4 (XBRL) for annual filings, which were deployed on the MCA-21 Version 3 portal recently.
In view of the deployment of the new e-Forms, and considering that companies may require some time to get familiarized with the filing process, and keeping in view the requests received from various stakeholders, it has been decided that companies will be allowed to complete their annual filings pertaining to FY 2024-25 till 31st December, 2025 without payment of additional fees.
However, it is hereby clarified that this General Circular shall not be construed as conferring any extension of statutory time for holding of AGMs by the companies under the Companies Act, 2013 (the Act) and the companies which have not adhered to the relevant statutory timelines shall continue to be liable to legal action under the appropriate provisions of the Act.
Any filings made subsequent to the currency of this General Circular would attract payment of all fees, including additional fees, as provided in the Companies (Registration Offices and Fees) Rules, 2014, from the date when such filings were actually due under the Act.
This is issued with the approval of the Competent Authority.
MCA extends DIR-3 KYC filing deadline to October 15, 2025: A sigh of relief for directors
The Ministry of Corporate Affairs (MCA) has announced a much-awaited extension for filing the DIR-3 KYC and DIR-3 KYC-WEB forms without additional fees. This provides directors with more time to complete their annual compliance requirements.
Key takeaways from the extension
Revised Due Date: The deadline has been extended from the usual September 30, 2025, to October 15, 2025.
No Additional Fee: The extension allows DIN holders to file their KYC details without incurring the standard ₹5,000 late filing penalty.
Applicability: The extension covers both e-form DIR-3 KYC (for first-time filers or those updating details) and the web-based DIR-3 KYC-WEB (for subsequent annual filings with no changes).
Reason for Extension: The MCA granted the extension after receiving requests from stakeholders to provide more time for compliance.
Who needs to file?
The DIR-3 KYC filing is a mandatory annual compliance requirement for every individual who holds a Director Identification Number (DIN). This includes:
Every DIN holder, regardless of whether they are currently serving as a director in a company or a designated partner in an LLP.
Even individuals whose DIN has been deactivated for non-compliance are required to file the form to reactivate it.
The importance of timely filing
Filing your DIR-3 KYC is a simple yet crucial step to ensure your director status remains active and compliant. Here’s why you should use this extension wisely:
Avoid DIN Deactivation: Failure to file the form by the new deadline will result in the deactivation of your DIN.
Prevent Penalties: If you miss the extended deadline, you will have to pay a steep penalty of ₹5,000 to get your DIN reactivated.
Maintain Corporate Governance: Timely compliance ensures that the MCA maintains accurate and updated records of directors, which is vital for corporate transparency and governance.
What you need to do
Gather Information: Ensure you have your personal mobile number and email ID ready for OTP verification.
Access the Portal: Log in to the MCA V3 portal to initiate the filing process.
Choose the Correct Form: Select the appropriate form based on your filing history: e-form DIR-3 KYC (for first-timers or updates) or web-form DIR-3 KYC-WEB (for subsequent filings with no changes).
Complete the Process: Verify your details and submit the form before October 15, 2025, to avoid any late fees.
Final thoughts
This extension is a welcome move by the MCA, especially for those who faced challenges during the initial filing period. It provides a valuable opportunity to complete the necessary compliance without the burden of additional fees. Directors are advised to take advantage of this extension and file their DIR-3 KYC forms at the earliest to ensure a smooth and penalty-free compliance process.
CBDT extends due date, taking into account the hardships faced by taxpayers and the representations received from professional bodies, by one-month relief for audit report submissions.
The Central Board of Direct Taxes (CBDT) has announced a significant relief for taxpayers and professionals by extending the due date for filing various audit reports under the Income-tax Act, 1961. The deadline, which was earlier set for 30th September 2025, has now been extended to 31st October 2025 for the Assessment Year (AY) 2025–26.
Why Was the Extension Granted?
The decision came after multiple representations from professional associations, including Chartered Accountant bodies, who highlighted the challenges faced by taxpayers and practitioners in completing audits on time.
Key reasons cited include:
Natural calamities such as floods in several regions, which disrupted normal business and professional activities.
Court petitions filed before various High Courts seeking relief.
Heavy workload on tax professionals, especially after the individual ITR filing deadline in mid-September.
Interestingly, CBDT clarified that the Income-tax e-filing portal has been functioning smoothly, with no major technical glitches. By 24th September 2025, over 4.02 lakh Tax Audit Reports (TARs) had already been uploaded, with more than 60,000 TARs filed in a single day.
Who Needs to File a Tax Audit Report?
Under Section 44AB of the Income-tax Act, tax audit is mandatory for:
Businesses with turnover above ₹1 crore (limit increases to ₹10 crore if cash transactions are ≤ 5%).
Professionals with gross receipts above ₹50 lakh.
Taxpayers under presumptive taxation (Sections 44AD/44ADA/44AE) if they declare lower profits than prescribed and their income exceeds the basic exemption limit.
What Happens If You Miss the Deadline?
Failure to file the audit report within the due date can attract penalties:
0.5% of turnover/gross receipts, subject to a maximum of ₹1.5 lakh.
The penalty is discretionary and may be waived if reasonable cause is demonstrated.
Impact on ITR Filing Deadlines
Currently, the due date for filing Income Tax Returns (ITRs) for taxpayers subject to audit remains 31st October 2025. However, experts suggest that CBDT may issue a separate notification to extend the ITR filing deadline to 30th November 2025, in line with past practice.
Key Takeaways
New due date for filing audit reports: 31st October 2025.
Reason for extension: Natural calamities, workload pressure, and professional representations.
E-filing portal status: Stable and fully functional.
Relief provided: Extra time for taxpayers and professionals to ensure accuracy and compliance.
Conclusion
The extension of the audit report filing deadline by CBDT is a welcome move, offering much-needed breathing space to taxpayers and professionals alike. While the e-filing system is robust, real-world challenges such as natural disasters and workload bottlenecks cannot be ignored. This proactive step ensures compliance without undue stress, reinforcing CBDT’s commitment to balancing efficiency with empathy.
The GST Council has announced major rate cuts and compliance reforms in its September 2025 meeting. Highlights of new GST slabs, effective dates, process changes, and how businesses should prepare.
India’s GST system just received its biggest shake-up since rollout: the GST Council approved a major rate rationalisation (moving to a much simpler slab structure), together with a package of taxpayer-friendly process reforms. The changes – aimed at reducing complexity, lowering prices for many everyday goods, and speeding up compliance/refunds for businesses – are to be implemented from 22 September 2025 (with a few exceptions and phased rollouts). Here’s a clear, practical, and source-backed breakdown of what happened, why it matters, and what businesses and consumers should expect next.
Main Highlights
Two main GST slabs: 5% (merit/essential) and 18% (standard) — the 12% and 28% slabs are being collapsed into these. A special de-merit 40% rate is proposed for a small set of luxury/sin goods (tobacco, very high-end vehicles, etc.).
Implementation date: Most changes effective 22 Sept 2025 (Navratri start). Tobacco/pan masala items will have separate timing. Some elements may be phased to manage compensation fund impacts.
Process reforms: Faster/automated registration for low-risk businesses, pre-filled returns, auto/refund acceleration, risk-based provisional refunds for exporters and a timeline to operationalise many tech changes.
Anti-profiteering approach: legal anti-profiteering machinery (Section 171) hasn’t been reinstated in an aggressive form — the government is asking industry to pass on benefits while monitoring and states are pushing for safeguards. Expect guidance from tax authorities.
What exactly changed – the rate map (summary)
The Council rationalised slabs to simplify compliance and broaden the “common man” gains.
5% slab — Will cover a large set of essentials, many medicines/healthcare inputs, basic food items and several household staples and smaller consumer items previously at 12%/18%. (Examples reported: roti, many edible goods, certain medicines and diagnostic kits, small household appliances in some categories).
8% slab — The standard rate now for most manufactured goods and many services previously at 18%/28%/12% where reclassification makes sense (e.g., many auto components, some consumer durables moved to 18%).
40% de-merit slab — A higher, selective rate for luxury and sin goods (tobacco products, very high-end cars, other items identified by the Council). These are explicitly carved out to preserve revenue and to tax dis-incentivise harmful/very high-end consumption.
Implementation mechanics & phasing
Effective date: The Council recommended implementation from 22 September 2025 for most goods/services. Tobacco and tobacco-related items will have separate treatment (different effective date to be notified) because of compensation cess and administrative considerations. Some elements (especially where compensation cess/compensation fund is concerned) may be phased to smooth state receipts.
Why phased? Several states flagged potential revenue loss concerns; the Council stressed consensus but also acknowledged fiscal impacts and decided to manage timing and the compensation cess account accordingly. Expect circulars from CBIC explaining exact implementation steps (tariff notifications, HSN crosswalks, valuation/credit rules).
Process reforms (big ticket operational changes)
The meeting wasn’t just about rates – there’s a parallel package to make compliance quicker and less painful:
Automated/simplified registration for low-risk applicants (target: 3 days/automated approval for eligible applicants). This aims to cut onboarding friction for SMEs and startups.
Prefilled returns & auto refunds — prefilled return architecture and auto refunds (including provisional/90% provisional refunds for exporters based on risk evaluation for specific sectors) to speed liquidity to business. Rollouts/timelines were announced — many measures to be operationalised by October–November 2025.
Faster refund windows (seven-day targets for specific exporters/priority cases) and risk-based provisional mechanisms to reduce stuck refunds.
Tribunal and dispute reforms — strengthening appellate/ADR mechanisms (e.g., national benches for Advance Rulings) to improve consistency in rulings.
These process reforms are intended to complement rate rationalisation so taxpayers – especially MSMEs and exporters — face lower compliance cost and faster cash flows.
Anti-profiteering and price transmission
The Council/officials have made it clear that industry is expected to pass benefits of lower GST to consumers. The strict anti-profiteering law (Section 171) hasn’t been robustly re-invoked as a new enforcement blitz, but states have insisted on safeguards and monitoring. Tax authorities and state governments will watch prices and may ask for evidence of benefit transmission; businesses should act cautiously and transparently.
Practical tip for retailers/manufacturers: document the cost/repricing methodology, issue credit notes where appropriate and update pricing policies — this is both good business practice and a defensive step in case of state queries.
Sectoral winners and losers — who gains, who pays more
Likely beneficiaries (cheaper): FMCG staples, many food items, certain medicines & diagnostic reagents, entry-level autos and components, many household goods and some construction materials (cement, tiles — reported moves from 28→18% / 12→5% for specific items). These cuts will help consumer demand and reduce input costs for industries like housing and consumer durables.
Likely paying more / targeted up-taxed: Very high-end cars, tobacco & pan masala, certain luxury goods moved into the 40% de-merit slab (aim: revenue neutrality and disincentive).
Stakeholder notes: Auto dealers, consumer durables firms and textiles have broadly welcomed the move as demand stimulative; states with manufacturing-heavy revenue bases have flagged short-term revenue pain and asked for compensatory arrangements.
How decisions were made (short explanation of the Council process)
The GST Council is a constitutional body (Article 279A) that makes recommendations on rates and other GST matters. Decisions are taken with a weighted voting mechanism (Centre has one-third weight, states two-thirds) and normally by a three-fourths weighted majority — but in practice the Council aims for consensus. The 56th meeting reported unanimous consensus on the package.
What to watch next
Notifications from CBIC/CBIC circulars giving precise tariff/HSN crosswalks, valuation rules and timeline for phased items. (Those will be the legally binding documents.)
State responses about compensation/temporary support if they claim revenue shortfalls — any fiscal transfers or special measures will be announced in coming weeks.
Price monitoring: watch for state consumer affairs departments and tax authorities asking firms to show price transmission evidence.
Final take
This is a large, pro-consumer and pro-growth move designed to simplify GST’s complexity and spur demand ahead of the festive season — while also modernising the compliance stack (faster registration/refunds). It’s politically significant (broad consensus) and technically big — businesses should act fast to align systems, pricing and documentation. States’ fiscal positions will be the main political/implementation watchpoint, so expect more operational clarifications from CBIC in the coming days.
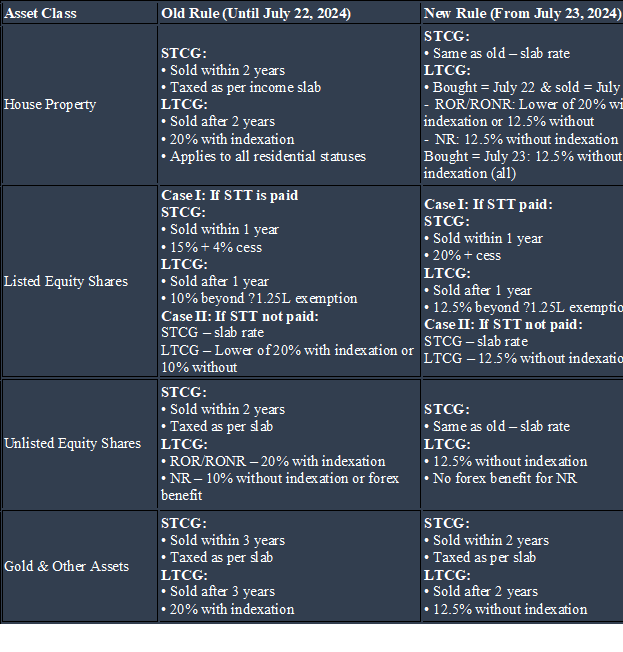
The Union Budget 2024 introduced significant changes to capital gains taxation, particularly effective from July 23, 2024, which taxpayers across India need to be aware of to ensure compliance and efficient filing. The capital gain tax rules were changed in the mid-year from FY 2024-25 (Asst Year 2025-26). Due to this, a taxpayer needs to be aware of both the old and new rules to pay the correct tax, depending on the date of sale. Here is a handy guide for individual taxpayers who have STCG and LTCG from houses, listed equity, unlisted equity, gold, and other assets.
Key Changes to Capital Gains Taxation (Effective July 23, 2024) The Union Budget 2024-25 has introduced notable adjustments, particularly impacting long-term capital gains (LTCG) and the application of indexation benefits.
* Increased Tax Rates: The tax rates for both short-term capital gains (STCG) and long-term capital gains (LTCG) have been revised. STCG on specified financial assets where Securities Transaction Tax (STT) is paid has increased from 15% to 20%. For most asset types, the LTCG tax rate has been raised from 10% to 12.5%.
* Revised LTCG Exemption Limit: The annual exemption limit for LTCG arising from the sale of equity shares or equity-oriented units has been increased from ₹1 lakh to ₹1.25 lakh.
* Indexation Benefit Changes: A significant change is the removal of indexation benefits for most assets transferred on or after July 23, 2024. This means the purchase price will not be adjusted for inflation, potentially leading to higher taxable gains.
Asset-Specific Capital Gains Tax Ready Reckoner
Here’s a breakdown of how capital gains are taxed for different asset classes, considering the pre- and post-July 23, 2024 scenarios:
House Property The taxation of house property capital gains depends on the date of acquisition and sale, as well as your residential status. * Short-Term Capital Gains (STCG): If a house property is sold within 24 months of purchase, the gains are considered STCG and are taxed according to your applicable income tax slab rates, irrespective of your residential status (Resident Ordinary Resident – ROR, Resident Not Ordinary Resident – RONR, or Non-Resident Indian – NRI). * Long-Term Capital Gains (LTCG): * Property bought on or before July 22, 2024, and sold on or after July 23, 2024: * ROR/RONR individuals have an option: pay 20% tax with indexation benefit or 12.5% tax without indexation. Taxpayers can choose the more beneficial option. * NRIs will pay 12.5% tax without indexation. * Property bought on or after July 23, 2024: LTCG will be taxed at a flat 12.5% without indexation for all taxpayers, regardless of residential status.
2. Listed Equity Shares The tax treatment for listed equity shares depends on whether STT has been paid. * STCG (Sold within 1 year): * If STT is paid: Taxed at 20% plus cess (for transfers on or after July 23, 2024). * If STT is not paid: Taxed at your income tax slab rates. * LTCG (Sold after 1 year): * If STT is paid: Taxed at 12.5% beyond the ₹1.25 lakh exemption limit (for transfers on or after July 23, 2024). * If STT is not paid: Taxed at 12.5% without indexation.
3. Unlisted Equity Shares * STCG: Taxed at your income tax slab rates. * LTCG: Taxed at 12.5% without indexation. Note that NRIs do not receive forex benefits on unlisted equity.
4. Gold and Other Assets * STCG (Sold within 2 years): Taxed at your income tax slab rates. * LTCG (Sold after 2 years): Taxed at 12.5% without indexation under the new rules. Under old rules, a 3-year holding period for LTCG was applicable, taxed at 20% with indexation.
Filing Your Income Tax Return (ITR) for FY 2024-25 (AY 2025-26) The Income Tax Department has enabled online utilities for filing ITR-2 and ITR-3 forms, which are relevant for individuals and Hindu Undivided Families (HUFs) with capital gains income. * ITR-2: Used by individuals and HUFs who have income from capital gains but do not have earnings from business or profession. * ITR-3: Applicable to taxpayers including stock traders, with provisions for reporting capital gains and other specified incomes.
Key Changes in Capital Gains Taxation:
Flat LTCG Rate Introduced
– New Rate: Long-Term Capital Gains (LTCG) are now taxed at 12.5% across most asset classes.
– Old Rate: Previously, LTCG was taxed at 20% with indexation or 10% without indexation, depending on the asset.
– Impact: For assets acquired after July 23, 2024, indexation is not allowed, which may increase tax liability if inflation-adjusted cost was significantly higher.
1. STCG Rate Hiked for Listed Equities
– New Rate: Short-Term Capital Gains (STCG) on listed equities now taxed at 20% (up from 15%).
– Impact: Traders and short-term investors face higher tax liability.
2. LTCG Exemption Limit Raised
– New Limit: Exemption on LTCG from listed equity and equity mutual funds increased to ₹1.25 lakh (from ₹1 lakh).
– Impact: Slight relief for small investors.
3. Indexation Benefit Restricted
– Allowed Only If: Property was acquired before July 23, 2024.
– Impact: For newer acquisitions, no indexation, which may result in higher taxable gains.
4. Holding Period Simplified
– Listed Securities: LTCG if held >12 months.
– Other Assets: LTCG if held >24 months.
– Impact: Easier classification, but may affect timing strategies.
Conclusion:
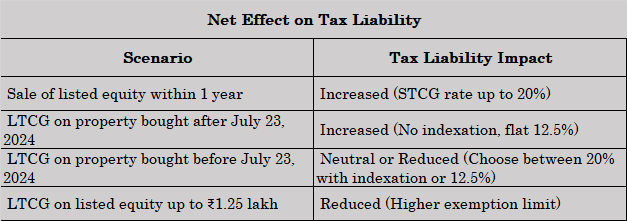
The capital gains tax amendments for Assessment Year 2025–26 have introduced a mix of increases and simplifications, depending on the asset type and transaction date. Here’s a breakdown of how they affect tax liability: