Finance ministry raises duty drawback rates for exports for engineering, marine, leather and textiles

As exports fell for the 11th month in a row in October 2015, the government on Monday increased the refunds to exporters on duties on imports, particularly those relating to engineering products. This would also neutralise the impact of import duty hike in steel, used in engineering products.

Besides engineering goods, the government raised the duty drawback rates on composite products such as leather handbags, ready-made garments made of cotton wool and those made of cotton with lycra.

The Central Board of Excise and Customs raised the duty drawback rate by two percentage points for the engineering sector, which would allow higher tax refund to exporters of machinery and appliances, electrical machinery, tools and implements, among others.

“These revised rates are based on average incidence of customs and central excise duties and service tax related with the manufacture of export goods and involve substantial total drawback for exporters,” the government said in a release.

After the additional hike in the duty drawback, the rate for certain engineering products could go up to close to eight per cent, sources said.

However, the government did not take into the account the 20 per cent safeguard duty imposed on hot-rolled steel. “It is a positive that the government has made up for the hike in duty on steel. But the smaller firms will have to bear the impact of safeguard duty, as it is not factored in new duty drawback announced ” said Ajay Sahai, director-general and CEO, Federation of Indian Export Organisations.

CRUX OF THE MATTER

  • Move expected to neutralise impact of import duty hike in steel
  • Duty drawback rates raised on engineering goods, leather handbags, readymade garments made of cotton wool and cotton with lycra, shrimps
  • Two percentage points rise in duty drawback for engineering sector to allow higher tax refund to exporters of machinery and appliances, electrical machinery, tools among others
  • Former CMD N Ramanujan had worked out a JV with Titan Watches when Xerxes Desai was heading it. But the government turned it down
  • The only operational plant at Tumkur, Karnataka, has 2 million-unit capacity of quartz watches
  • The watch model, Kanchan, used to sell at a premium in the grey market at Rs 1,000, when its legal price was Rs 700

Duty drawback is a refund of certain types of customs and Central excise duties as well as service tax on imports of inputs or raw materials that are used to manufacture goods for exports.

The revised rates of duty drawback notified by the finance ministry will be effective from November 23.

In a first, the government extended the brand rate of duty drawback to wheat. It also provided a mechanism to pay provisional drawback to exporters soon after export, for certain exports made under the claim for brand rate of duty drawback.

“This was pending for a long time. In a positive development, the government also allowed exporters claiming brand rate of drawback rate to avail provisional drawback rate until the brand rate is decided,” said Sahai.

The government added the expert committee would look into exporters’ concerns arising from new schedule of rates and make further recommendations to the government in January 2016. The government will also take into account feedback from export promotion councils to this effect.

Source:
http://www.business-standard.com/article/economy-policy/finmin-raises-duty-drawback-rates-to-arrest-export-slump-115111700035_1.html

India, Japan sign action plan to double investments in 5-years

The governments of India and Japan signed an agreement on Thursday for doubling of Japanese investment into Indian firms in the next five years, and  boosting two-way trade. The signatories were Commerce and Industry Minister Nirmala Sitharaman and Japan’s minister for economy, trade and industry, Yoichi Miyazawa.

The plan was categorised into five broad areas: development of selected townships in India, promotion of investment and infrastructure development, further development and cooperation in information technology, enhancing cooperation in strategic sectors and Asia-Pacific economic integration.

Signing of the action plan is seen “as a step further in improving the trade relationship between India and Japan as a follow-up of Prime Minister Narendra Modi’s visit to Japan last year,” stated a release quoting Miyazawa.

According to Sitharaman, the agenda was in line with PM’s Make in India plan that will further investments from Japan into the country’s manufacturing sector.

Last year, the Department of Industrial Policy and Promotion under the ministry of commerce and industry had set up a mechanism to fast-track Japanese investments named ‘Japan Plus.’

During Modi’s visit, Japanese Prime Minister Shinzo Abe had set a target of 3.5 trillion yen ($33.5 billion) of public and private investment and financing from Japan including official development assistance to India to be made over five years. There are already 1,209 Japanese firms operating in India out of which 137 have started their operations after October 2013.

Japan is the fourth largest foreign direct investment (FDI) contributor to India, with major interests in pharmaceuticals, automobiles, and services sectors accounting for 7.46 per cent of total FDI equity inflows into India. During April 2000-November 2014, FDI from Japan into India stood at $17.55 billion.

Under the Tokyo Declaration for Japan-India Special Strategic and Global Partnership, Modi and Abe have set a target of doubling Japanese FDI and the number of Japanese firms in India by 2019.

Source: http://www.business-standard.com/article/economy-policy/india-japan-sign-action-plan-to-double-investments-in-5-years-115043000401_1.html

Strengthening Iran-India trade ties a great opportunity for both


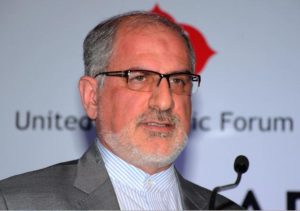
Iran’s Ambassador to India Gholamreza Ansari at the inaugural session of the United Economic Forum’s Trade Summit 2015 in Chennai on Saturday.

Iran’s Ambassador to India Gholamreza Ansari at the inaugural session of the United Economic Forum’s Trade Summit 2015 in Chennai on Saturday.

India is on top of Iran’s list of partners with which it plans to strengthen economic ties in the region, according to Ghulam Raza Ansari, Ambassador of Iran to India.

Ansari, who just returned from Iran after participating in a seminar on its economic direction post-sanctions, said that the countries in the region had been Iran’s biggest asset in tiding over a three-decade long sanction imposed by the West.

Iran had managed the sanctions and achieved its rights through diplomacy and cooperation. It will first focus on growing trade relations in the region and India is a top priority. There is a great opportunity for both countries to increase economic relations across a wide range of sectors such as oil and gas including transmission, metal, food and agriculture.

Tamil Nadu particularly was first destination of Iran’s investments when it invested in 1960s in petrochemicals and refinery, he said, addressing the inaugural function of a two-day trade summit organised by the United Economic Forum, a platform for the socio-economic development of muslims.

Mufti Mohammad Sayeed, Chief Minister, Jammu and Kashmir, said education is the key to the development of the community.

The Sachar Committee, which had been appointed by the previous Central Government to go into socio economic status of Muslims and make recommendations for their development, had pointed out that educational backwardness was the reason for economic backwardness.

The Committee’s recommendations such as starting quality government schools in areas where there are Muslims, schools for girls and skill development facilities need to be implemented. Degrees awarded by traditional institutions such as the Madarasas must be recognised in mainstream education and competitive exams, he said.

Ahmed AR Buhari, President, UEF, said India is a bright spot in the globe in terms of economic development. The forum is actively participating in the ‘Make in India’ campaign launched by the Prime Minister, Narendra Modi.

UEF has set a target of garnering ₹ 10,000 crore in investments during the two-day summit and has tied up investments of over ₹ 2,000 crore on the first day across a range of sectors including tourism, hospitality, real estate and logistics.

Source: http://www.thehindubusinessline.com/economy/strengthening-iranindia-trade-ties-a-great-opportunity-for-both/article7877117.ece


RBI allows foreign currency-rupee swap transactions

RBI said that such swap transactions could be undertaken by the MFI/IFI concerned on a back-to-back basis with an authorised dealers (AD) Category-I bank in India

The Reserve Bank of India (RBI) on Thursday allowed residents having a long-term foreign currency liability to enter into foreign currency-rupee swaps with multilateral or international financial institutions (MFI/IFI) in which the government of India is a shareholding member, subject to certain conditions.

RBI said that such swap transactions could be undertaken by the MFI/IFI concerned on a back-to-back basis with an authorised dealers (AD) Category-I bank in India. The tenure of such swaps should be at least three years, according to a notification issued by the central bank.

In the event of a default by the resident borrower on its swap obligations, the MFI/IFI concerned will have to bring in foreign currency funds to meet its corresponding liabilities to the counter-party AD Cat-I bank in India, the central bank said.

The AD Cat-I bank will have to report the FCY-INR swaps transactions entered into with the MFIs/IFIs on a back-to-back basis to CCIL reporting platform, including the details of the foreign currency borrower. Furthermore, the banks will have to bring the contents of this circular to the notice of their constituents and customers concerned.

Services sector growth hits 8-month high in October

India’s services sector activity touched an eight-month high in October driven by a significant rise in new business orders even as growth in manufacturing output eased, a Nikkei survey said.

The Nikkei Business Activity index climbed to 53.2 in October, from 51.3 in September, as fresh orders expanded at a solid pace and were most pronounced since February.

“Services companies saw a faster rise in new businesses than their manufacturing counterparts,” said Pollyanna De Lima, economist at Markit, which compiled the survey.

Meanwhile, the seasonally adjusted Nikkei India Composite PMI Output index, which maps manufacturing and services sectors, rose to 52.6 in October from 51.5 in September helped by new businesses.

A reading of 50 divides growth and contraction.

“India’s economic growth shifted into higher gear in October driven by the services sector. Although manufacturing production continued to expand, the growth eased and was sluggish by historical standards,” Lima added.

Lima noted that “the upward trend in private sector output reflected stronger inflows of incoming new works, one that was most marked since March”.

Going forward, services business sentiment regarding the 12-month business outlook remained positive in October.

Notwithstanding the growth in services activity, October data indicated that services sector employment remained unchanged. Around 98 per cent of respondents reported no change in payroll numbers since the preceding month.

“Private sector firms remained wary of costs and payroll numbers, once again, were unchanged,” Lima said.

On the prices front, the Nikkei survey said average input costs rose in both services and manufacturing sectors, albeit at a slower pace.

Reserve Bank Governor Raghuram Rajan on September 29 effected a more-than-expected interest rate cut of half a per cent to spur the economy.

Moreover, RBI has also lowered its economic growth forecast for the current fiscal to 7.4 per cent, from its previous projection of 7.6 per cent.

The April-June quarter GDP slipped to 7 per cent, from 7.5 per cent in the preceding quarter.

Source:http://economictimes.indiatimes.com/articleshow/49654978.cms?utm_source=contentofinterest&utm_medium=text&utm_campaign=cppst

Global re-insurers gearing up to open branch offices in India

Global reinsurance majors, such as Swiss Re, Munich Re and SCOR, have firmed up plans to apply for a composite licence to carry on reinsurance business through a branch office in India.

Last week, the Insurance Regulatory and Development Authority of India (IRDAI) released final regulations for registration and operation of branch offices by foreign re-insurers.

Currently, all global re-insurers have representative offices in India and operate from overseas while the Indian market has only one domestic re-insurer, General Insurance Corporation (GIC Re).

Kalpana Sampat, Principal Officer and Managing Director of Swiss Re, said the Indian direct insurance market has seen very good growth and the company plans to apply for the licence shortly to operate in a full-fledged manner in the domestic market.

Hitesh Kotak, Chief Representative for India at Munich Re, said the company is in the process of preparing its application for branch office in accordance with the Indian regulator’s requirements.

A representative of SCOR SE said the company intends to apply to the regulator for a composite licence. Ankur Nijhawan, Managing Director of Hannover Re, said his company is currently evaluating the regulations.

In its guidelines aimed at making it attractive for global re-insurers to set up operations in India, IRDAI has put in place a level-playing field for foreign re-insurers, which have a minimum retention of 50 per cent vis-à-vis the domestic re-insurer GIC Re. Minimum retention is the minimum amount of business that will be ceded to the re-insurer on an automatic basis to avoid the expenses associated with small cessions.

Swiss Re’s Sampat said the regulations allow an equal opportunity to the foreign re-insurer with an Indian branch, which in turn will help facilitate setting up a vibrant domestic reinsurance market.

Build local base

Industry experts also said that the presence of foreign re-insurers would help the Indian market developing technical expertise and underwriting skills.

Hitesh Kotak of Munich Re said, “We are keen to work on the best ways to combine Munich Re’s expertise and establish ourselves by closely working with clients and brokers to identify new opportunities.”

“We plan to achieve this through developing a strong local team which is closer to the clients and, at the same time equipped to explore our rich knowledge base and experience,” he added.

http://www.thehindubusinessline.com/money-and-banking/global-reinsurers-gearing-up-to-open-branch-offices-in-india/article7838538.ece?homepage=true

Finance Ministry to ease transfer pricing rules

The finance ministry is streamlining safe harbour rules and advance agreements, two mechanisms to determine the price of services rendered by a multinational to its subsidiary in India.

Safe harbour rules – directives on margins the tax authorities should accept for the transfer price declared by an assessee – have drawn a tepid response since they were introduced a couple of years ago. There is also a huge backlog in advance pricing agreements (APAs), an ahead-of-time understanding between a taxpayer and the tax authority on an appropriate transfer pricing methodology.

ALIGNING INDIAN TAXATION WITH BEST PRACTICES
Safe harbour rules

  • Government looking at lowering safe harbour margins to make it attractive for companies to opt for it
  • Government to make safe harbour definition unambiguous bringing in more clarity

Advance Pricing Agreement

  • With close to 550 cases pending, government looking at expediting clearances through:
  • Sector-specific approach to cases
  • Increasing manpower and filling up vacancies

The move would simplify the tax regime, reduce litigation and help improve the business environment, a finance ministry official said.

The steps will involve lowering the margins in safe harbour rules and definitions will be reworked to remove ambiguities. India announced the safe harbour rules in 2013, but the high margins of up to 25 per cent on total operational profits have made it unattractive for companies to use them.

“We are addressing issues related to transfer pricing to align it with best practices. We are revising the safe harbour rules that will include revisiting the definition and revising the margins, considered high by companies,” said a tax official.

Information technology (IT) and information technology-enabled services (ITeS) companies with transactions of up to Rs 500 crore have a safe harbour operating margin of 20 per cent and those with transactions above Rs 500 crore have a margin of 22 per cent. Knowledge process outsourcing companies have a safe harbour operating margin of 25 per cent.

Experts argue there is ambiguity in the definition of IT, ITeS and knowledge process outsourcing companies with a lot of overlap. Moreover, the margins decided in tribunals or in advance pricing agreements turn out much lower, ranging between 15 and 18 per cent.

“The definitions under the safe harbour rules are fuzzy and sometimes overlap, creating confusion over what rate should apply and which company will fall under which sector. We are expecting clarity on the definition,” said Rahul Garg, leader, direct tax, PwC.

Manisha Gupta, partner, Deloitte Haskins & Sells, said the safe harbour margins were high. “The government agrees to far lower rates at tribunals and in advance pricing agreements,” she said.

The lowering of safe harbour rates will ease the advance pricing agreement backlog. The government introduced the advance pricing scheme in 2012 and there are over 500 applications pending.

“We are considering sector-wise handling of cases by officers to expedite decisions,” the tax official said. “We have already made a request for an increase in manpower to clear the backlog. We expect a decision soon,” he added.

India has the highest incidence of transfer pricing litigation worldwide. The number of cases scrutinised has quadrupled from 1,061 in 2005-06 to 4,290 in 2014-15.

Among measures recently introduced, the government said an officer would be assigned not more than 50 important and complex transfer pricing cases. Officers typically audit more than 70 cases at a time.

Besides, the tax department has incorporated range and multi-year data in transfer pricing calculations to bring Indian laws in line with international practices. Earlier, single-year data and the arithmetic mean were used to arrive at transfer pricing.

Earlier this year, the finance ministry allowed rollback advance pricing agreements so that multinational companies could settle taxes for previous years as well.

“The burden on tribunals, high courts, Supreme Court and even on the APA team can be substantially reduced if the Indian government revamps the safe harbour rules (that is, devising calibrated and more reasonable margins for the sector consistent with the margins finally arrived at post-tribunal orders/MAP/APA and providing clarifications on what constitutes software development activities, KPO, contract R&D,” said a Deloitte & Taxsutra report on transfer pricing.

Approximately over 40 per cent of APA applications are from the IT/ITeS sector. Up to September 2015, more than 575 APA applications have been filed with the APA authorities. Fourteen of these APAs have been concluded, of which 12 are unilateral and two bilateral (with Japan and the UK).

Source:Business Standard